

Vaccine biotechnology company Novavax (NASDAQ:NVAX) beat Wall Street’s revenue expectations in Q3 2026, but revenue fell by 3% year on year to $68.3 million. The company’s full-year revenue guidance of $400 million at the midpoint came in 4.2% above analysts’ consensus estimates. Its GAAP loss of $0.19 per share was 45.1% above analysts’ consensus estimates.
For more on Novavax, read our free full research report.
Novavax (NVAX) Q3 2026 highlights:
- Revenue $68.3 million vs S&P analysts’ consensus estimates of $44.81 million (3% year-on-year decline, 52.4% beat)
- EPS (GAAP) -$0.19 vs analysts’ consensus estimates of -$0.35 (45.1% beat)
- Operating margin -45.8%, up from -253% in the same quarter last year
- Market capitalization $1.76 billion
"This quarter, we continued to execute across all three pillars of our strategy," said John C. Jacobs, President and Chief Executive Officer, Novavax. "Our partner Sanofi initiated their Phase 3 influenza-COVID-19 combination vaccine trial vaccine trial in Europe, triggering a $125 million milestone payment. Our focused R&D efforts are building a growing body of data on what our technology can do in infectious disease, advancing our C. difficile candidate towards the clinic and exploring oncology as a potential new area of application. And we have been doing this while continuing to reduce expenses and operate with financial discipline. Over time, we believe this strategy can build a robust and profitable Novavax, with multiple partners and products, diversified revenue streams and a meaningful impact on global health."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Novavax’s demand was weak over the last five years as its revenue fell at a 19.3% annual rate. That decline points to poor business quality.
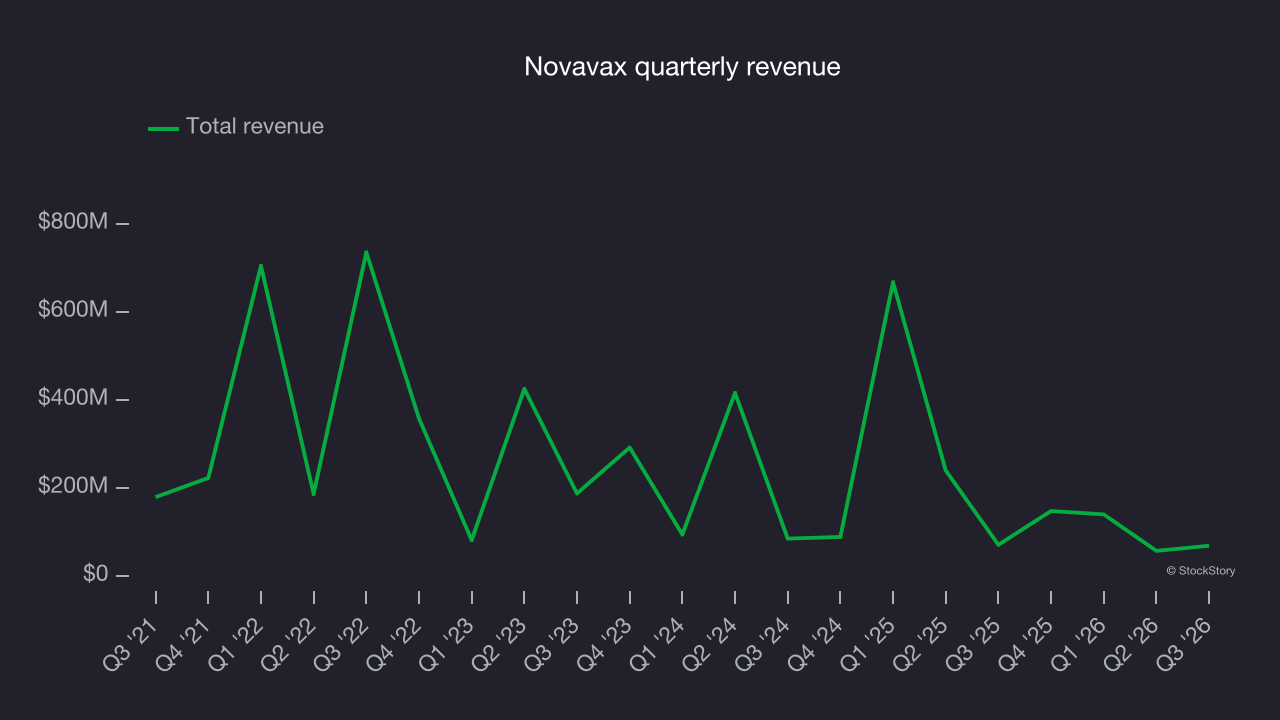
Long-term growth is the most important, but within healthcare, a half-decade historical view may miss new innovations or demand cycles. Novavax’s recent performance shows its demand remained suppressed as its revenue has declined by 31.8% annually over the last two years. 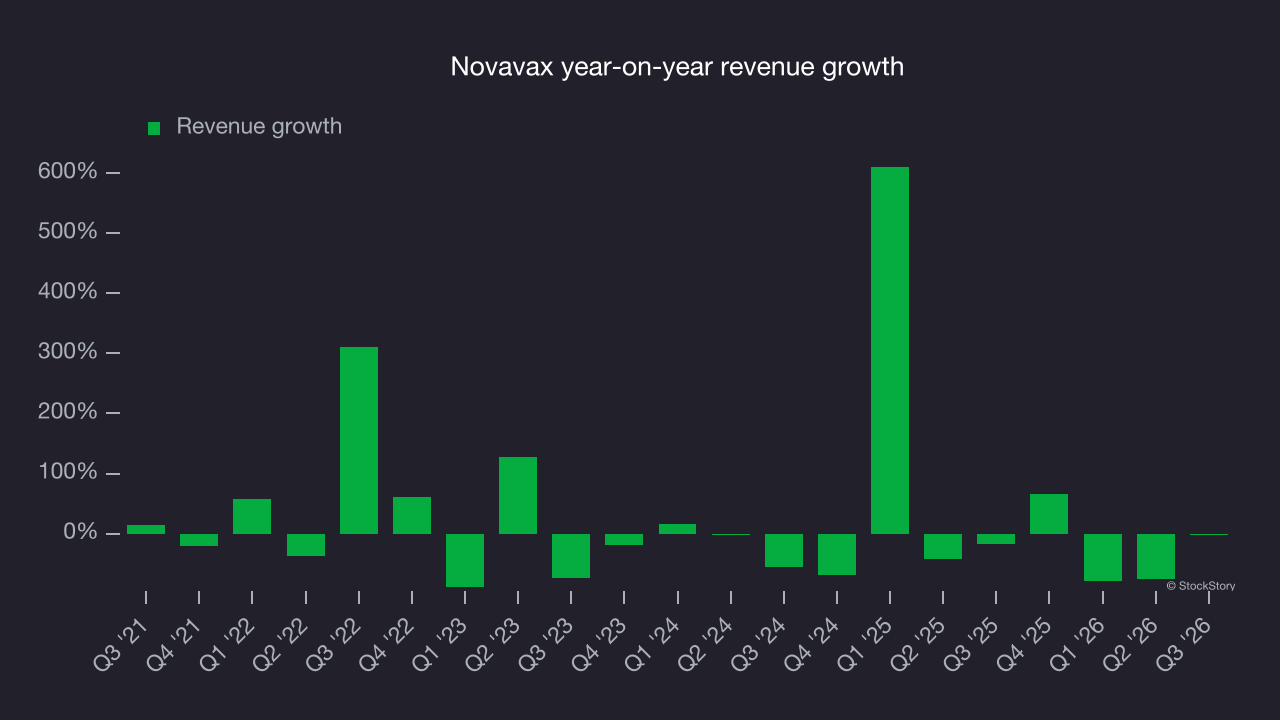
This quarter, Novavax’s revenue fell by 3% year on year to $68.3 million but beat Wall Street’s consensus estimates by 52.4%.
Looking ahead, sell-side analysts expect revenue to decline by 3.9% over the next 12 months, according to S&P. Although this projection is better than its two-year trend, the company’s demand difficulties remain a concern.
Adjusted operating margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt and taxes.
Novavax’s high expenses have contributed to an average adjusted operating margin of negative 36.8% over the last five years. Unprofitable healthcare companies require extra scrutiny because they may be vulnerable in a downturn. It’s hard to be confident that the business can endure a full cycle.
On the positive side, Novavax’s adjusted operating margin rose by 45.2 percentage points over the last five years. More recent performance shows that trajectory remains intact, as its margin has also increased by 12.8 percentage points on a two-year basis.
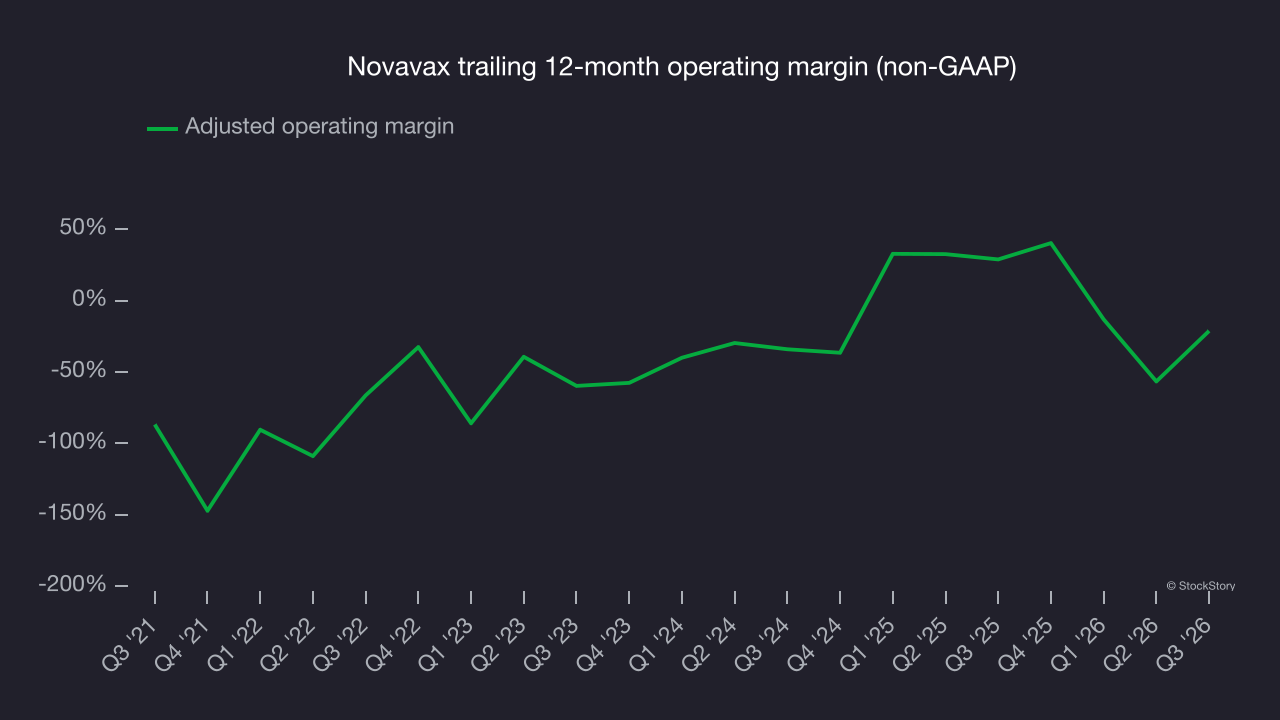
This quarter, Novavax generated a negative 45.8% adjusted operating margin. The company’s consistent lack of profits raises concerns.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Although Novavax’s full-year earnings are still negative, it reduced its losses and improved its EPS by 49.9% annually over the last five years. The next few quarters will be critical for assessing its long-term profitability.
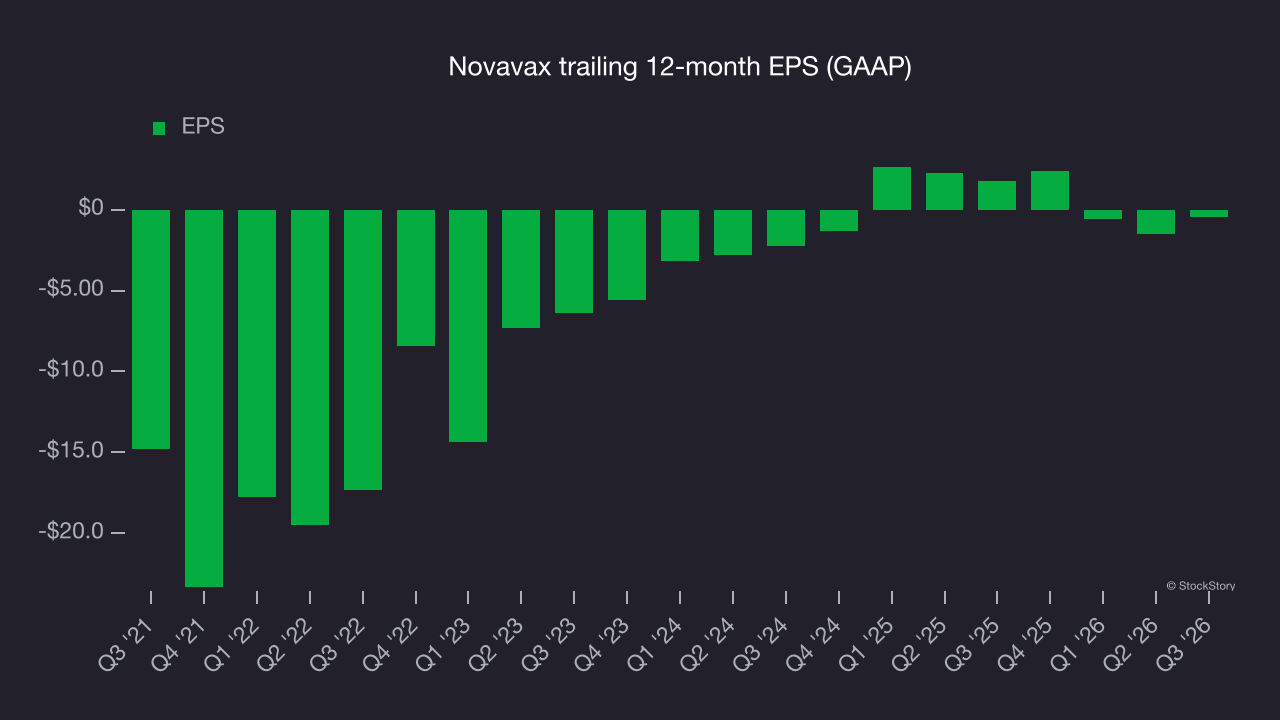
In Q3, Novavax reported EPS of negative $0.19, up from negative $1.25 in the same quarter last year. This result beat analysts’ consensus estimates by a wide margin, a positive for shareholders. The outlook is positive as well: analysts forecast Novavax’s full-year EPS will turn positive over the next 12 months, rising from negative $0.47 to positive $0.17, according to S&P.
Key takeaways from Novavax’s Q3 results
Novavax delivered a solid Q3, with revenue well ahead of Wall Street’s consensus estimates and EPS also topping analysts’ consensus estimates. Those beats were key positives, but the market seemed to be hoping for more. Shares edged lower 1.8% to $10.48 immediately after the results.
When deciding whether to buy the stock, the latest quarter matters, but not nearly as much as longer-term fundamentals and valuation. Read more in the full research report here (it’s free).