

Home warranty company Frontdoor (NASDAQ:FTDR) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 6% year on year to $655 million. Guidance for next quarter’s revenue was better than expected at $458 million at the midpoint, 0.8% above analysts’ consensus estimates. Its non-GAAP profit of $1.81 per share was 2% above analysts’ consensus estimates.
For more on Frontdoor, read our free full research report.
Frontdoor (FTDR) Q3 2026 highlights:
- Revenue $655 million vs S&P analysts’ consensus estimates of $647.6 million (6% year-on-year growth, 1.1% beat)
- Adjusted EPS $1.81 vs S&P analysts’ consensus estimates of $1.77 (2% beat)
- Adjusted EBITDA $205 million vs analysts’ consensus estimates of $203.6 million (31.3% margin, 0.7% beat)
- Revenue guidance $458 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $454.2 million
- EBITDA guidance $595 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 28.7%, compared with 25.2% in the same quarter last year
- Free cash flow margin 9.9%, similar to the same quarter last year
- Market capitalization $6.40 billion
"I am proud of how our team produced strong third-quarter results while providing exceptional service for our members during the hottest summer on record," said Chairman and Chief Executive Officer Bill Cobb. "Our team continues to rise to the challenge and find new ways to improve our operations and elevate the member experience. These outcomes reflect the value we provide homeowners, the dedication of our people, and the durability of our business model."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Frontdoor’s revenue grew at a weak 6.6% annualized rate over the last five years, falling short of the consumer discretionary sector benchmark.
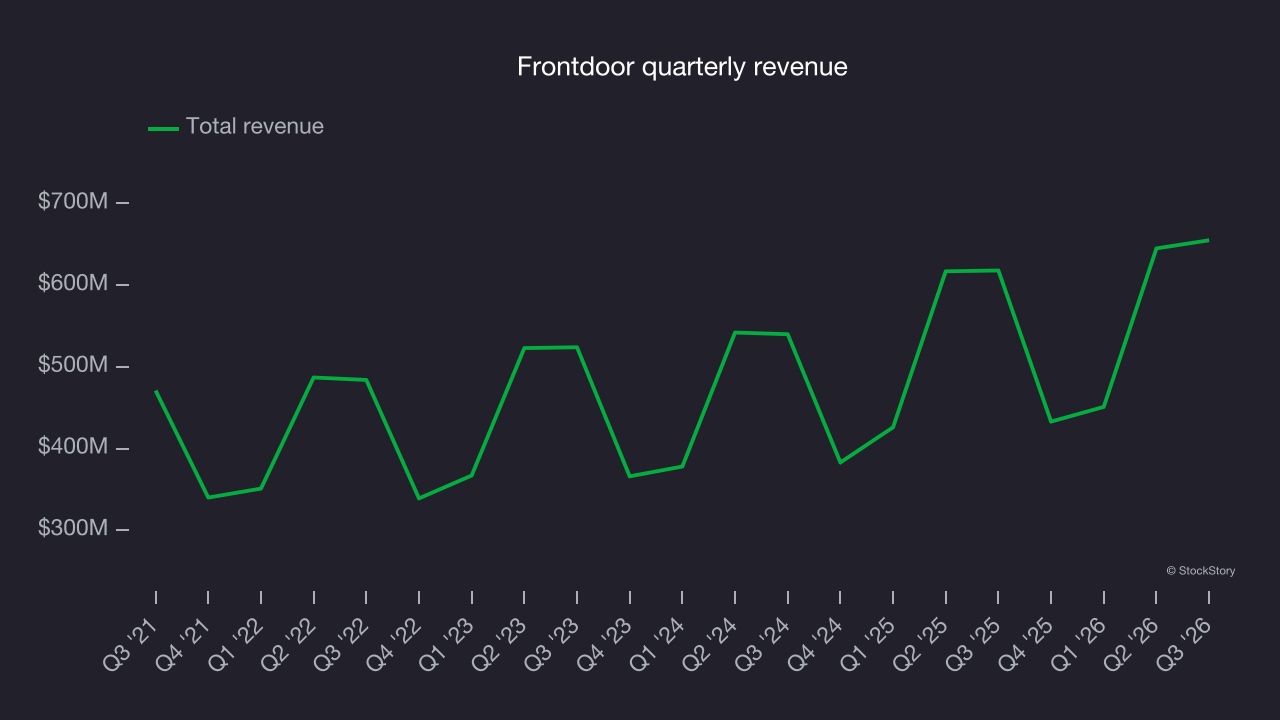
Long-term growth matters most, but within consumer discretionary, a longer historical view may miss a company riding a successful new product or trend. Frontdoor’s annualized revenue growth of 9.4% over the last two years is above its five-year trend, a positive sign. 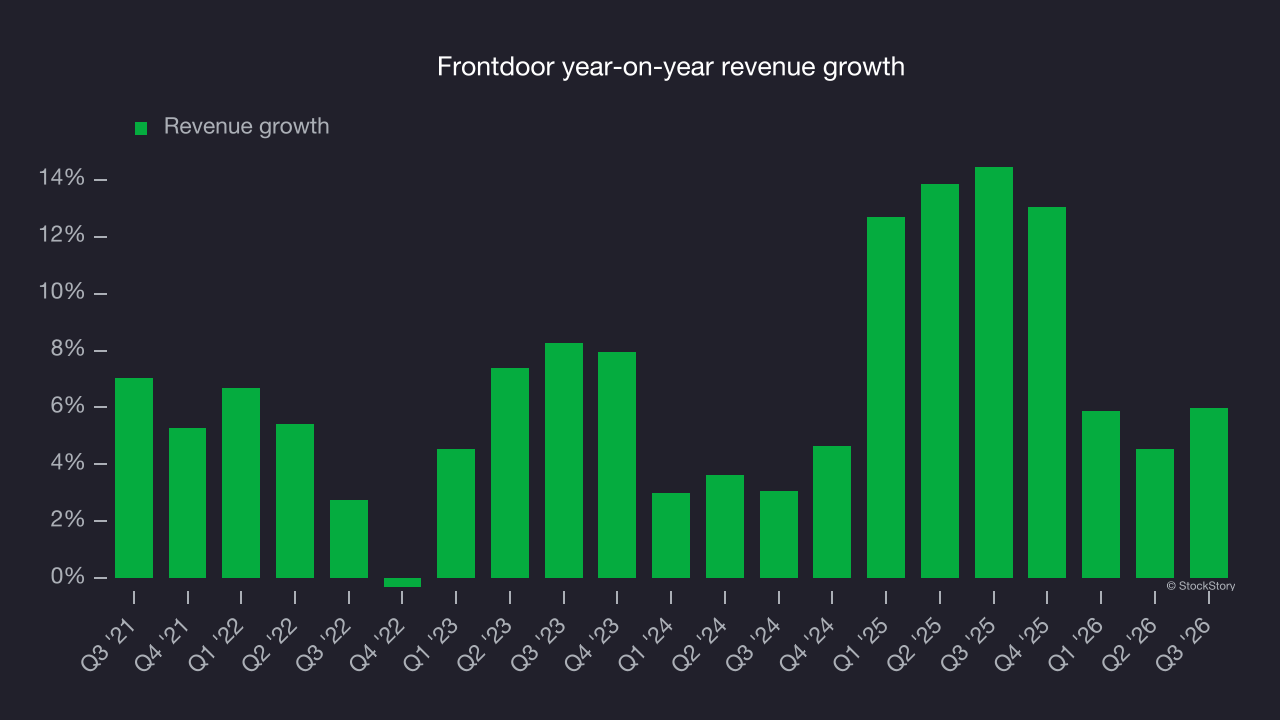
This quarter, Frontdoor reported year-on-year revenue growth of 6%, and its $655 million of revenue exceeded Wall Street’s consensus estimates by 1.1%. Management is guiding for a 5.8% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 5.1% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and indicates its products and services will face some demand challenges.
Operating margin
Frontdoor’s operating margin has been trending up over the last 12 months and averaged 20% over the last two years. The company’s improved efficiency is a positive, but its suboptimal cost structure means profitability remains poor for a consumer discretionary business.
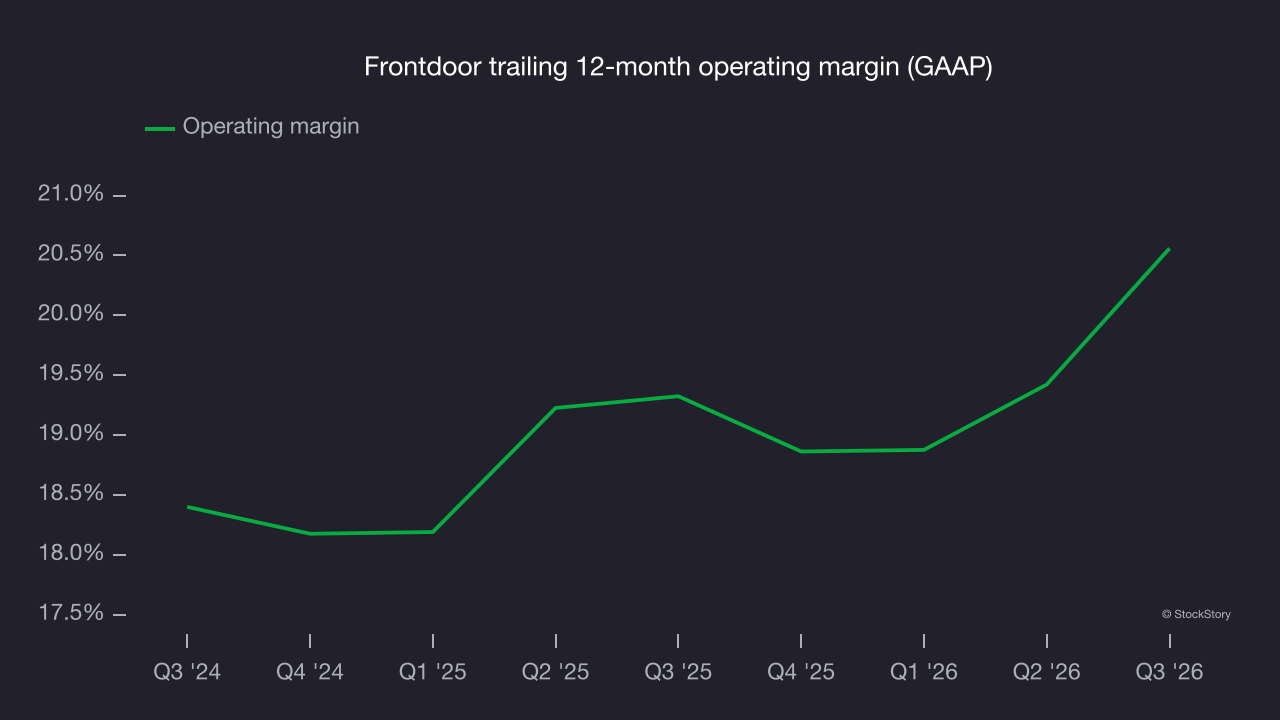
In Q3, Frontdoor generated an operating margin of 28.7%, up 3.5 percentage points year on year. This increase was a positive development, reflecting greater efficiency.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Frontdoor’s EPS grew at a 20.5% compounded annual growth rate over the last five years. On the positive side, this outpaced its 6.6% annualized revenue growth, indicating the company became more profitable on a per-share basis as it expanded.
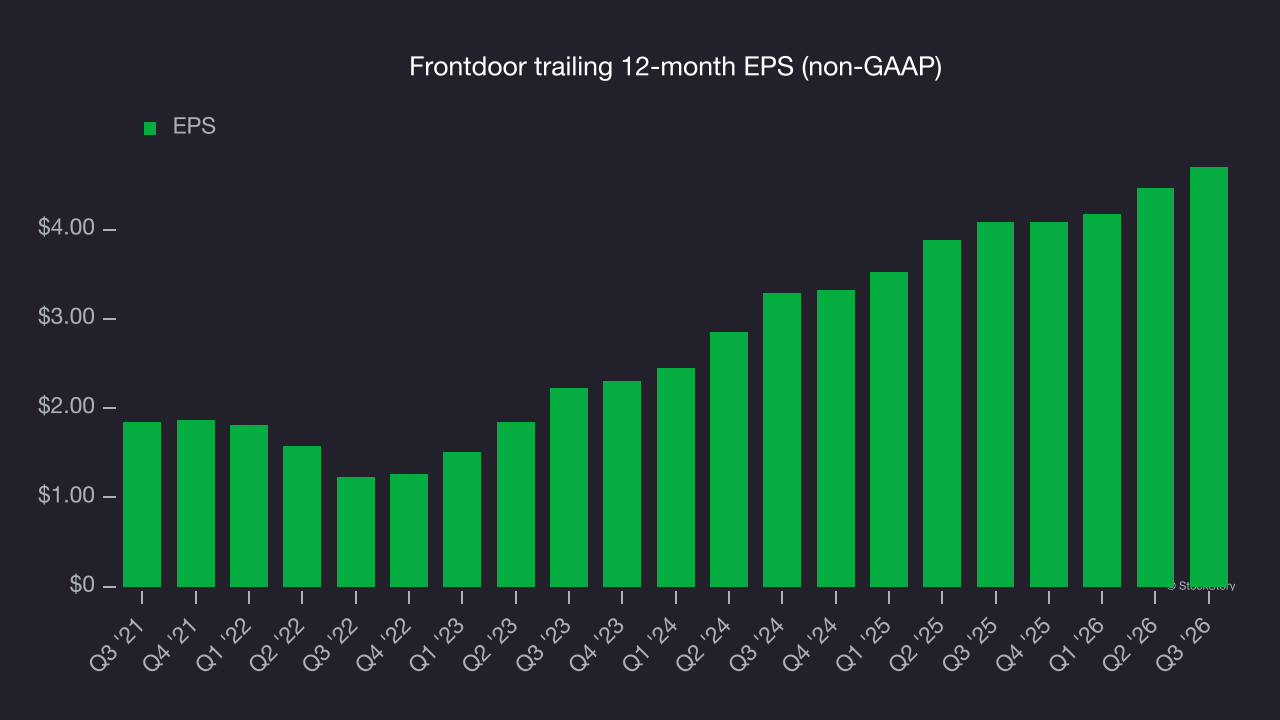
In Q3, Frontdoor reported adjusted EPS of $1.81, up from $1.58 in the same quarter last year. This result beat analysts’ consensus estimates by 2%. Over the next 12 months, Wall Street expects Frontdoor’s full-year EPS to grow 7.1% from $4.70 to $5.03, according to S&P.
Key takeaways from Frontdoor’s Q3 results
Frontdoor’s outlook offered some key positives: EBITDA guidance for next quarter topped analysts’ consensus estimates, and revenue guidance came in slightly above Wall Street’s consensus. Shares remained flat at $92.86 immediately after the results.
When assessing Frontdoor as an investment, it’s important to consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).