

Luxury furniture retailer Arhaus (NASDAQ:ARHS) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 6.8% year on year to $368.1 million. On the other hand, next quarter’s outlook exceeded expectations with revenue guided to $408 million at the midpoint, or 4.1% above analysts’ consensus estimates. Its GAAP profit of $0.05 per share was 41.7% below analysts’ consensus estimates.
For more on Arhaus, read our free full research report.
Arhaus (ARHS) Q3 2026 highlights:
- Revenue $368.1 million vs S&P analysts’ consensus estimates of $370.6 million (6.8% year-on-year growth, 0.7% miss)
- EPS (GAAP) $0.05 vs analysts’ consensus estimates of $0.09 (41.7% miss)
- Adjusted EBITDA $27.39 million vs analysts’ consensus estimates of $31.86 million (7.4% margin, 14.1% miss)
- Revenue guidance $408 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $391.8 million
- EBITDA guidance $165.5 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Operating margin 2.7%, down from 4.8% in the same quarter last year
- Free cash flow margin 25%, up from 8.1% in the same quarter last year
- Locations 109 at quarter end, up from 103 in the same quarter last year
- Same-store sales rose 2.6% year on year (4.1% in the same quarter last year)
- Market capitalization $1.86 billion
“For 40 years, Arhaus has been defined by exceptional craftsmanship, timeless design, and distinctive products. Our continued investment in compelling new collections and expanded customization is resonating with clients, as reflected in third-quarter Comparable Written Sales(2) growth of 13.9%. As we celebrate our 40th anniversary, we remain excited about the opportunity to bring our unique product offering to more clients and build on our momentum.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but many enduring ones grow for years.
With $1.43 billion in revenue over the past 12 months, Arhaus is a small retailer, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with suppliers.
Arhaus grew its revenue at a sluggish 3.3% compounded annual growth rate over the last three years as it barely increased revenue at existing, established locations.
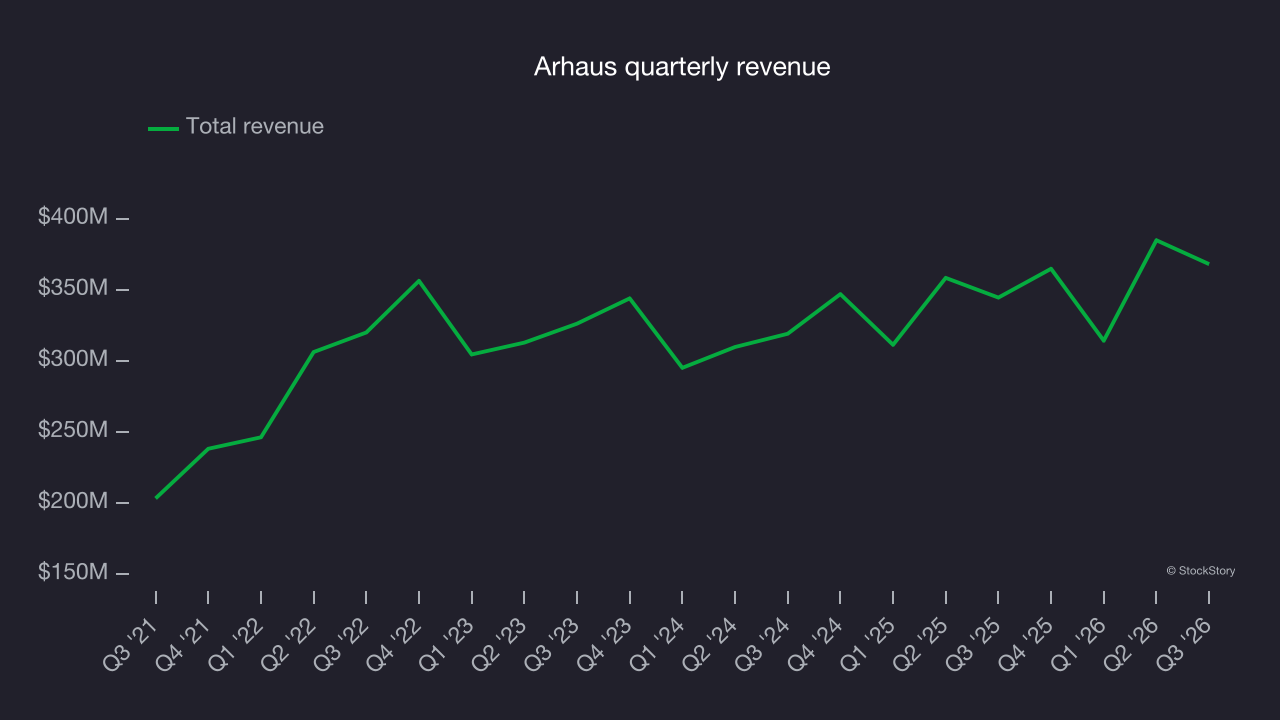
This quarter, Arhaus’s revenue grew by 6.8% year on year to $368.1 million, missing Wall Street’s consensus estimates. Company management is currently guiding for an 11.8% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 7.2% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is noteworthy and implies its newer products will spur better top-line performance.
Store performance
Number of stores
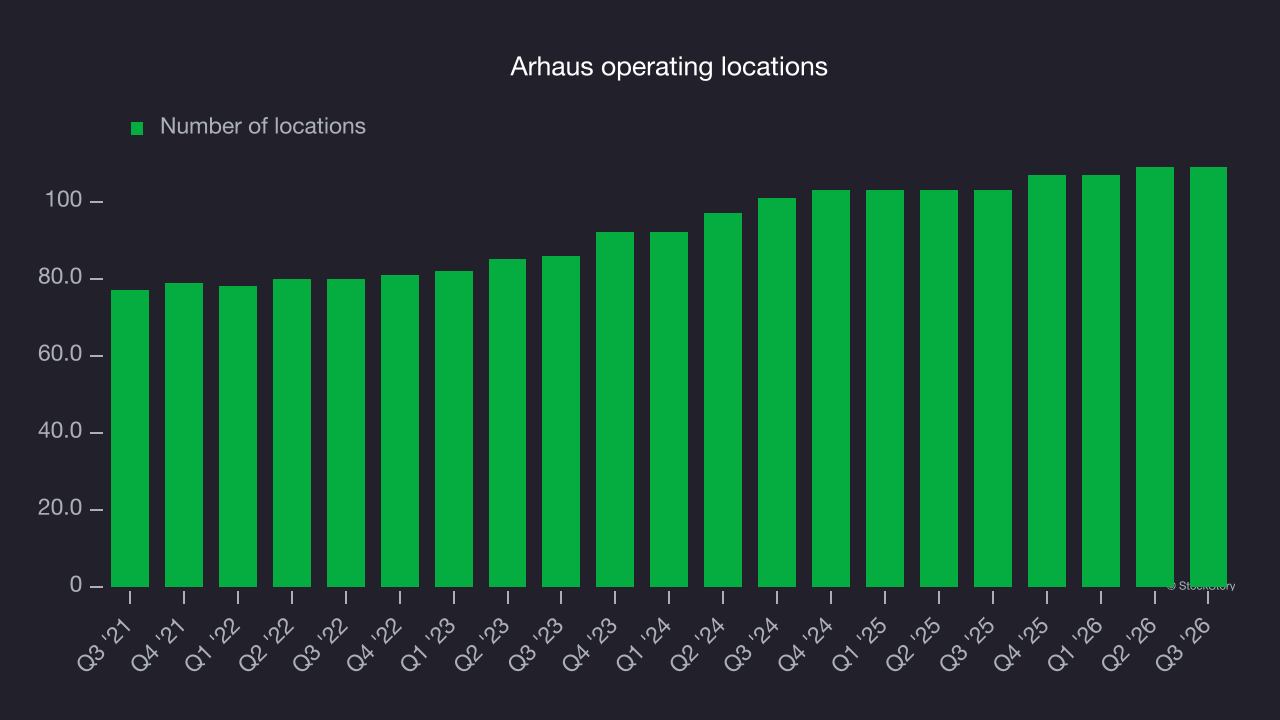
Arhaus had 109 locations in the latest quarter. Over the last two years, its store count has grown at a rapid pace, averaging 6.4% annual growth, among the fastest in the consumer retail sector. This gives it a chance to scale into a mid-sized business over time.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
Same-store sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales is an industry measure of whether revenue is growing at those existing stores and is driven by customer visits (often called traffic) and the average spending per customer (ticket).
Arhaus’s demand within its existing locations has been relatively stable over the last two years but was below most retailers. On average, the company’s same-store sales have grown by 1.6% per year. This performance suggests it should consider improving its foot traffic and efficiency before expanding its store base.
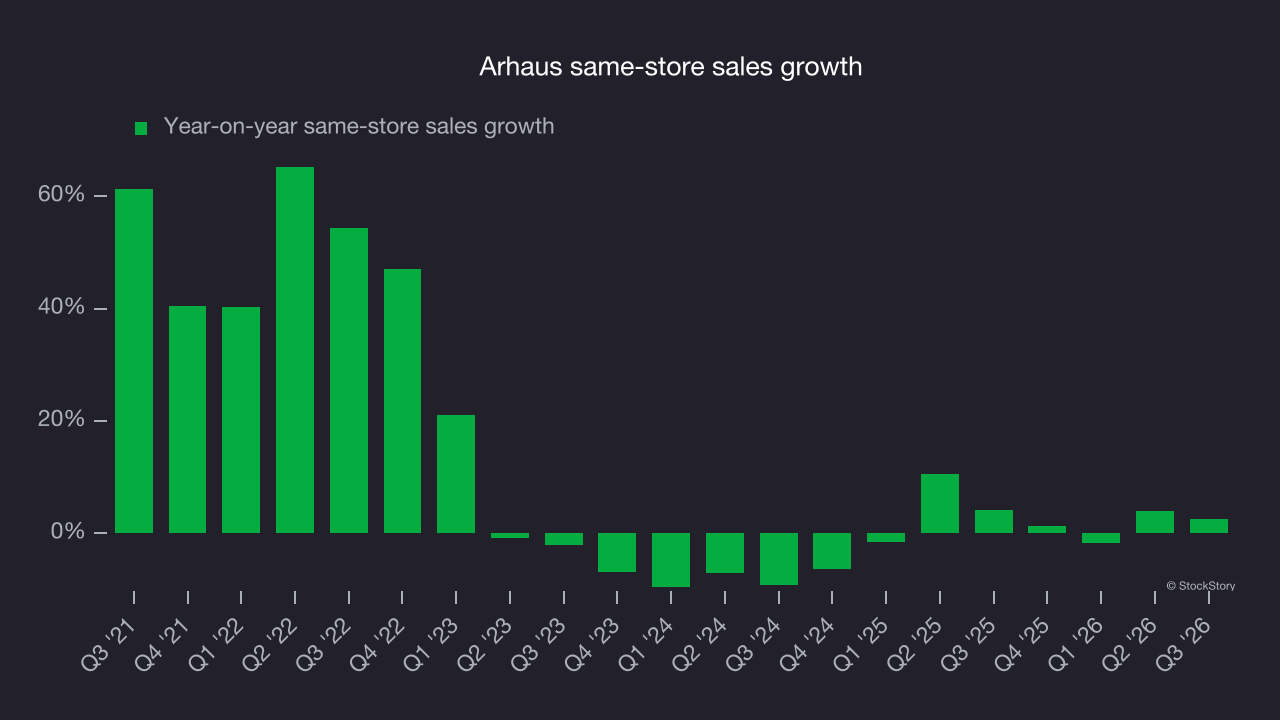
In the latest quarter, Arhaus’s same-store sales rose 2.6% year on year. This performance was more or less in line with its historical levels.
Key takeaways from Arhaus’s Q3 results
Q3 EBITDA and EPS both fell short of Wall Street’s consensus estimates, leaving a quarter that could have been better. Shares remained flat at $13.14 immediately after the release.
Arhaus’s latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).