

Ride sharing and on-demand delivery platform Uber (NYSE:UBER) met Wall Street’s revenue expectations in Q3 2026, with revenue up 9.6% year on year to $14.77 billion. Its non-GAAP profit of $0.88 per share was 1.5% above analysts’ consensus estimates.
For more on Uber, read the full research report for free.
Uber (UBER) Q3 2026 highlights:
- Revenue $14.77 billion vs S&P analysts’ consensus estimates of $14.7 billion (9.6% year-on-year growth, in line)
- Adjusted EPS $0.88 vs S&P analysts’ consensus estimates of $0.87 (1.5% beat)
- Adjusted EBITDA $2.96 billion vs analysts’ consensus estimates of $2.92 billion (20.1% margin, 1.3% beat)
- Adjusted EPS guidance $0.97 at the midpoint for the full year, missing analysts’ consensus estimates by 71.1%
- Operating margin 9.8%, up from 8.3% in the same quarter last year
- Free cash flow margin 17.2%, down from 19.7% in the previous quarter
- Monthly active platform consumers 215 million, up 26 million year on year
- Market capitalization $136 billion
“Uber delivered its fifth consecutive quarter of 20%+ Gross Bookings growth, driven by record audience and consumer engagement,” said Dara Khosrowshahi, CEO. “We’re investing from a position of strength to expand Mobility supply, build on Delivery’s momentum, and deepen engagement across our platform. Our focus on autonomous is now on commercial execution, with approximately 700 fully driverless vehicles expected on Uber by year-end and over 2,000 in 2027.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Over the last three years, Uber grew its revenue at a solid 16.3% compounded annual growth rate. Its growth surpassed the average consumer internet company and shows its offerings resonate with customers.
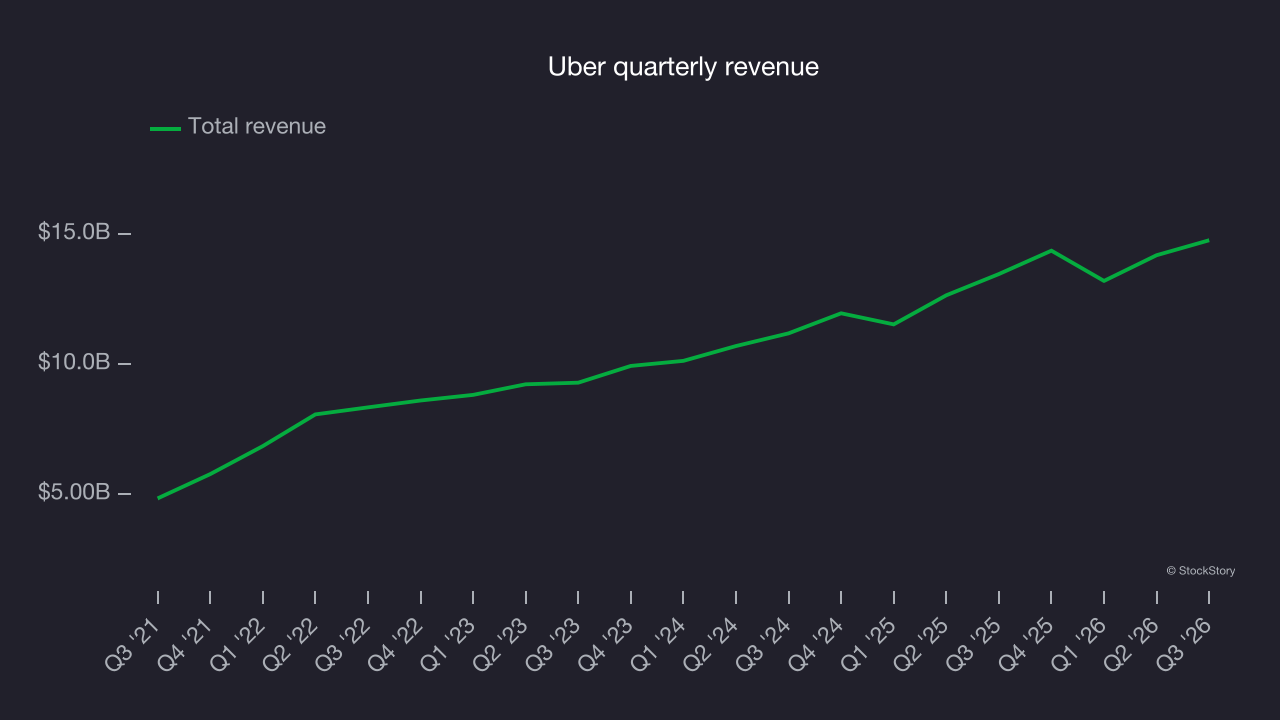
This quarter, Uber grew its revenue by 9.6% year on year, and its $14.77 billion in revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 14% over the next 12 months, according to S&P, a slight deceleration versus the last three years. Its growth trajectory remains attractive given its scale and suggests the market is forecasting success for its products and services.
Monthly active platform consumers
User growth
As a gig economy marketplace, Uber generates revenue growth by expanding the number of services on its platform (e.g. rides, deliveries, freelance jobs) and raising the commission fee from each service provided.
Over the last two years, Uber’s monthly active platform consumers, a key performance metric for the company, increased by 15.7% annually to 215 million in the latest quarter. This growth rate is among the fastest of any consumer internet business and indicates its offerings have significant traction. 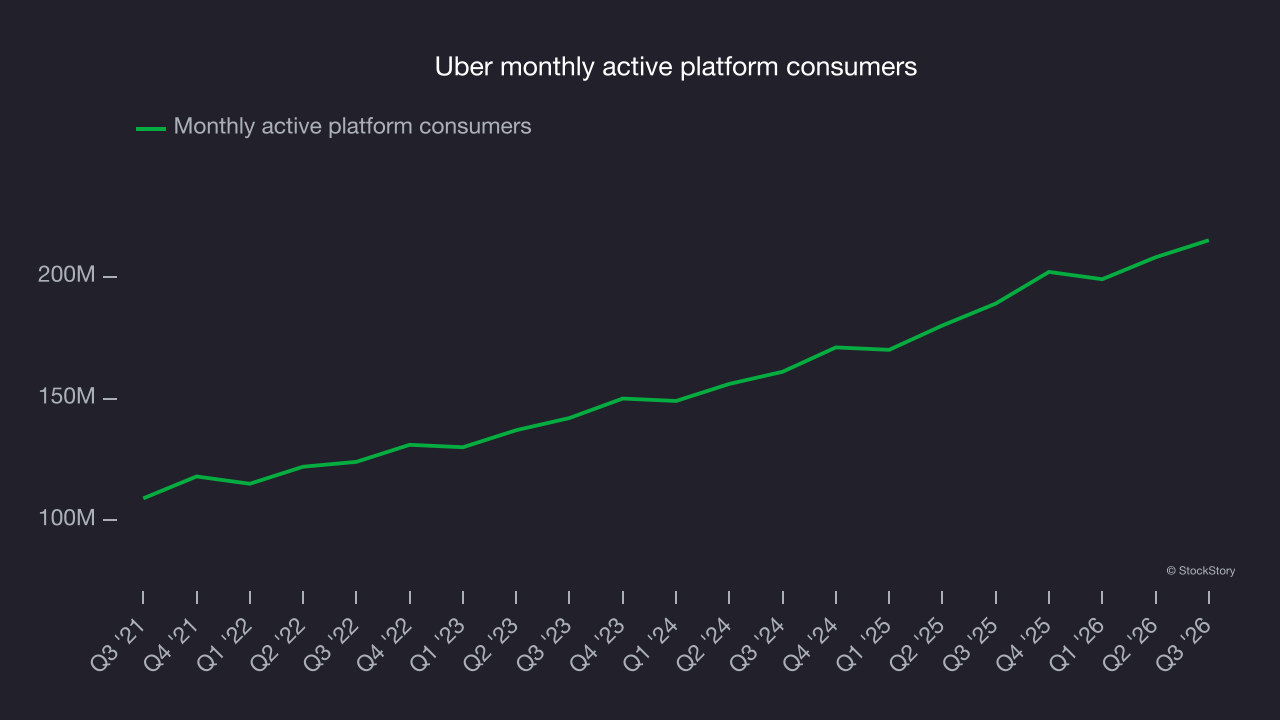
In Q3, Uber added 26 million monthly active platform consumers, leading to 13.8% year-on-year growth. The quarter’s growth rate was lower than its two-year result, suggesting its new initiatives aren’t accelerating user growth just yet.
Revenue per user
Average revenue per user, or ARPU, is a critical metric to track because it measures how much the company earns in transaction fees from each user. This number also offers insight into Uber’s take rate, which represents its pricing leverage over the ecosystem, or “cut” from each transaction.
Uber’s ARPU has been roughly flat over the last two years. That is underwhelming, but the increase in monthly active platform consumers is more relevant for assessing long-term business potential. The trend bears watching; if Uber tries boosting ARPU by taking a more aggressive approach to monetization, it’s unclear whether its user base can continue growing at the current pace. 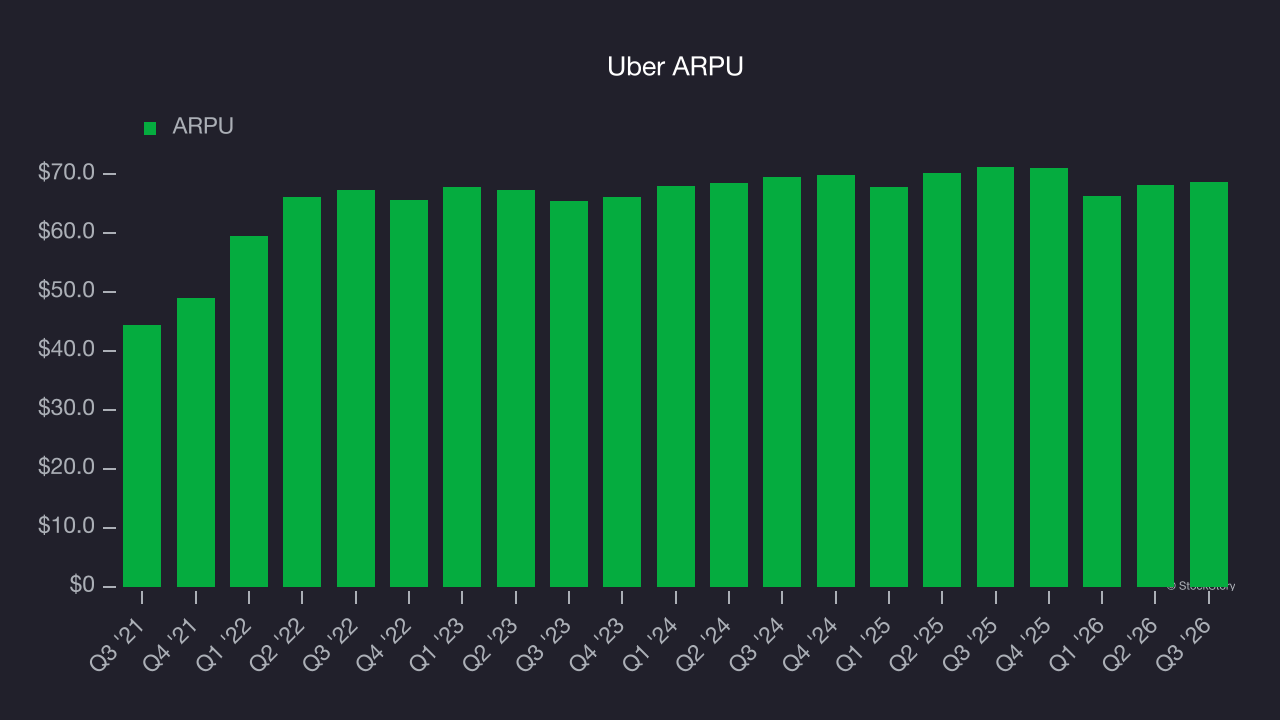
This quarter, Uber’s ARPU was $68.68. It declined 3.6% year on year, worse than the change in its monthly active platform consumers.
Key takeaways from Uber’s Q3 results
Uber added users and narrowly beat Wall Street’s EBITDA consensus this quarter, but its full-year EPS guidance fell short of expectations. That guidance miss left room for a better quarter overall. Shares remained flat at $67.04 immediately after the report.
Uber’s latest quarter matters when deciding whether to invest in the stock, but not as much as longer-term business quality and valuation. Read the full research report here (it’s free).