

Financial services company Primerica (NYSE:PRI) announced better-than-expected revenue in Q3 2026, with revenue up 7.5% year on year to $901.7 million. Its non-GAAP profit of $6.77 per share was 6% above analysts’ consensus estimates.
For more on Primerica, read our free full research report.
Primerica (PRI) Q3 2026 highlights:
- Net premiums earned $453.6 million vs analysts’ consensus estimates of $466.6 million (flat year on year, 2.8% miss)
- Revenue $901.7 million vs S&P analysts’ consensus estimates of $894.6 million (7.5% year-on-year growth, 0.8% beat)
- Pre-tax profit $271.9 million (30.2% margin)
- Adjusted EPS $6.77 vs S&P analysts’ consensus estimates of $6.38 (6% beat)
- Market capitalization $8.62 billion
"In the third quarter, Primerica’s financial performance underscored the consistency of our business fundamentals, driven by our unique operating model that is purpose-built to help middle-income families achieve financial security," said Glenn Williams, Chief Executive Officer. "Stable earnings in our Term Life segment and record investment sales continue to drive earnings momentum. These results reflect the dedication of our independent sales force and their commitment to helping families build a more secure future."
Revenue growth
Insurance companies generate revenue three ways. The first is the core insurance business itself, represented in the income statement as premiums earned. The second source is investment income from investing the “float” (premiums collected but not yet paid out as claims) in assets such as fixed-income assets and equities. The third is fees from policy administration, annuities and other value-added services. Primerica’s 6.2% annualized revenue growth over the last five years was mediocre compared with the rest of the insurance sector, but there are still things to like about Primerica.
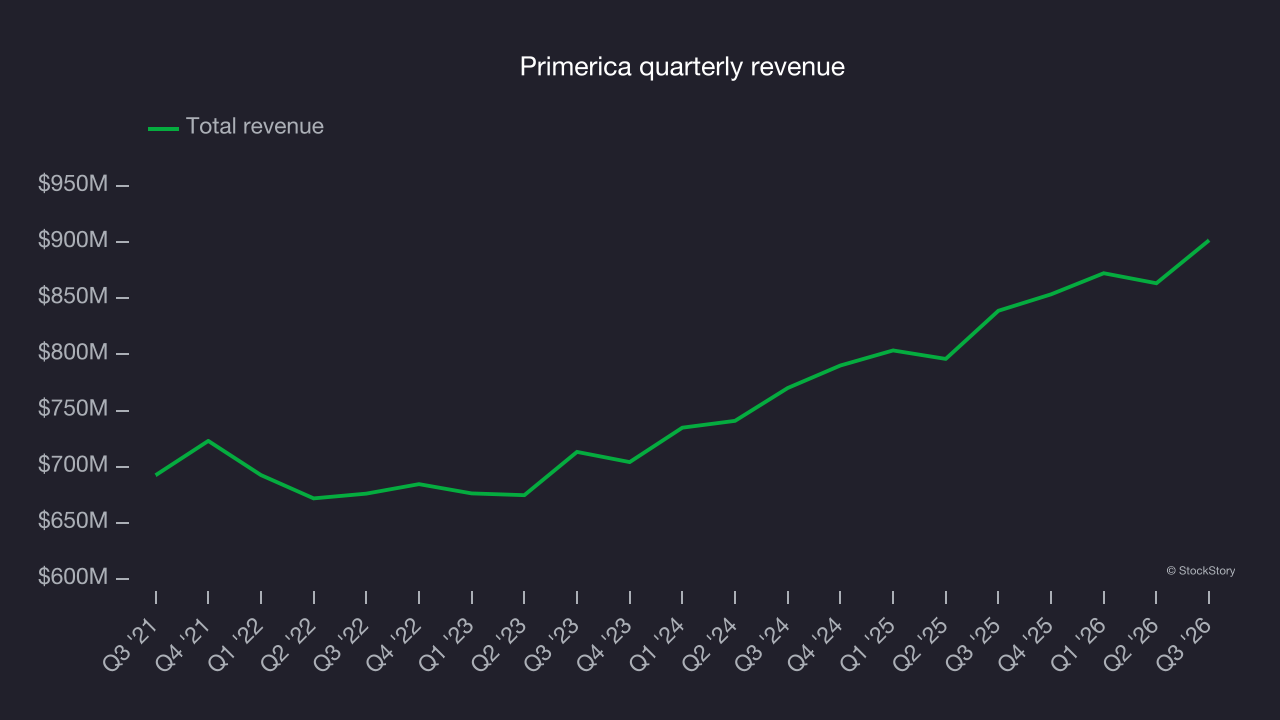
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Primerica’s annualized revenue growth of 8.8% over the last two years is above its five-year trend, suggesting some bright spots. 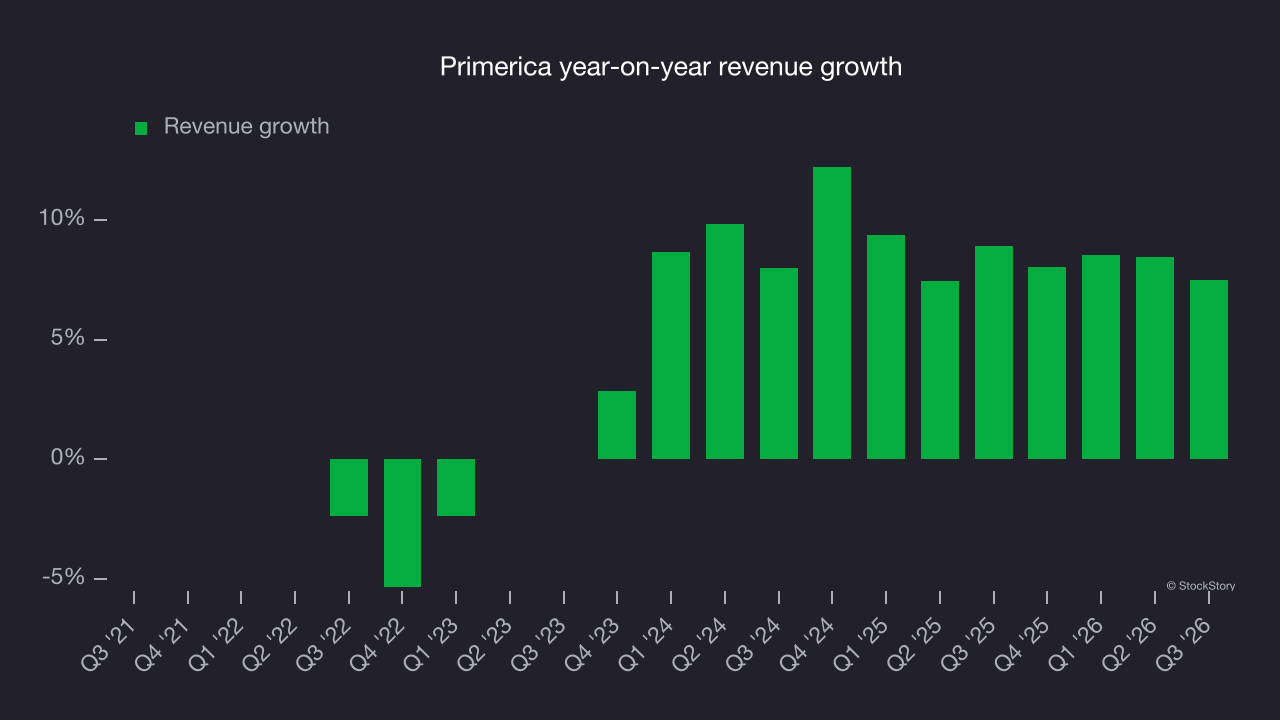 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Primerica reported year-on-year revenue growth of 7.5%, and its $901.7 million of revenue exceeded Wall Street’s consensus estimates by 0.8%.
Net premiums earned made up 55.9% of the company’s total revenue during the last five years, reflecting a balance between insurance and non-insurance growth drivers.
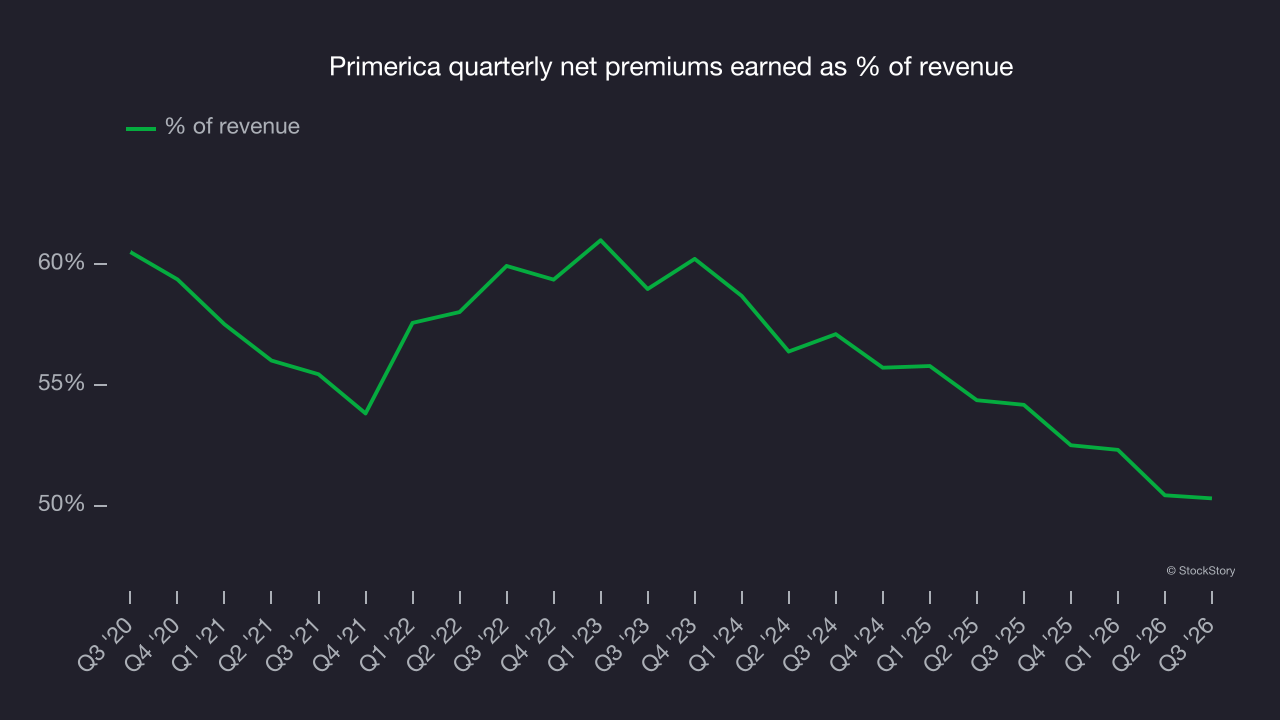
Markets consistently prioritize net premiums earned growth over investment and fee income, recognizing its superior quality as a core indicator of the company’s underwriting success and market penetration.
Net premiums earned
When insurers sell policies, they protect themselves from extremely large losses or an outsized accumulation of losses with reinsurance (insurance for insurance companies). Net premiums earned are therefore gross premiums less what’s ceded to reinsurers as a risk mitigation and transfer strategy.
Primerica’s net premiums earned have grown at a 4.1% annualized rate over the last five years, worse than the broader insurance industry and slower than its total revenue.
Primerica’s net premiums earned growth decelerated to 2.3% annually over the last two years. Net premiums earned grew more slowly than total revenue over this period, implying that other line items such as investment income grew at a faster rate. These extra revenue streams are important to the bottom line, yet their performance can be inconsistent. Some firms have been more successful and consistent in managing their float, but sharp fluctuations in the fixed income and equity markets can significantly affect short-term results.
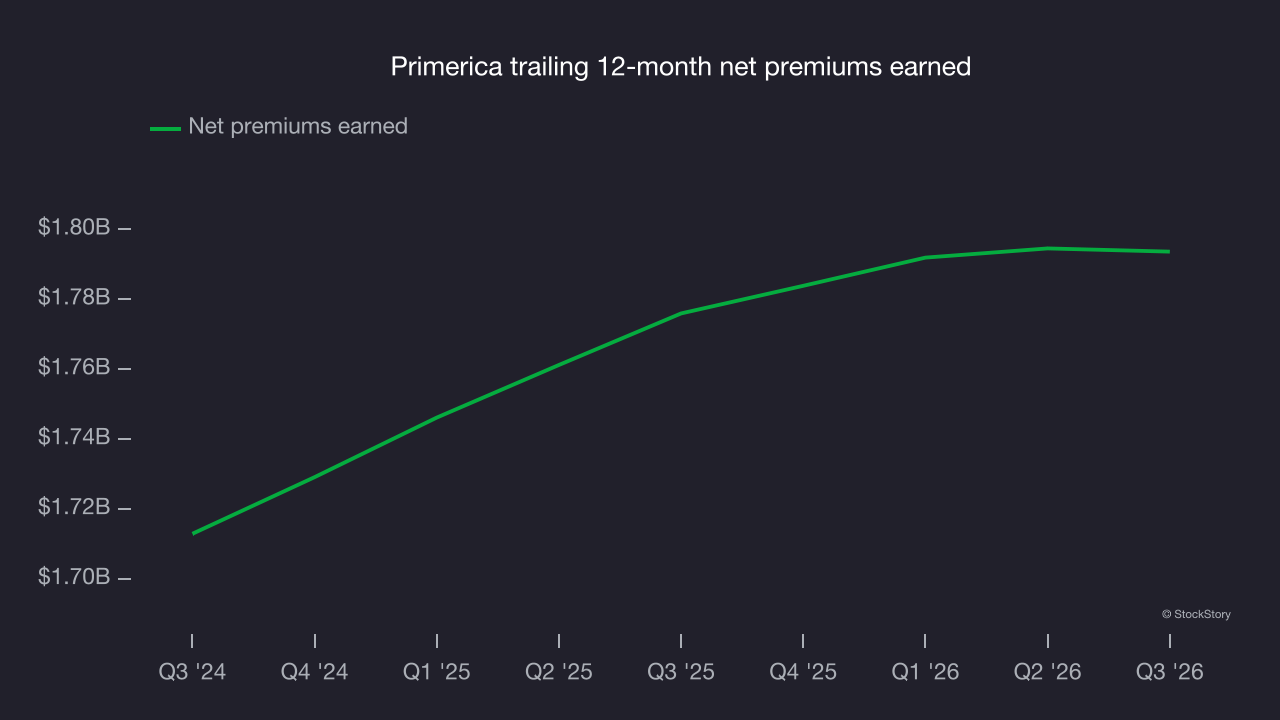
This quarter, Primerica’s net premiums earned totaled $453.6 million, flat year on year and short of Wall Street’s consensus estimates.
Key takeaways from Primerica’s Q3 results
Primerica’s quarter was softer overall: revenue narrowly topped analysts’ consensus estimates, but net premiums earned fell short of expectations. Shares edged higher 1.1% to $287.50 immediately after the results.
To assess Primerica at its current price, consider valuation and business quality as well as the latest earnings. For more on Primerica, read our full research report here (it’s free).