

HR software provider Paycom (NYSE:PAYC) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 10.2% year on year to $543.8 million. The company expects the full year’s revenue to be around $2.22 billion, close to analysts’ consensus estimates. Its non-GAAP profit of $3.37 per share was 20.4% above analysts’ consensus estimates.
For more on Paycom, read our full research report, available free.
Paycom (PAYC) Q3 2026 highlights:
- Revenue $543.8 million vs S&P analysts’ consensus estimates of $535.9 million (10.2% year-on-year growth, 1.5% beat)
- Adjusted EPS $3.37 vs S&P analysts’ consensus estimates of $2.80 (20.4% beat)
- Adjusted EBITDA $268.1 million vs analysts’ consensus estimates of $235.7 million (49.3% margin, 13.7% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $2.22 billion at the midpoint from $2.2 billion
- EBITDA guidance $1.07 billion at the midpoint for the full year, above analysts’ consensus estimates of $1.01 billion
- Operating margin 36%, up from 22.8% in the same quarter last year
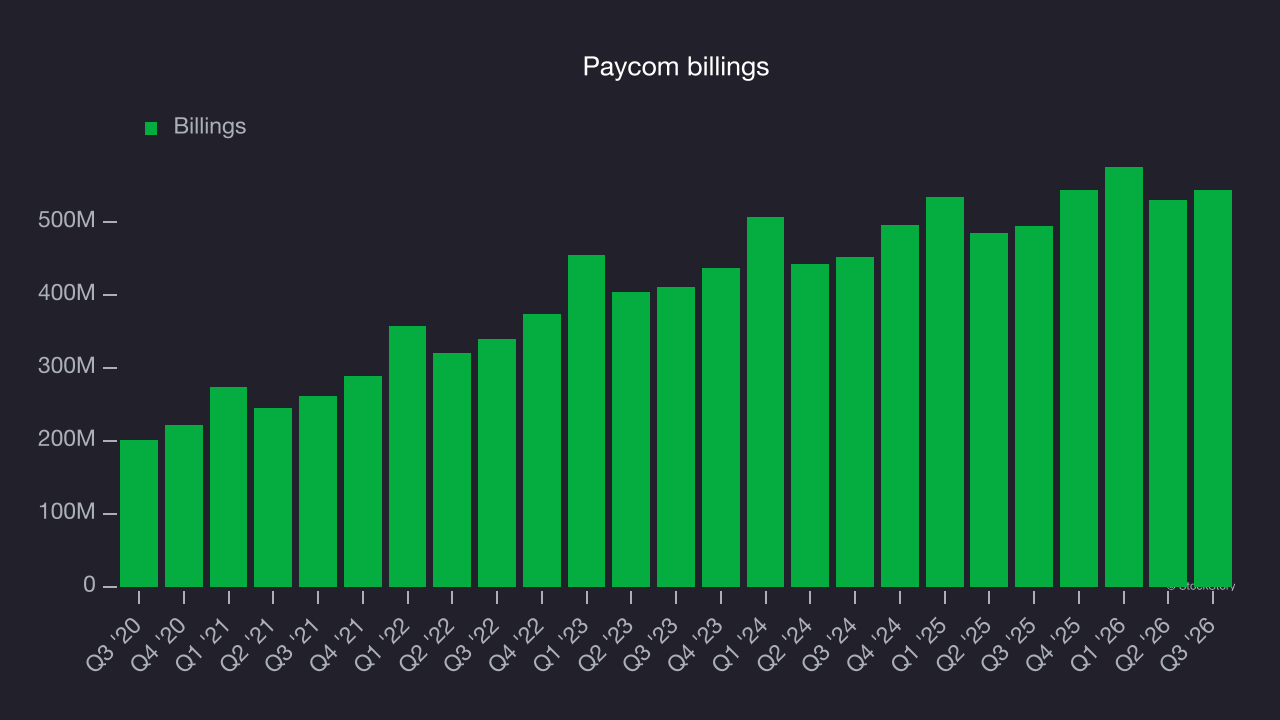
- Billings $544.7 million at quarter end, up 10.1% year on year
- Market capitalization $11.65 billion
“Our strong third-quarter results reflect the tremendous ROI clients are realizing from the automated decisioning logic built into our platform,” said Paycom founder and CEO Chad Richison. “Our software and infrastructure allow us to develop, release, host, distribute, and service technology that delivers greater value to our clients and Paycom. This represents a powerful advantage across our large and expanding TAM. Thanks to our strong performance, we are once again raising our full-year outlook.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Over the last five years, Paycom grew its revenue at a 17.2% compounded annual growth rate. Though this growth is acceptable on an absolute basis, revenue growth alone is not enough in the software sector, which can display significant earnings volatility. The bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, the five-year growth period starts around Covid, when revenue was depressed before rebounding.
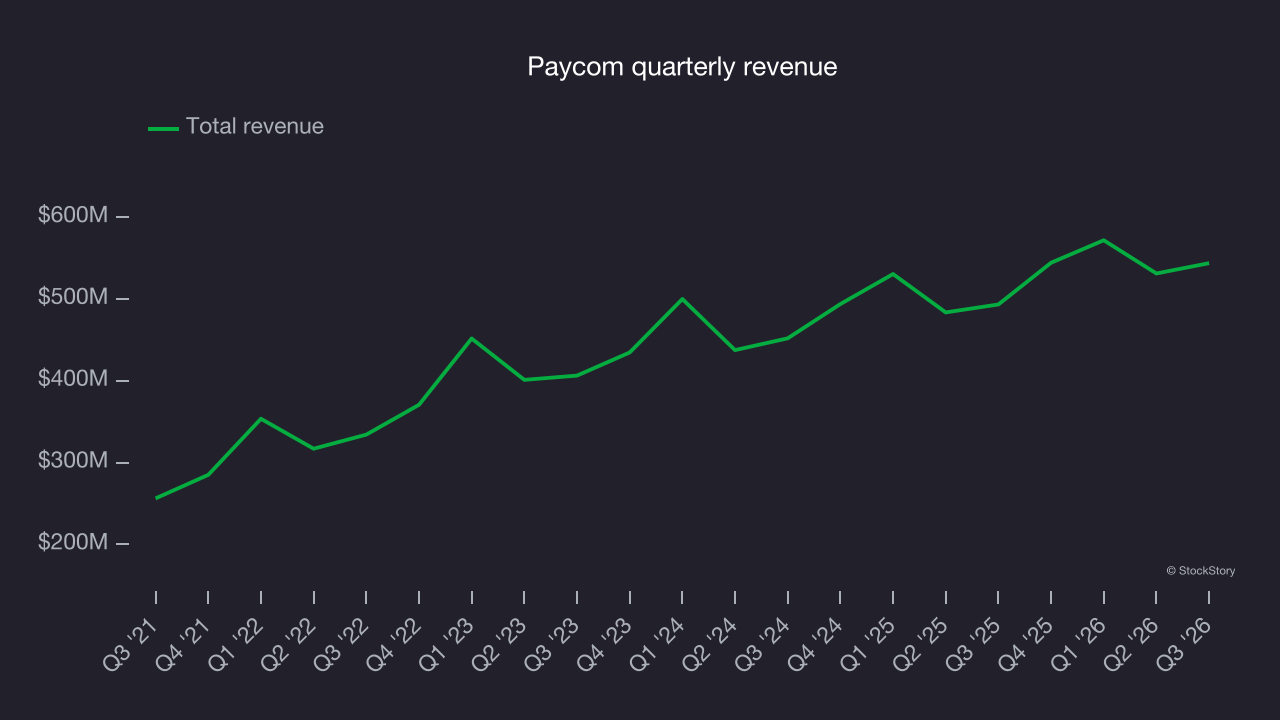
Long-term growth matters most, but within software, a half-decade historical view may miss recent innovations or disruptive industry trends. Paycom’s recent performance shows its demand has slowed as its annualized revenue growth of 9.6% over the last two years was below its five-year trend. Decelerating revenue growth in the sector is a concern, as it could signal changing consumer tastes aided by low switching costs.
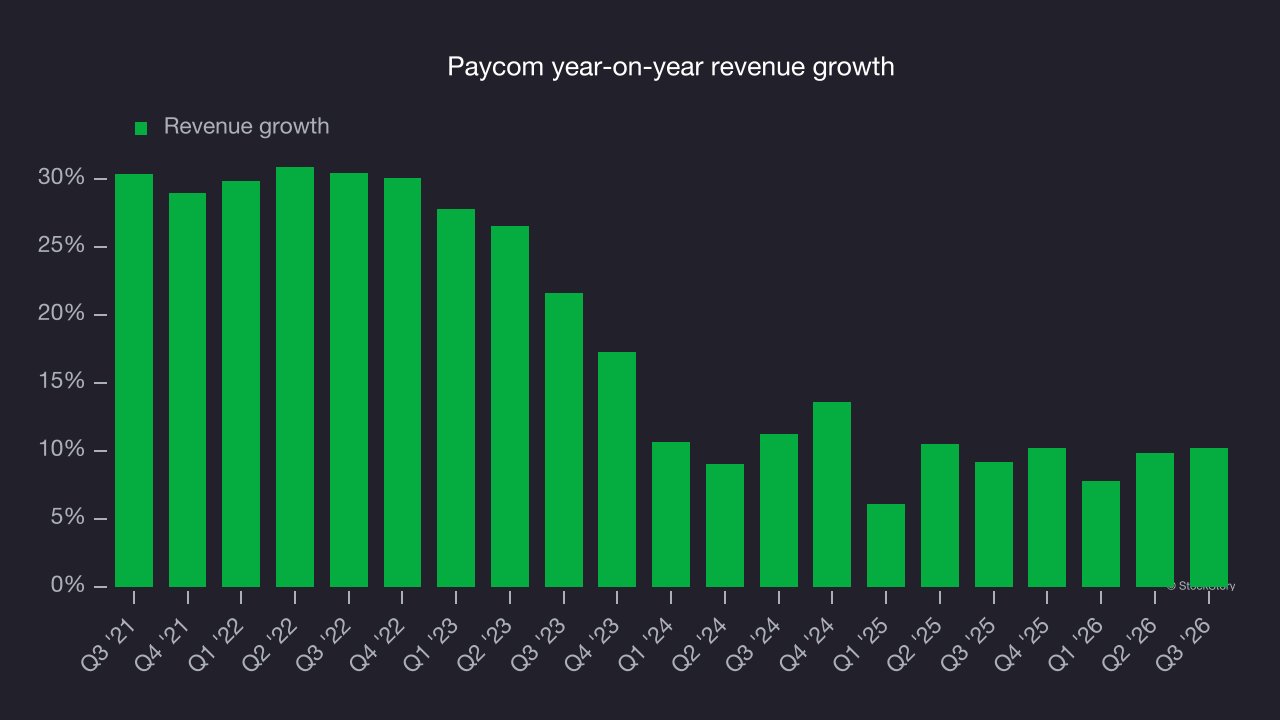
This quarter, Paycom reported year-on-year revenue growth of 10.2%, and its $543.8 million of revenue exceeded Wall Street’s consensus estimates by 1.5%.
Looking ahead, sell-side analysts expect revenue to grow 6.3% over the next 12 months, according to S&P, a deceleration versus the last two years. This uninspiring projection implies its products and services will see some demand headwinds.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Paycom’s billings came in at $544.7 million in Q3, and over the last four quarters, its growth was underwhelming, averaging 9.2% year on year. This performance mirrored its total revenue and suggests that increasing competition is making it harder to acquire and retain customers.
Customer acquisition efficiency
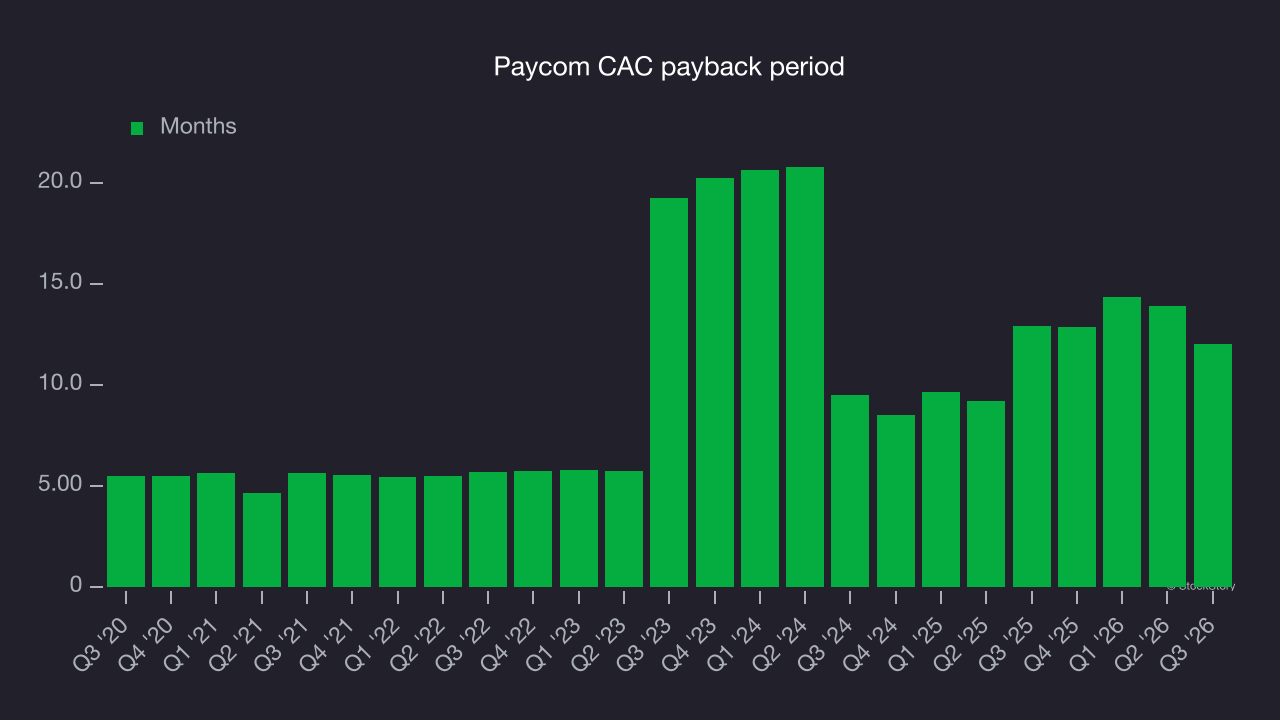
The customer acquisition cost, or CAC, payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
Paycom is highly efficient at acquiring new customers, and its CAC payback period was 12 months this quarter. The company’s rapid recovery of its customer acquisition costs means it can attempt to spur growth by increasing its sales and marketing investments.
Key takeaways from Paycom’s Q3 results
Paycom delivered a solid quarter, with full-year EBITDA guidance well above analysts’ consensus estimates and billings narrowly ahead of Wall Street’s consensus. Still, the market appeared to be hoping for more. Shares fell 4.8% to $254.90 immediately after the release.
The latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. Read our full research report here (it’s free).