

Student loan servicer Navient (NASDAQ:NAVI) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 87.6% year on year to $317 million. Its GAAP profit of $0.16 per share was 60% above analysts’ consensus estimates.
For more on Navient, read the full research report for free.
Navient (NAVI) Q3 2026 highlights:
- Net interest income $115 million vs analysts’ consensus estimates of $125 million (19% year-on-year decline, 8% miss)
- Pre-tax profit $13 million (4.1% margin)
- EPS (GAAP) $0.16 vs analysts’ consensus estimates of $0.10 (60% beat)
- Market capitalization $774.7 million
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Over the last five years, Navient’s demand was weak and its revenue declined by 17.8% per year. That performance fell short of our standards and points to poor business quality.
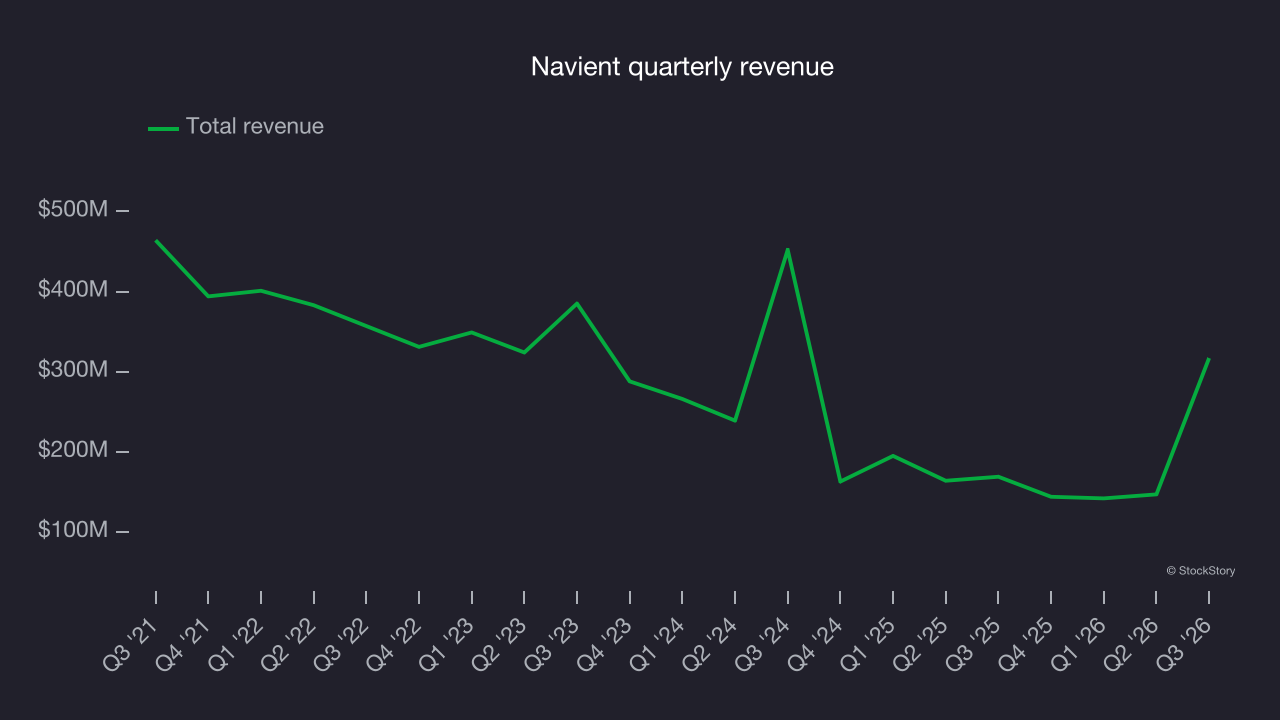
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Navient’s recent performance shows its demand remained suppressed as its revenue has declined by 22.4% annually over the last two years.
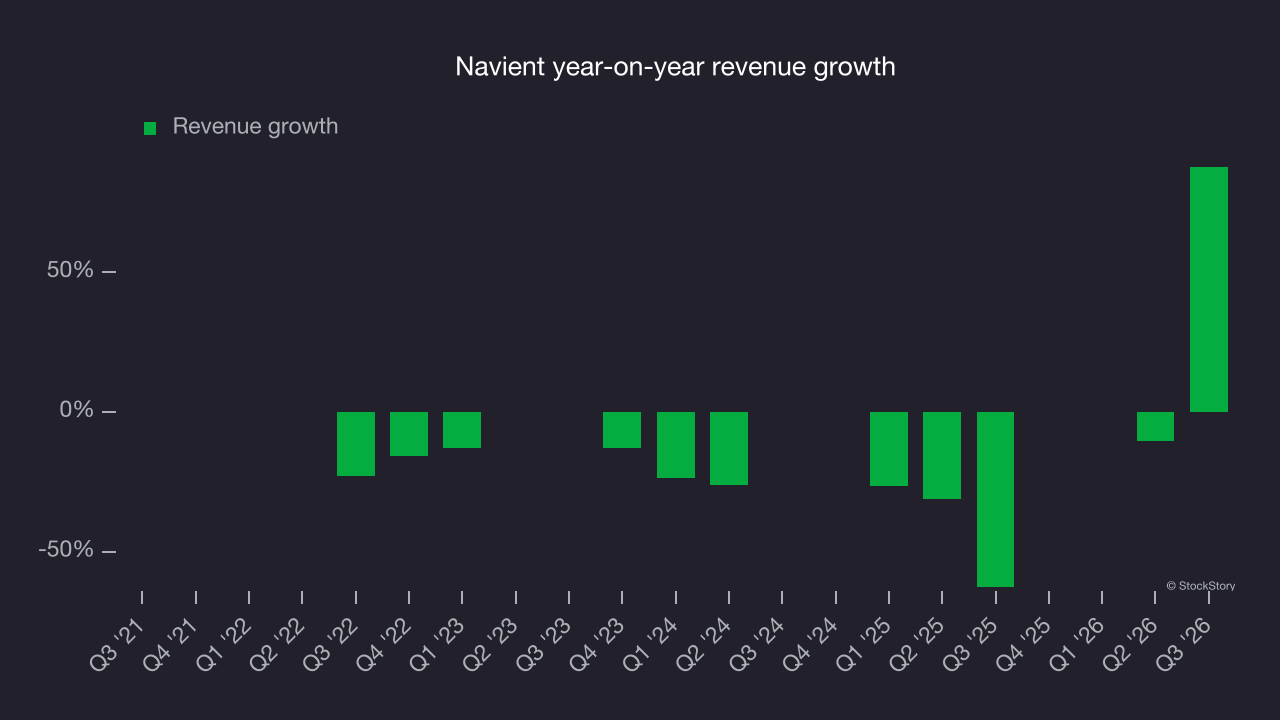
Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Navient reported year-on-year revenue growth of 87.6%, and its $317 million in revenue beat Wall Street’s consensus estimates by 122%.
Key takeaways from Navient’s Q3 results
Navient’s wide revenue beat and EPS above analysts’ consensus estimates were the highlights of a good Q3 report, but net interest income missed expectations. Shares remained flat at $9.09 immediately after the release.
The latest quarter matters, but longer-term fundamentals and valuation are more important when deciding if the stock is a buy. Read our full research report here (it’s free).