

Fast-food chain McDonald’s (NYSE:MCD) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose only 1.1% year on year to $7.16 billion. Its non-GAAP profit of $3.57 per share was 5.6% above analysts’ consensus estimates.
For more on McDonald's, read our full research report for free.
McDonald's (MCD) Q3 2026 highlights:
- Revenue $7.16 billion vs S&P analysts’ consensus estimates of $7.30 billion (1.1% year-on-year growth, 1.9% miss)
- Adjusted EPS $3.57 vs S&P analysts’ consensus estimates of $3.38 (5.6% beat)
- Operating margin 50.2%, up from 47.4% in the same quarter last year
- Same-store sales rose 1.5% year on year (3.6% in the same quarter last year)
- Market capitalization $186.1 billion
"McDonald's delivered another quarter of global growth, with solid performance across much of our international business. In the U.S., we're encouraged by improvement as the quarter progressed following our intervention on value," said Chris Kempczinski, Chairman and CEO. "We're focused on building from here, strengthening the business today and investing in the next chapter of growth."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul.
With $27.78 billion in revenue over the past 12 months, McDonald's is one of the most widely recognized restaurant chains and benefits from customer loyalty, an advantage many businesses lack. Its scale also gives it negotiating leverage with suppliers, enabling it to source its ingredients at a lower cost. However, its scale is a double-edged sword because there are only a finite number of places to build restaurants, making it harder to find incremental growth. For McDonald's to boost its revenue, it likely needs to adjust its prices, launch new chains or expand in foreign markets.
McDonald's grew its revenue at a sluggish 4.2% compounded annual growth rate over the last seven years, but to its credit, it opened new restaurants and increased revenue at existing, established dining locations.
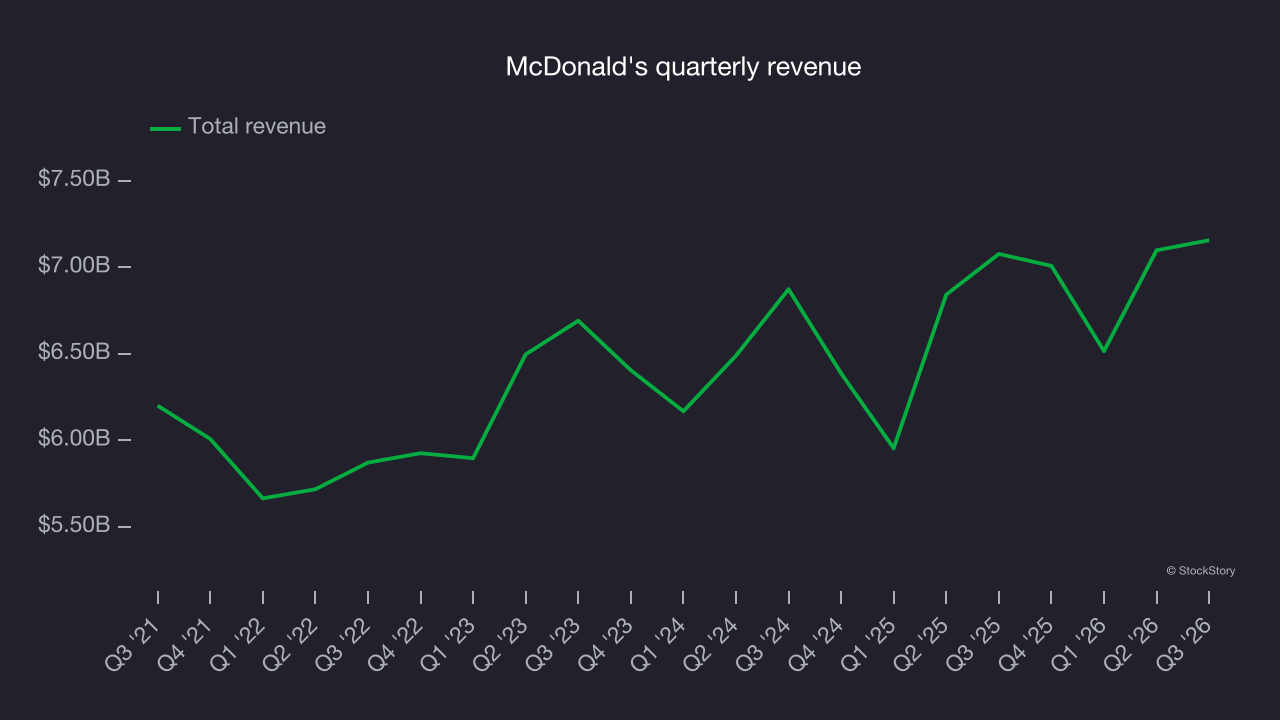
This quarter, McDonald’s revenue grew by 1.1% year on year to $7.16 billion, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 3.6% over the next 12 months, according to S&P, similar to its seven-year rate. This projection is underwhelming and implies its newer menu offerings will not accelerate its top-line performance yet. Still, the company is performing well on other measures of financial health.
Restaurant performance
Number of restaurants
A restaurant chain’s total number of dining locations influences how much it can sell and how quickly revenue can grow.
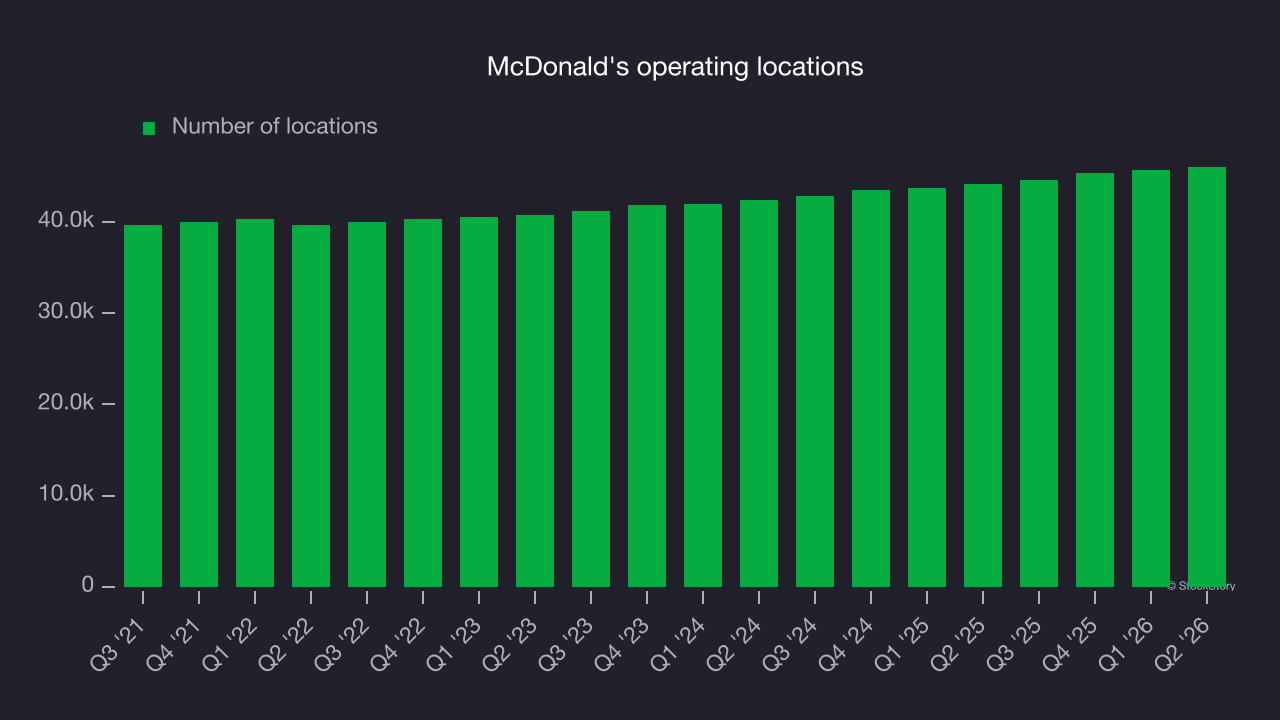
McDonald's opened new restaurants at a rapid pace over the last two years, averaging 4.2% annual growth, much faster than the broader restaurant sector. The company’s franchise model also makes expansion easier, with franchisees primarily responsible for opening new restaurants while McDonald's provides support.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
Note that McDonald's reports its restaurant count intermittently, so some data points are missing in the chart below.
Same-store sales
The change in a company’s restaurant base only tells one side of the story. The other is the performance of its existing locations, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales offer insight into this topic by measuring organic growth at restaurants open for at least a year.
McDonald’s demand rose over the last two years and slightly outpaced the industry. On average, the company’s same-store sales have grown by 2.4% per year. This performance suggests its rollout of new restaurants could be beneficial for shareholders. When a chain has demand, more locations should help it reach more customers and boost revenue growth.
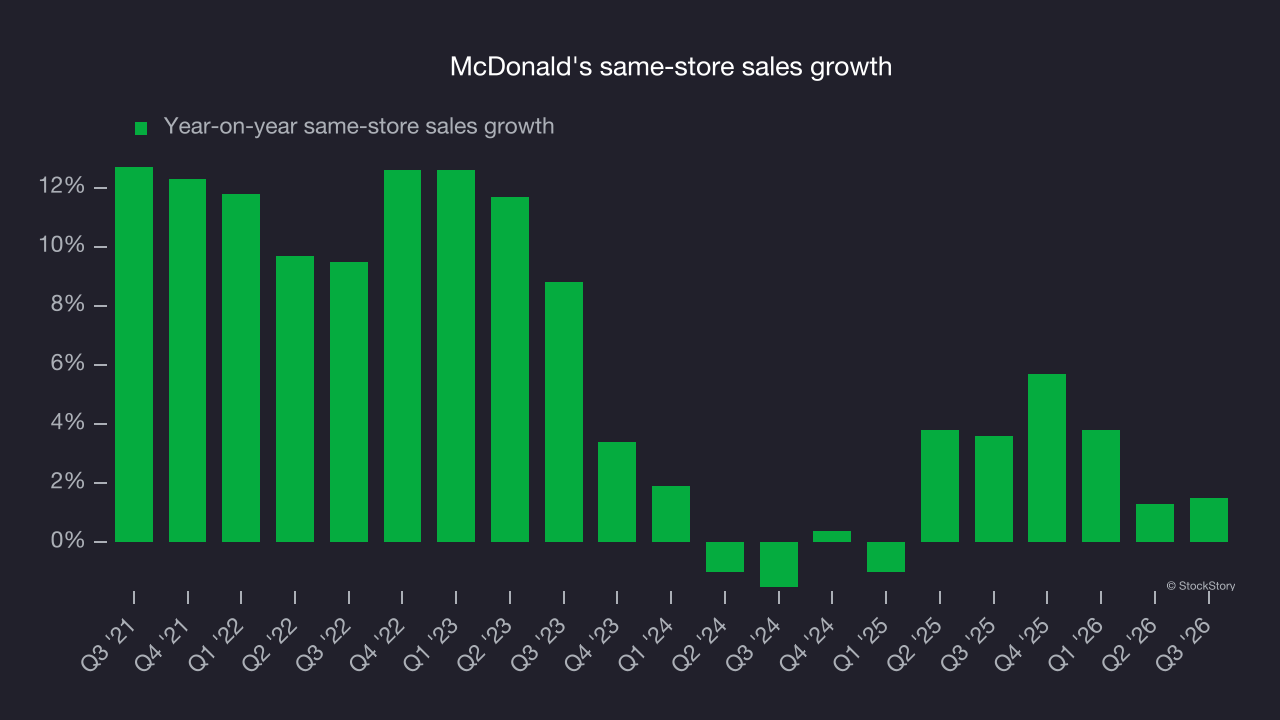
In the latest quarter, McDonald’s same-store sales rose 1.5% year on year. This performance was more or less in line with its historical levels.
Key takeaways from McDonald’s Q3 results
McDonald’s met analysts’ consensus estimates for same-store sales and beat Wall Street’s consensus estimates for EPS, but a revenue miss made for a softer quarter overall. Shares rose 2.2% to $268.71 immediately after the release.
How should investors evaluate McDonald's? That decision calls for considering its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).