

Maximus currently trades at $64.95 per share and has shown little upside over the past six months, posting a middling return of 0.6%.
Is there a buying opportunity in Maximus, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Maximus not exciting?
We don’t have much confidence in Maximus. Here are three reasons why MMS doesn’t excite us, plus one stock we’d rather own.
1. Revenue growth flatlining
We at StockStory place the most emphasis on long-term growth, but within business services, a stretched historical view may miss recent innovations or disruptive industry trends. Maximus’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 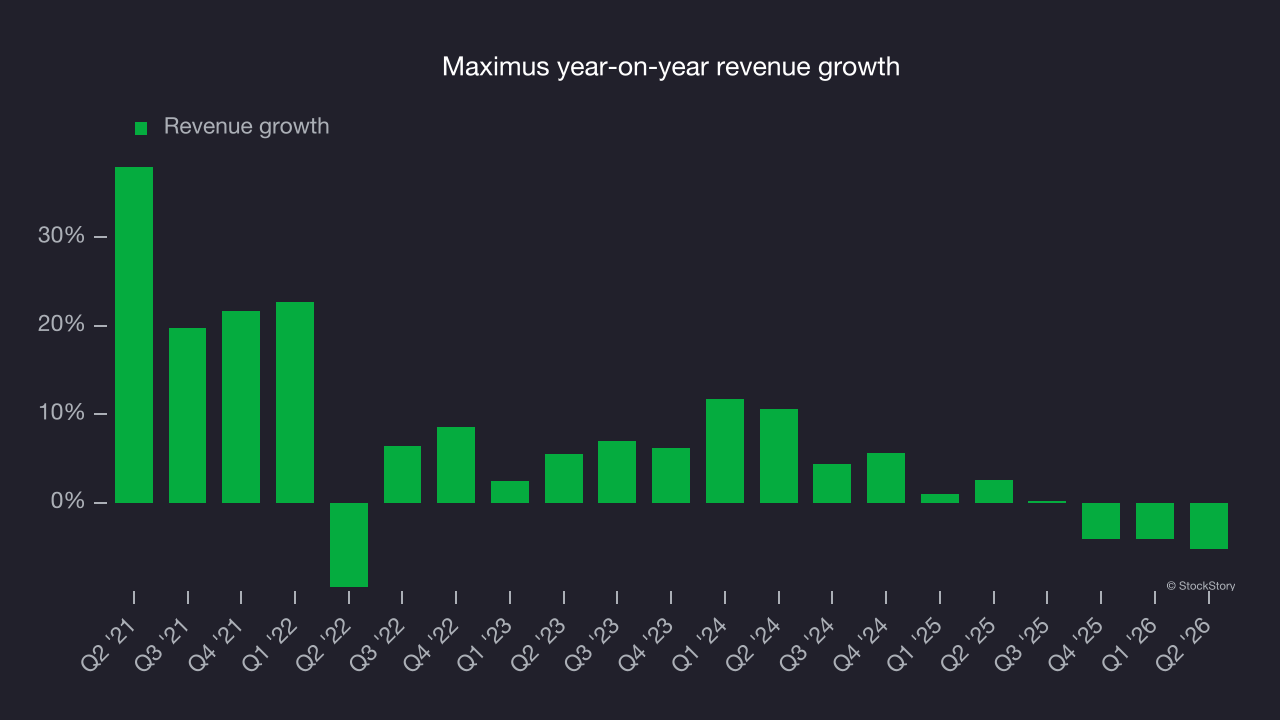
2. Projected revenue growth is slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Maximus’s revenue to rise by 3.5%, according to S&P. Although this projection implies its newer products and services will spur better top-line performance, it is still below average for the sector.
3. Mediocre free cash flow margin limits reinvestment potential
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
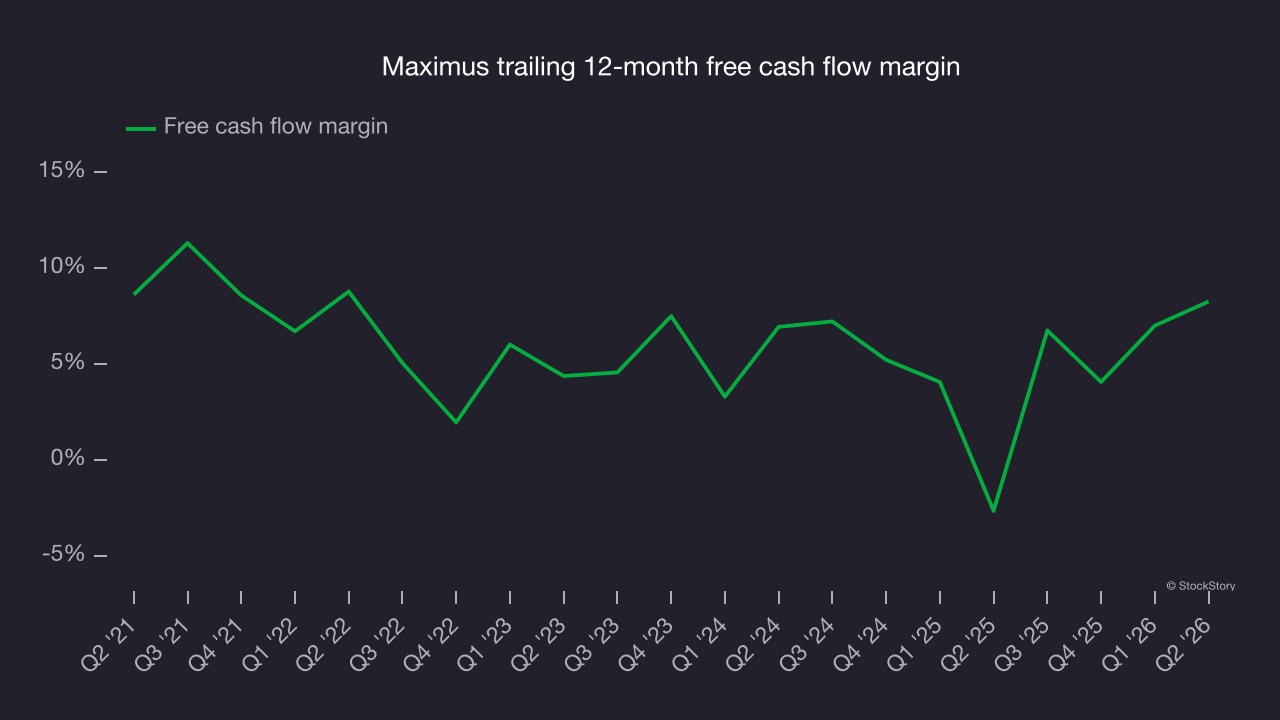
Maximus has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 5%, below what we’d expect for a business services business.
Final judgment
Maximus isn’t a terrible business, but it doesn’t pass our bar. That said, the stock currently trades at 8× forward P/E (or $64.95 per share). While this valuation is optically cheap, the potential downside is big given its shaky fundamentals. We’re fairly confident there are better investments elsewhere. We’d suggest looking at one of our all-time favorite software stocks.
Stocks we would buy instead of Maximus
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.