

Aerospace and defense company Kratos (NASDAQ:KTOS) will be announcing earnings results this Thursday after market hours. Here’s what to look for.
Kratos beat analysts’ revenue expectations last quarter, reporting revenues of $458.8 million, up 30.5% year on year. It was a very strong quarter for the company, with a solid beat of analysts’ organic revenue estimates and a beat of analysts’ EPS estimates.
Is Kratos a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Kratos’s revenue to grow 36.3% year on year, improving from the 26% increase it recorded in the same quarter last year.
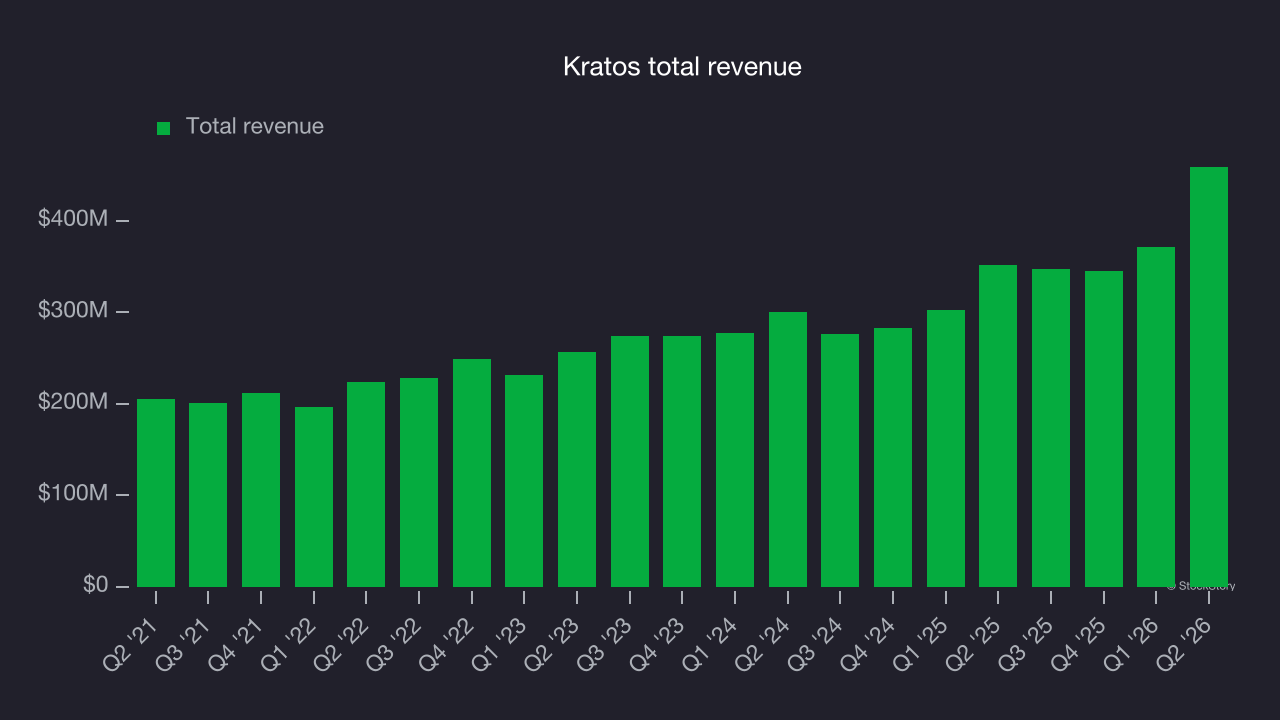
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Kratos has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Kratos’s peers in the defense contractors segment, some have already reported their Q3 results, giving us a hint as to what we can expect. Huntington Ingalls delivered year-on-year revenue growth of 10.8%, beating analysts’ expectations by 5.3%, and RTX reported revenues up 11.1%, topping estimates by 3.3%. Huntington Ingalls traded up 13.5% following the results while RTX’s stock price was unchanged.
Read our full analysis of Huntington Ingalls’s results here and RTX’s results here.
Investors in the defense contractors segment have had steady hands going into earnings, with share prices flat over the last month. Kratos is down 2.4% during the same time and is heading into earnings with an average analyst price target of $89.76 (compared to the current share price of $41.03).
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.