

Credit scoring and analytics company FICO (NYSE:FICO) announced better-than-expected revenue in calendar Q3 2026 (fiscal Q4 2026), with revenue up 27.4% year on year to $657 million. Its non-GAAP profit of $11.10 per share was 3.6% above analysts’ consensus estimates.
For more on Fair Isaac Corporation, read our free full research report.
Fair Isaac Corporation (FICO) Q3 CY2026 highlights:
- Revenue $657 million vs S&P analysts’ consensus estimates of $650.2 million (27.4% year-on-year growth, 1.1% beat)
- Adjusted EPS $11.10 vs S&P analysts’ consensus estimates of $10.71 (3.6% beat)
- Operating margin 40.6%, down from 46% in the same quarter last year
- Free cash flow margin 43.3%, up from 40.9% in the same quarter last year
- Market capitalization $15.64 billion
“I am proud of our performance in FY26,” said Will Lansing, chief executive officer. “Our team continues to execute well despite a turbulent macro environment.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term.
With $2.53 billion in revenue over the past 12 months, Fair Isaac Corporation is a mid-sized business services company, which sometimes brings disadvantages compared to larger competitors benefiting from better economies of scale. On the positive side, it can still achieve high growth rates because it’s working from a smaller revenue base.
Fair Isaac Corporation’s 14% annualized revenue growth over the last five years was strong. This shows demand for its offerings was higher than that of many business services companies.
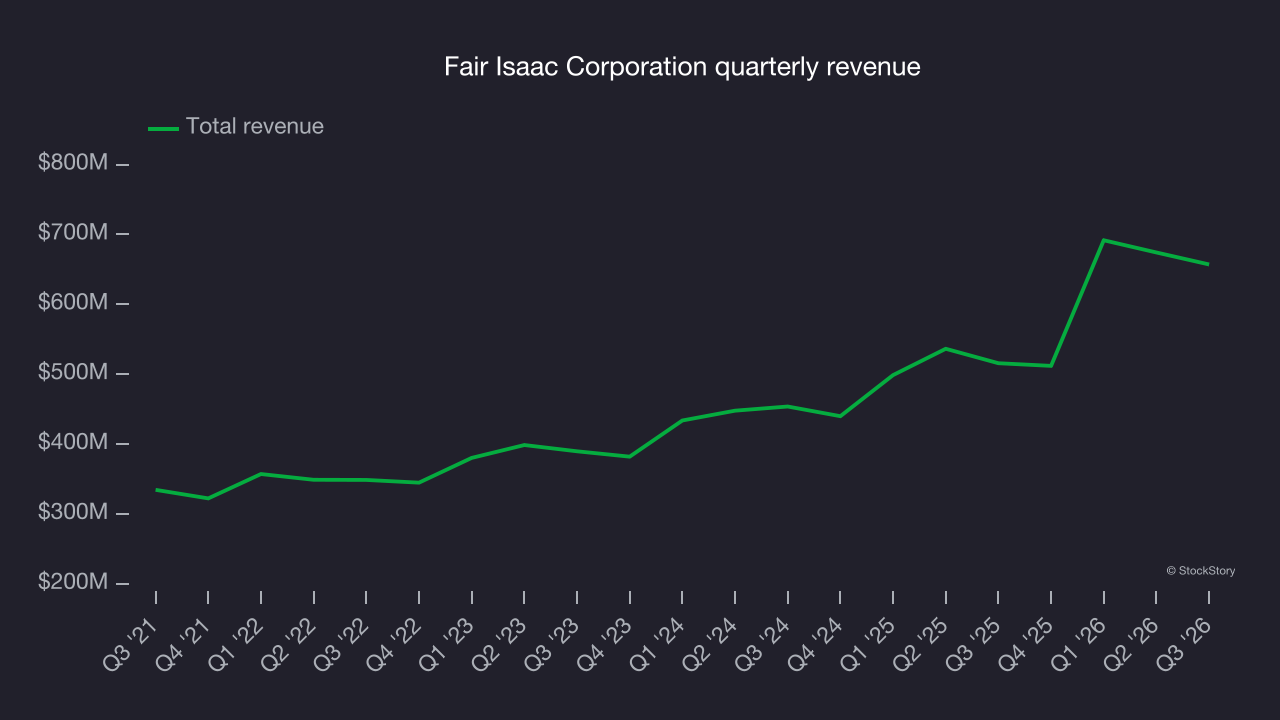
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Fair Isaac Corporation’s annualized revenue growth of 21.5% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 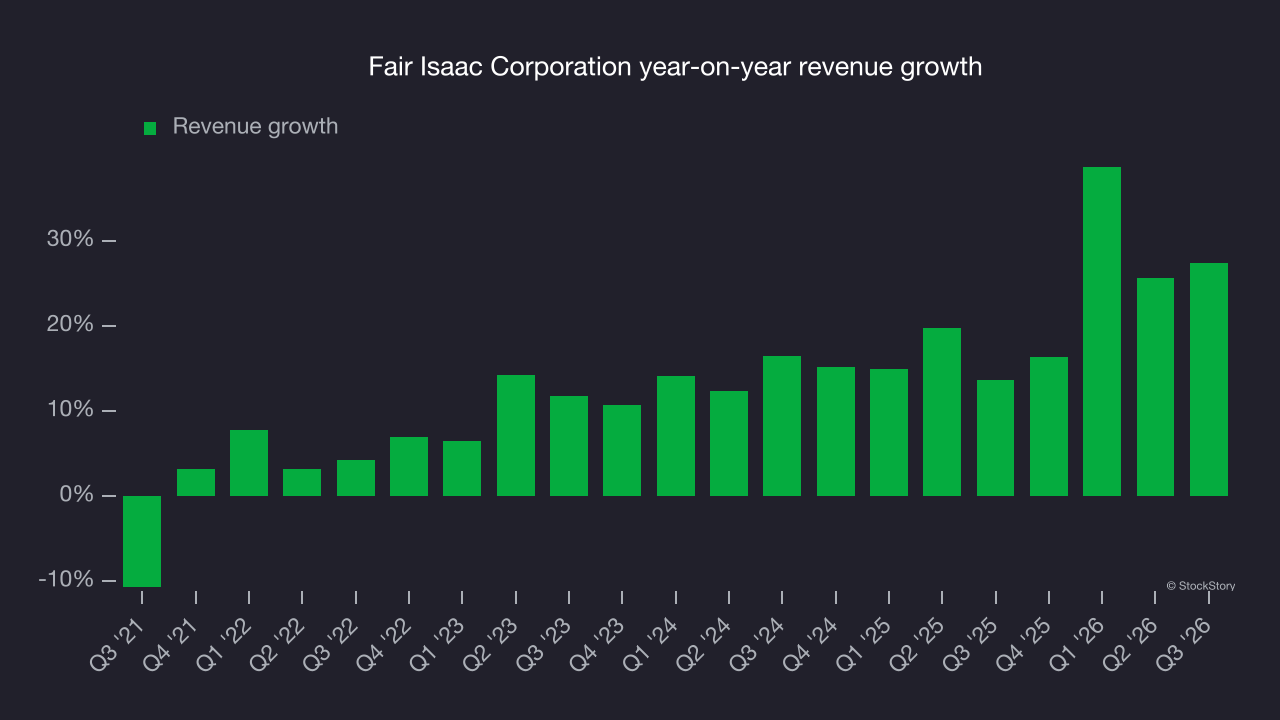
This quarter, Fair Isaac Corporation reported strong year-on-year revenue growth of 27.4%, and its $657 million in revenue topped Wall Street’s consensus estimates by 1.1%.
Looking ahead, sell-side analysts expect revenue to grow 4.6% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges. Still, the company is tracking well in other measures of financial health.
Adjusted operating margin
Fair Isaac Corporation has operated efficiently over the last five years. It demonstrated high profitability for a business services company, with an average adjusted operating margin of 53.1%.
Fair Isaac Corporation’s adjusted operating margin rose by 9.3 percentage points over the last five years, as its revenue growth provided substantial operating leverage.
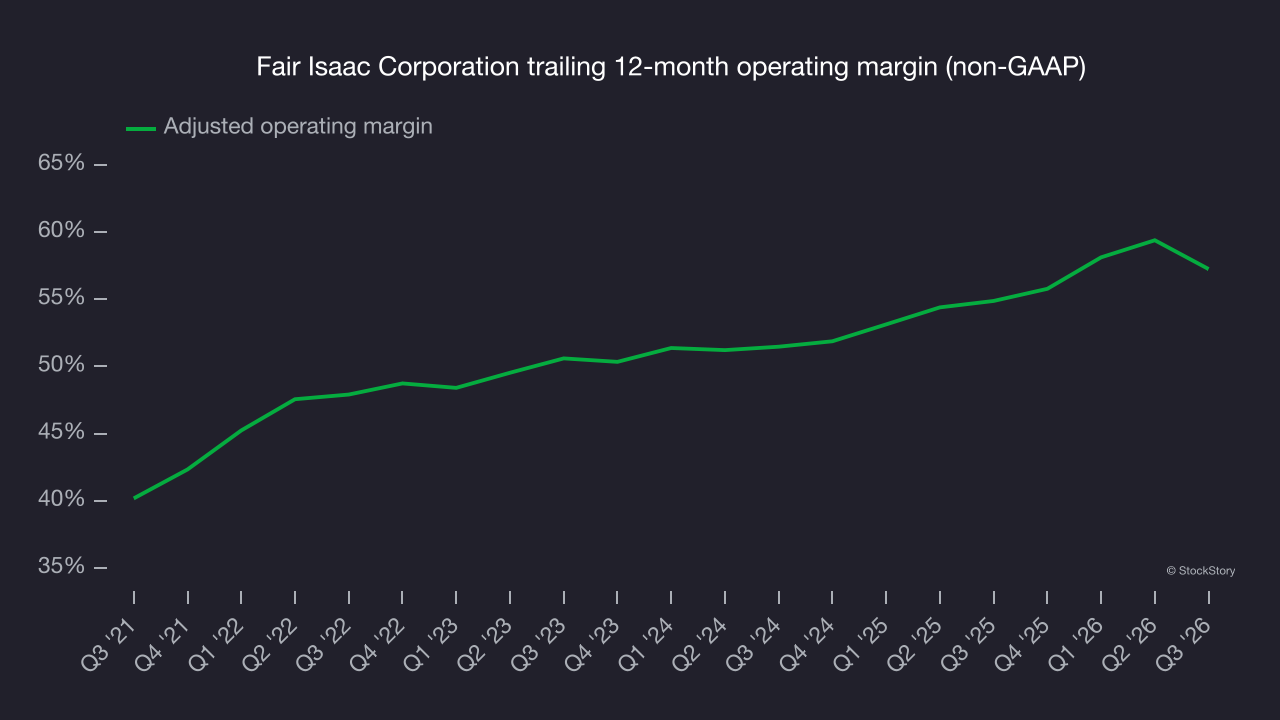
This quarter, Fair Isaac Corporation generated an adjusted operating margin of 47.2%, down 7.2 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Fair Isaac Corporation’s EPS grew at a 26.9% compounded annual growth rate over the last five years, higher than its 14% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
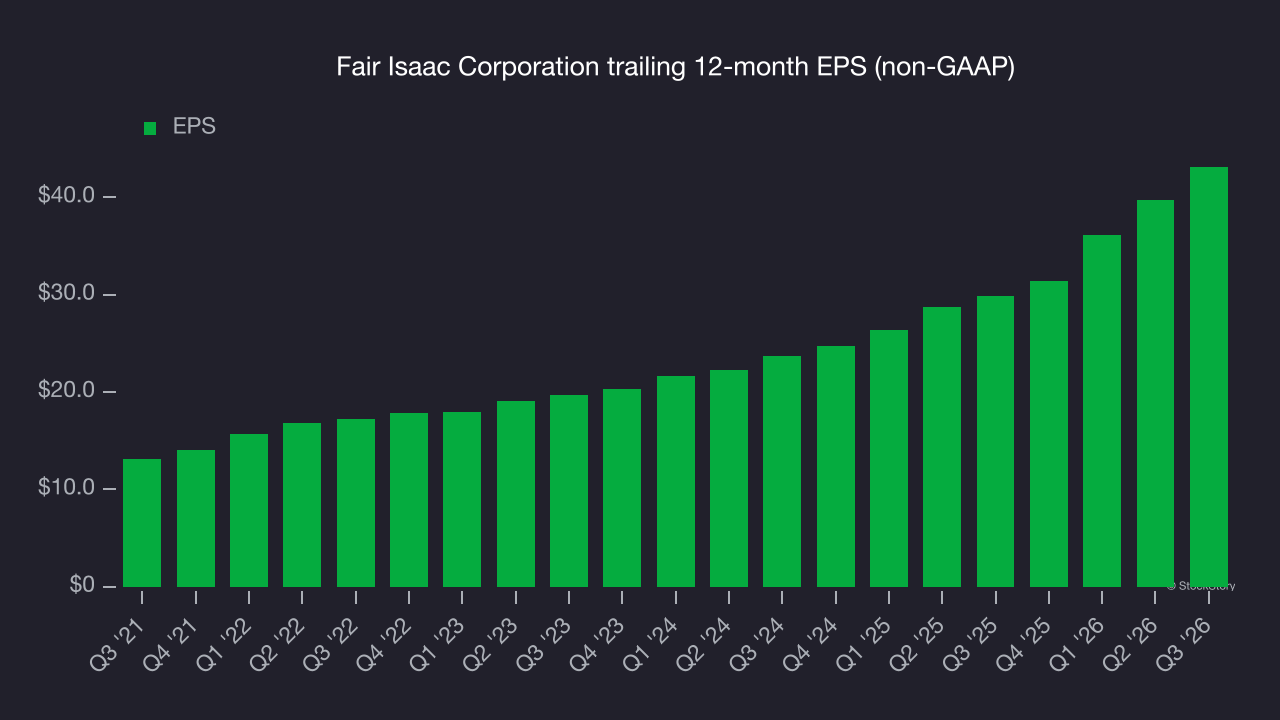
A closer look at Fair Isaac Corporation’s earnings quality helps explain the drivers of its performance. Fair Isaac Corporation’s adjusted operating margin declined this quarter but expanded by 9.3 percentage points over the last five years. Its share count also shrank by 24.4%, and these factors together are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth. 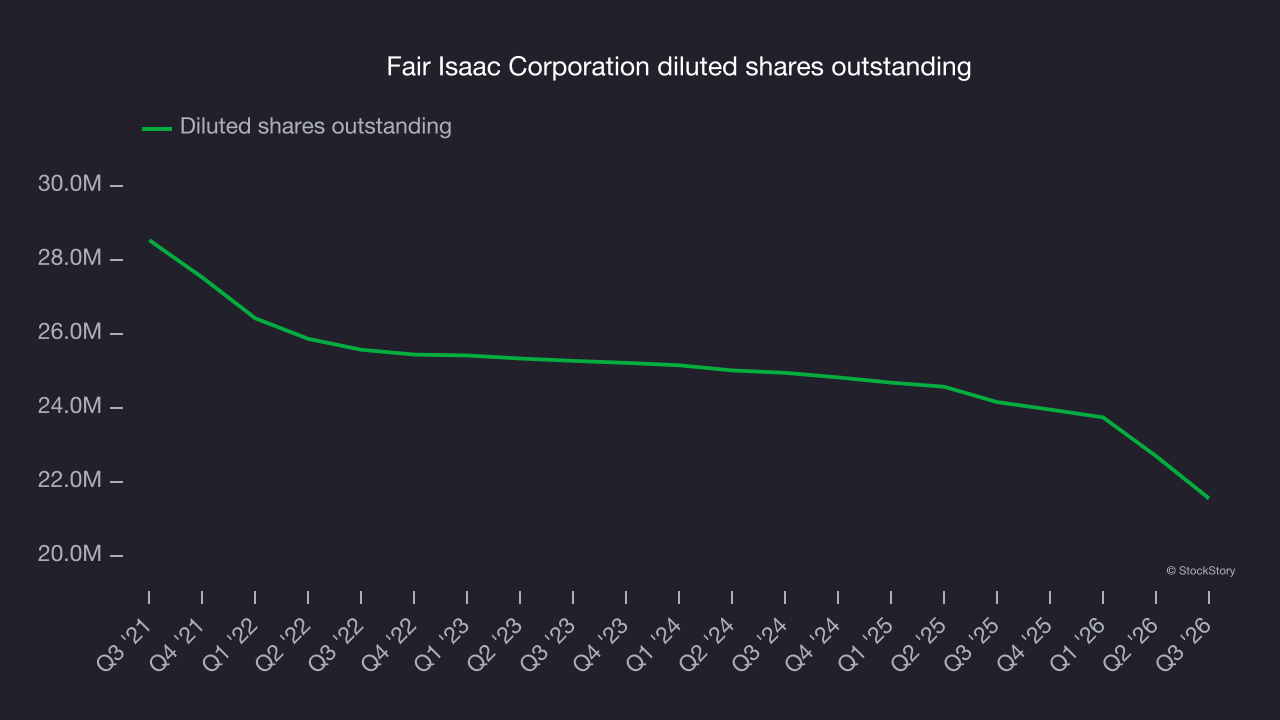
As with revenue, analyzing EPS over a more recent period can provide insight into an emerging theme or development for the business.
For Fair Isaac Corporation, its two-year annual EPS growth of 34.8% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, Fair Isaac Corporation reported adjusted EPS of $11.10, up from $7.74 in the same quarter last year. This result beat analysts’ consensus estimates by 3.6%. Over the next 12 months, Wall Street expects Fair Isaac Corporation’s full-year EPS to grow 6.7% from $43.11 to $46.01, according to S&P.
Key takeaways from Fair Isaac Corporation’s Q3 results
Fair Isaac Corporation’s EPS beat and narrow revenue beat against Wall Street’s consensus estimates gave the quarter some key positives. Even so, investors were likely hoping for more: Shares tumbled 9% to $643.91 immediately after the results.
Fair Isaac Corporation’s latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in the stock. For more, read the full research report here (it’s free).