

Dental products company Envista Holdings (NYSE:NVST) met Wall Street’s revenue expectations in Q3 2026, with revenue up 3.2% year on year to $691.5 million. Its non-GAAP profit of $0.40 per share was 12.4% above analysts’ consensus estimates.
For more on Envista, read our free full research report.
Envista (NVST) Q3 2026 highlights:
- Revenue $691.5 million vs S&P analysts’ consensus estimates of $688.2 million (3.2% year-on-year growth, in line)
- Adjusted EPS $0.40 vs S&P analysts’ consensus estimates of $0.36 (12.4% beat)
- Adjusted EBITDA $106 million vs analysts’ consensus estimates of $97.38 million (15.3% margin, 8.9% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.56 at the midpoint, a 2.3% increase
- Operating margin 74.5%, up from 8.6% in the same quarter last year
- Free cash flow -$16.1 million, down from $67.9 million in the same quarter last year
- Market capitalization $3.98 billion
"Envista delivered another quarter of profitable growth, gaining share and expanding margins," said Paul Keel, CEO. "Supported by the Envista Business System, we are converting broad-based topline performance into even stronger earnings growth, while continuing to invest in our customers, colleagues and communities to sustain long-term success. Our strong momentum and year-to-date progress give us confidence to raise our full-year earnings guidance once again."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years. Over the last five years, Envista grew its revenue at a tepid 3.1% compounded annual growth rate, falling short of the healthcare sector benchmark.
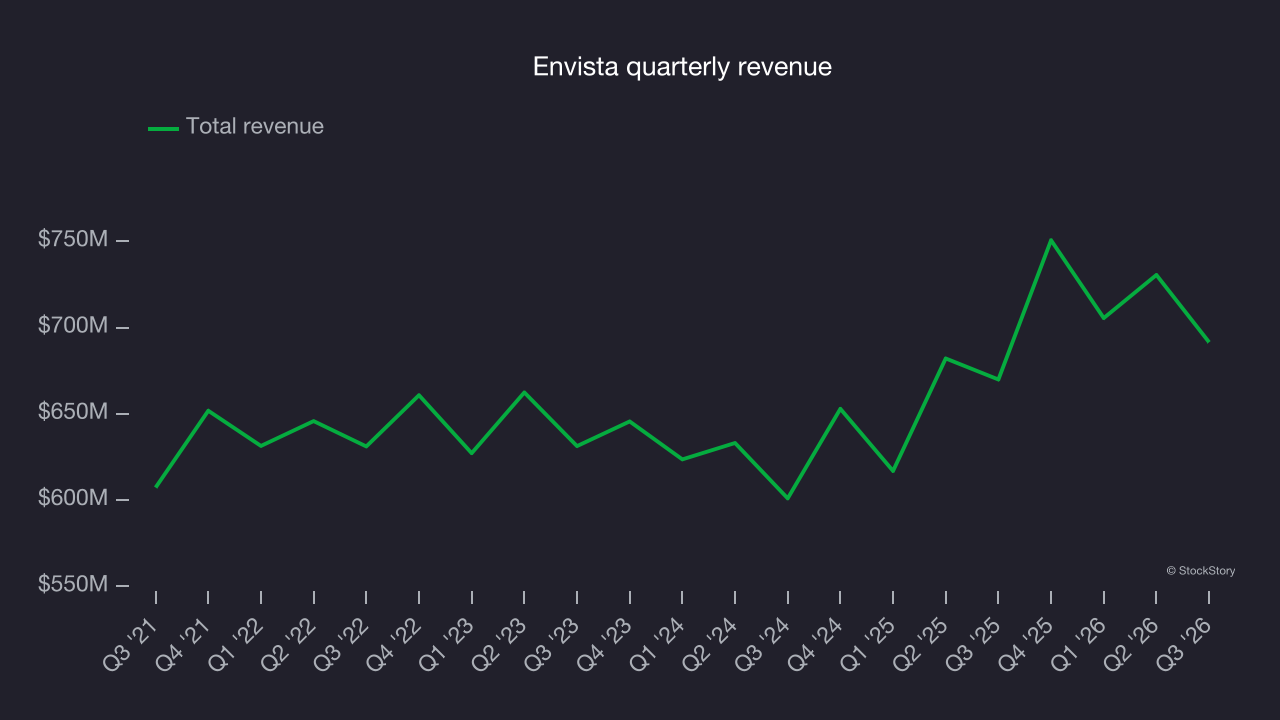
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. Envista’s annualized revenue growth of 7.2% over the last two years is above its five-year trend, a positive sign. 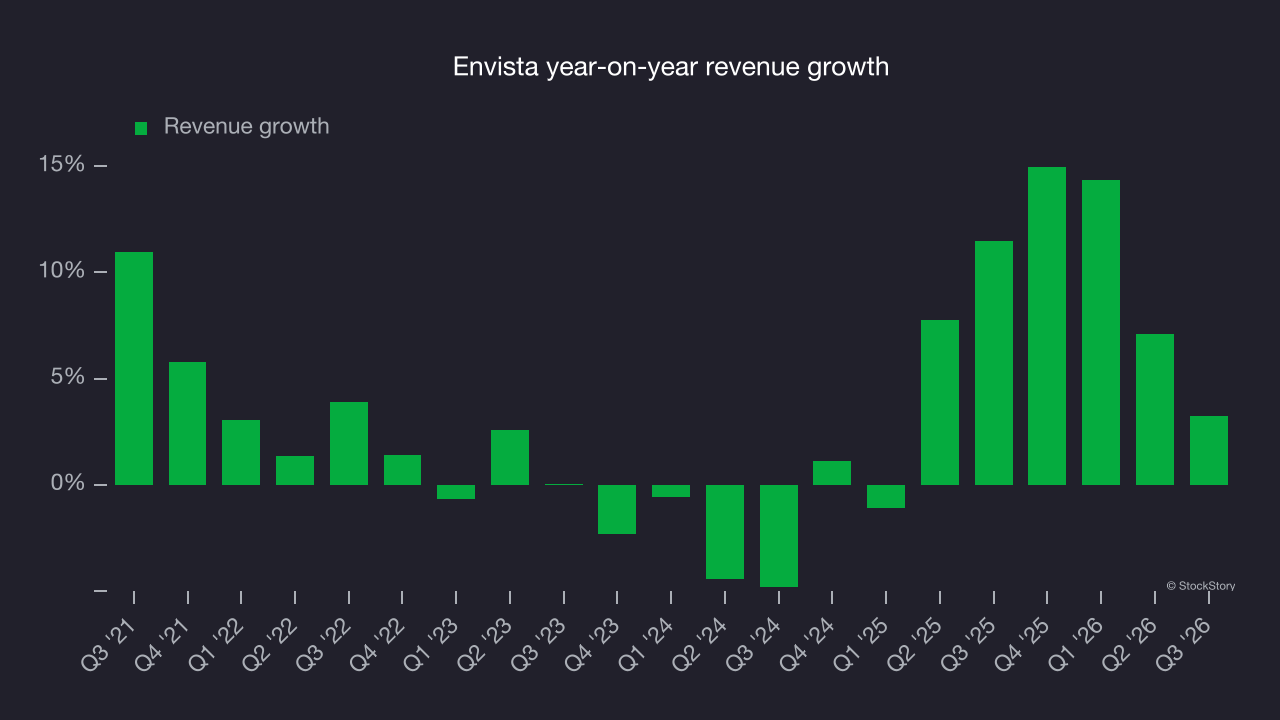
This quarter, Envista grew its revenue by 3.2% year on year, and its $691.5 million in revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 2% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will see some demand headwinds.
Adjusted operating margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt and taxes.
Envista has managed its cost base well over the last five years. It demonstrated solid profitability for a healthcare business, producing an average adjusted operating margin of 17.5%.
Looking at the trend in its profitability, Envista’s adjusted operating margin rose by 9.6 percentage points over the last five years, as its revenue growth gave it operating leverage. This performance was mostly driven by its recent improvements as the company’s margin has increased by 17.3 percentage points on a two-year basis.
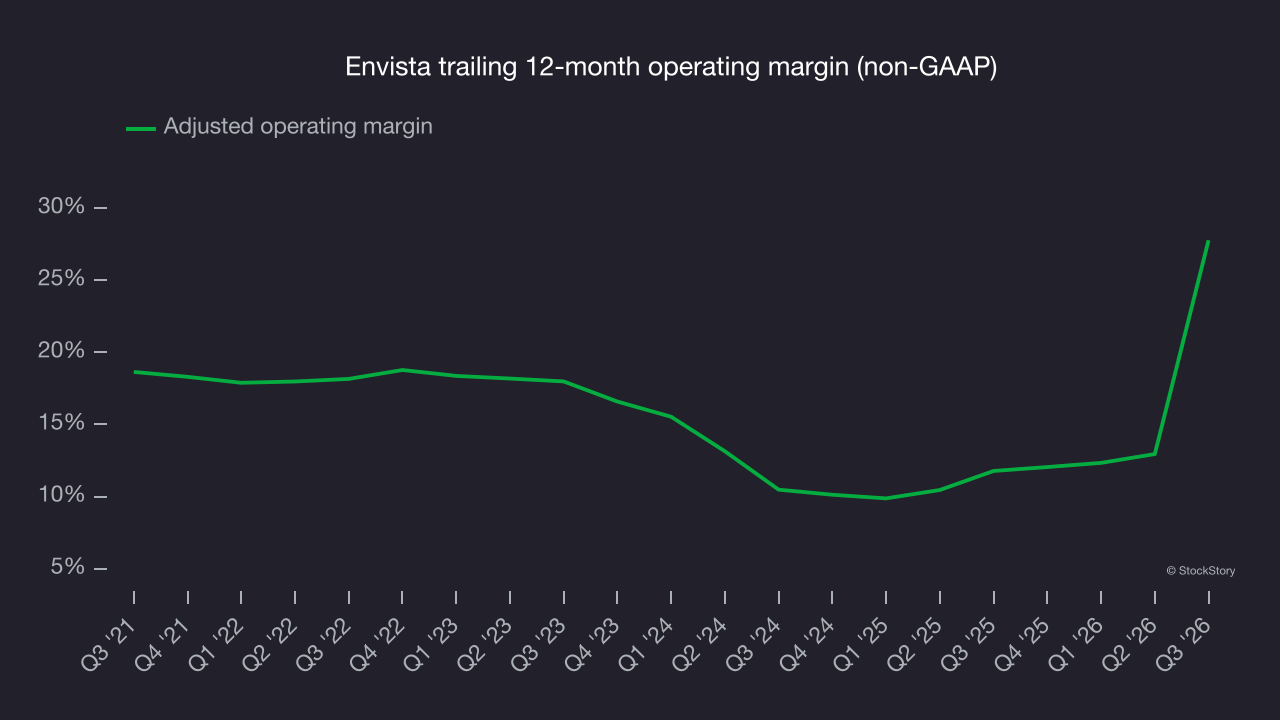
In Q3, Envista generated an adjusted operating margin of 74.5%, up 61.7 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Envista’s EPS declined by 5.7% annually over the last five years while its revenue grew by 3.1%. The difference stemmed from higher interest expenses or taxes, as the company improved its adjusted operating margin and repurchased its shares during this time.
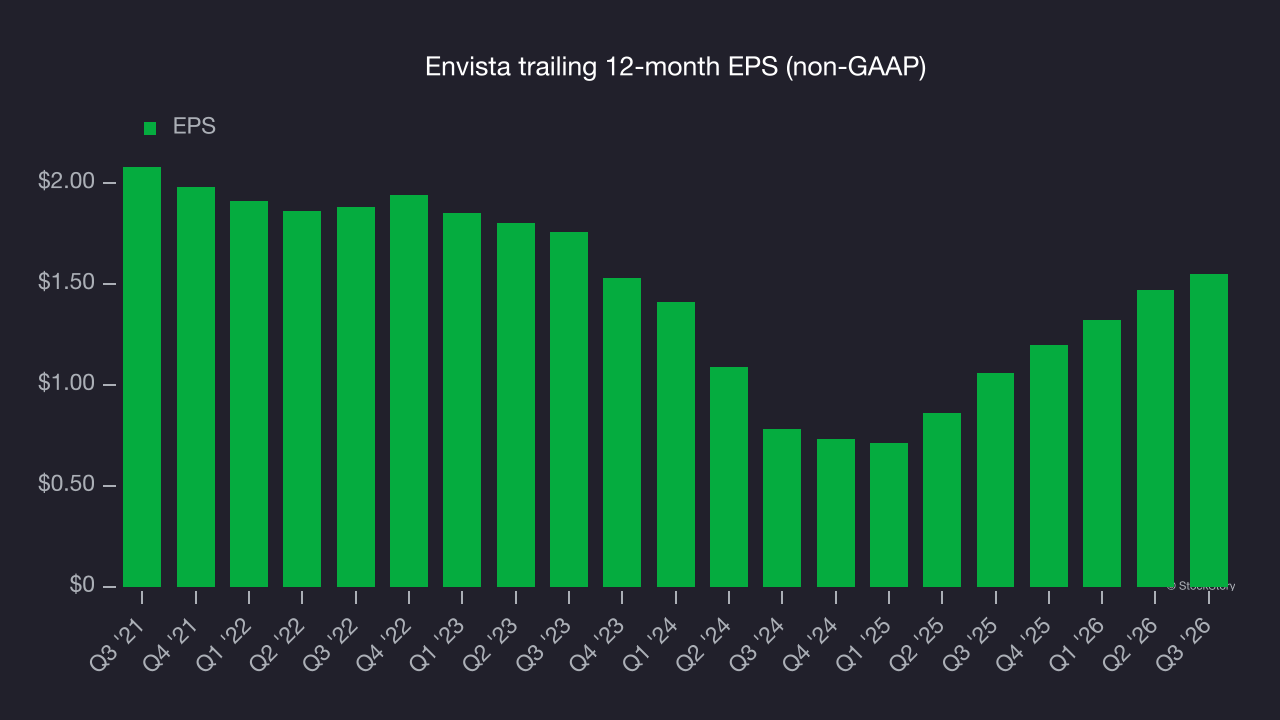
In Q3, Envista reported adjusted EPS of $0.40, up from $0.32 in the same quarter last year. That was well above analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Envista’s full-year EPS to grow 3.1% from $1.55 to $1.60, according to S&P.
Key takeaways from Envista’s Q3 results
Envista delivered a solid Q3, with EPS above analysts’ consensus estimates and full-year EPS guidance also ahead of Wall Street’s consensus. Those were key positives for the quarter. Shares remained flat at $27.27 immediately after the results.
Envista had a solid quarterly earnings result, but is the stock a good investment at its current valuation? The latest quarter is only one piece of the longer-term business quality puzzle. Quality, combined with valuation, can help determine whether the stock is a buy. For more on Envista, read our full research report here (it’s free).