

Cosmetics company e.l.f. Beauty (NYSE:ELF) beat Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), with revenue up 51.4% year on year to $520.8 million. The company’s full-year revenue guidance of $2.02 billion at the midpoint came in 1.8% above analysts’ consensus estimates. Its non-GAAP profit of $1.21 per share was significantly above analysts’ consensus estimates.
For more on e.l.f. Beauty, read our free full research report.
e.l.f. Beauty (ELF) Q3 CY2026 highlights:
- Revenue $520.8 million vs S&P analysts’ consensus estimates of $475.3 million (51.4% year-on-year growth, 9.6% beat)
- Adjusted EPS $1.21 vs S&P analysts’ consensus estimates of $0.60 (significant beat)
- Adjusted EBITDA $123.4 million vs analysts’ consensus estimates of $76.8 million (23.7% margin, 60.6% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $2.02 billion at the midpoint from $1.95 billion, a 3.2% increase
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $3.84 at the midpoint, an 8.9% increase
- EBITDA guidance $424 million at the midpoint for the full year, above analysts’ consensus estimates of $408.6 million
- Operating margin 10.1%, up from 2.2% in the same quarter last year
- Free cash flow margin 2.3%, down from 4.8% in the same quarter last year
- Market capitalization $6.58 billion
“I am proud of the e.l.f. Beauty team for delivering our 31st consecutive quarter of net sales growth, with net sales up 51% driven by strength across our portfolio. With this momentum, we are raising our full-year net sales guidance to 22 to 24 percent,” said e.l.f. Beauty Chairman and CEO Tarang Amin. “The consistency of our results is powered by our passionate team of owners, deep engagement with our community, and democratizing access to the best of beauty.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years.
With $1.94 billion in revenue over the past 12 months, e.l.f. Beauty is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the positive side, it can grow faster because it has a longer list of untapped store chains to sell into.
e.l.f. Beauty grew its revenue at a strong 36.3% compounded annual growth rate over the last three years. This shows demand for its products was higher than for those of many consumer staples companies.
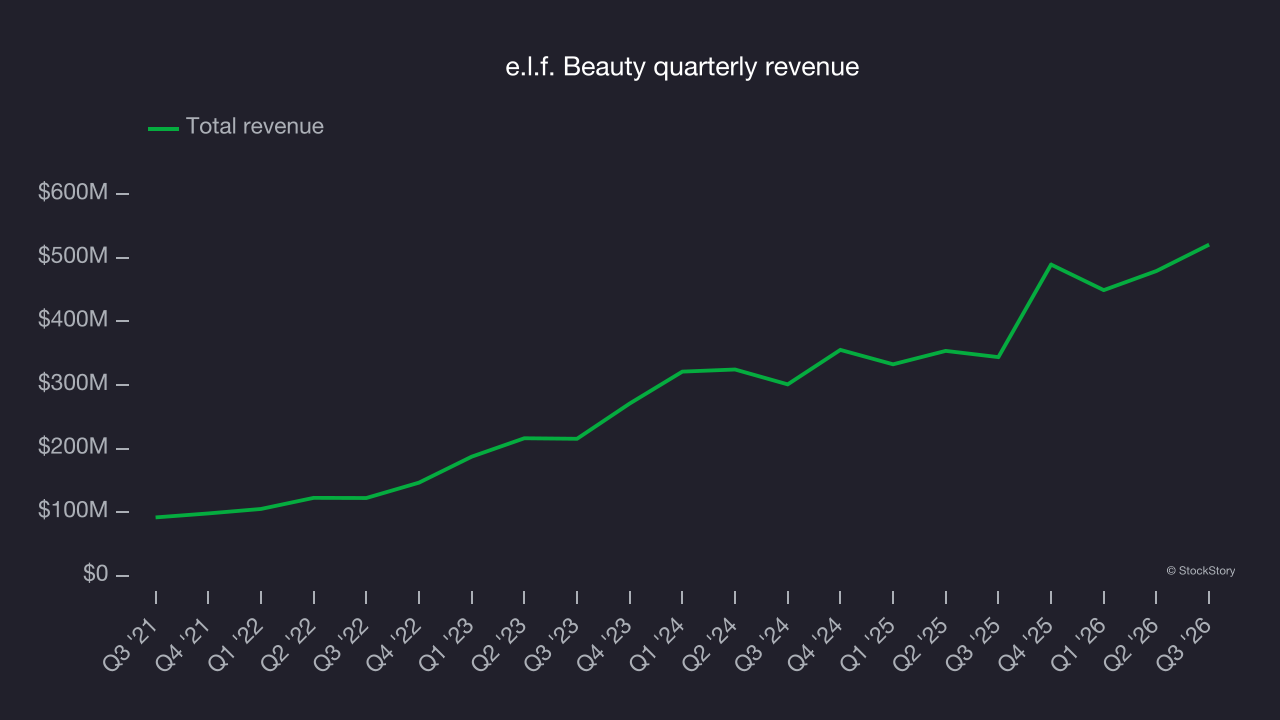
This quarter, e.l.f. Beauty reported year-on-year revenue growth of 51.4%, and its $520.8 million in revenue beat Wall Street’s consensus estimates by 9.6%.
Looking ahead, sell-side analysts expect revenue to grow 7.1% over the next 12 months, according to S&P, a deceleration versus the last three years. Despite the slowdown, this projection is above average for the sector and suggests the market sees some success for its newer products.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate.
e.l.f. Beauty has shown strong cash profitability, driven by its attractive business model that enables it to reinvest or return capital to investors. The company’s free cash flow margin averaged 12.6% over the last two years, impressive for a consumer staples business.
e.l.f. Beauty’s margin expanded by 4 percentage points over the last year. This shows the company is heading in the right direction, and it became a less capital-intensive business because its free cash flow profitability rose while its operating profitability was flat.
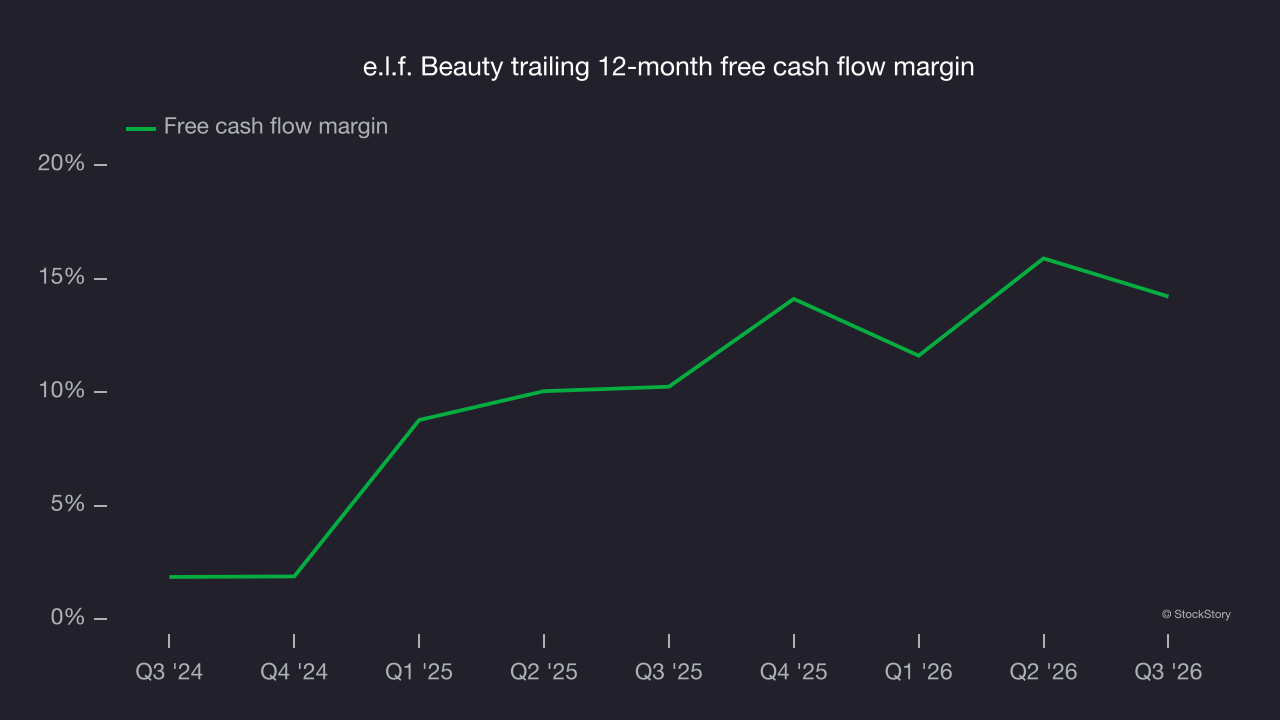
e.l.f. Beauty’s free cash flow came in at $12.1 million in Q3, equivalent to a 2.3% margin. The company’s cash profitability declined by 2.5 percentage points from the same quarter last year, but quarterly changes warrant caution because capital expenditures can be seasonal and companies often stockpile inventory in anticipation of higher demand, leading to quarter-to-quarter swings. Long-term trends are more important.
Key takeaways from e.l.f. Beauty’s Q3 results
A wide EBITDA beat and EPS above analysts’ consensus estimates made this a solid quarter for e.l.f. Beauty. Shares rose 3.4% to $117.50 immediately after the results.
e.l.f. Beauty had a solid quarter, but is the stock a buy? The latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. Read the full research report here (it’s free).