

Natural gas producer Comstock Resources (NYSE:CRK) missed Wall Street’s revenue expectations in Q3 2026, but revenue rose 14.9% year on year to $384.4 million. Its non-GAAP profit of $0.02 per share was $0.02 below analysts’ consensus estimates.
For more on Comstock Resources, read our free full research report.
Comstock Resources (CRK) Q3 2026 highlights:
- Revenue $384.4 million vs S&P analysts’ consensus estimates of $388.5 million (14.9% year-on-year growth, 1.1% miss)
- Adjusted EPS $0.02 vs S&P analysts’ consensus estimates of $0.04 ($0.02 miss)
- Operating margin 6%, down from 15% in the same quarter last year
- Oil production down -36.4% year on year
- Market capitalization $4.06 billion
Revenue growth
Cyclical industries such as energy can make mediocre companies look strong for a time, but a long-term view reveals which businesses can withstand and adapt to changing conditions. Over the last five years, Comstock Resources grew its revenue at a weak 1.4% compounded annual growth rate, falling short of our benchmarks.
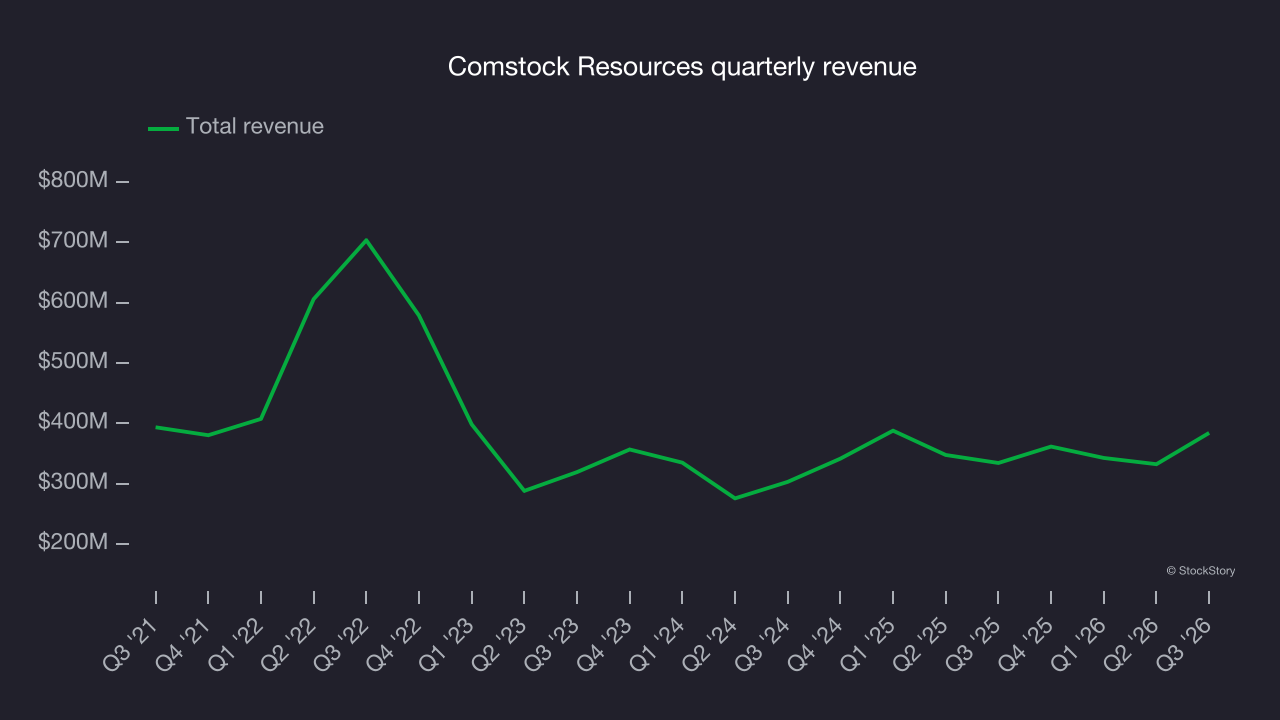
Energy cycles can be long enough that a single five-year period can still reflect one price environment, which is why an additional, decade-long view can help capture through-cycle performance. Comstock Resources’s annualized revenue growth of 23.2% over the last ten years is above its five-year trend.
While looking at revenue is important, it can also introduce noise around commodity prices and mergers and acquisitions. Analyzing drivers of revenue, on the other hand, highlights what is happening inside the asset base and whether the economic footprint of a company is expanding. Over the last two years, Comstock Resources’s oil production averaged 28.3% year-on-year declines while its natural gas production averaged 9.3% year-on-year declines.
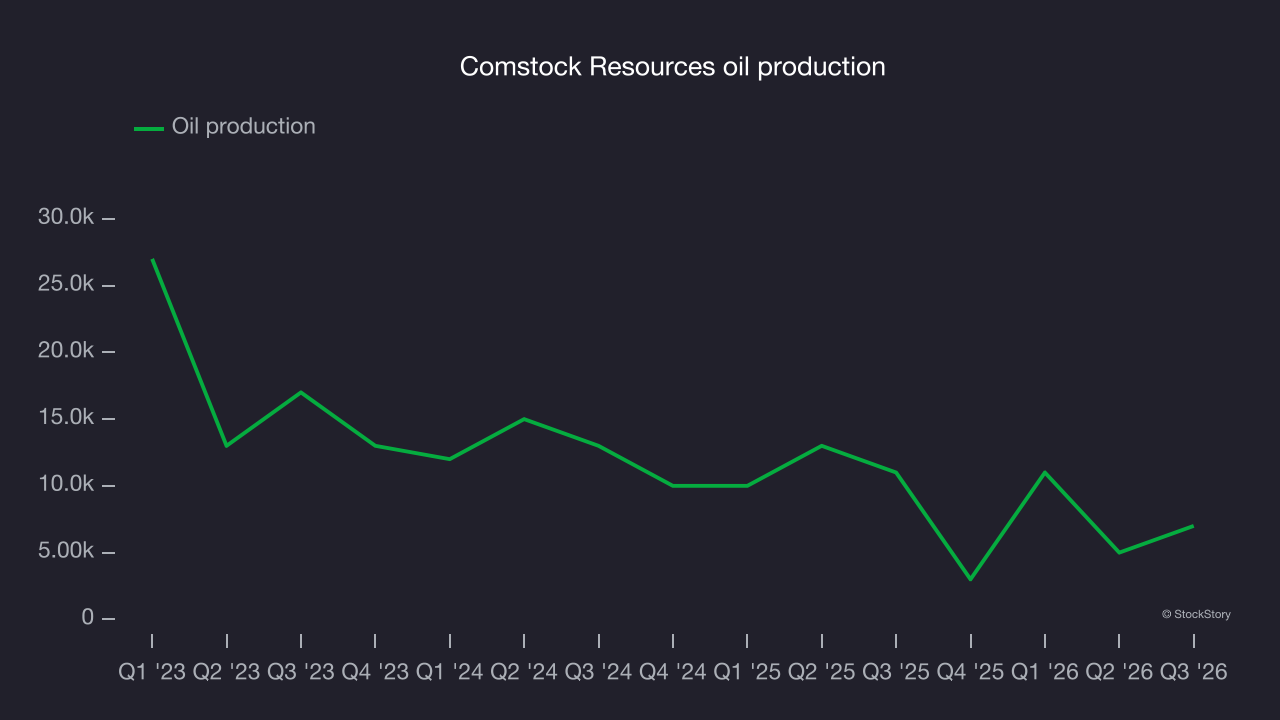
This quarter, Comstock Resources’s revenue grew by 14.9% year on year to $384.4 million but fell short of Wall Street’s consensus estimates. Its oil production fell by 36.4% year on year.
Adjusted EBITDA margin
Comstock Resources has performed well over the last five years. It demonstrated strong profitability for an upstream and integrated energy business, with an average EBITDA margin of 73.2%.
Analyzing the trend in its profitability, Comstock Resources’s EBITDA margin decreased by 15.1 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
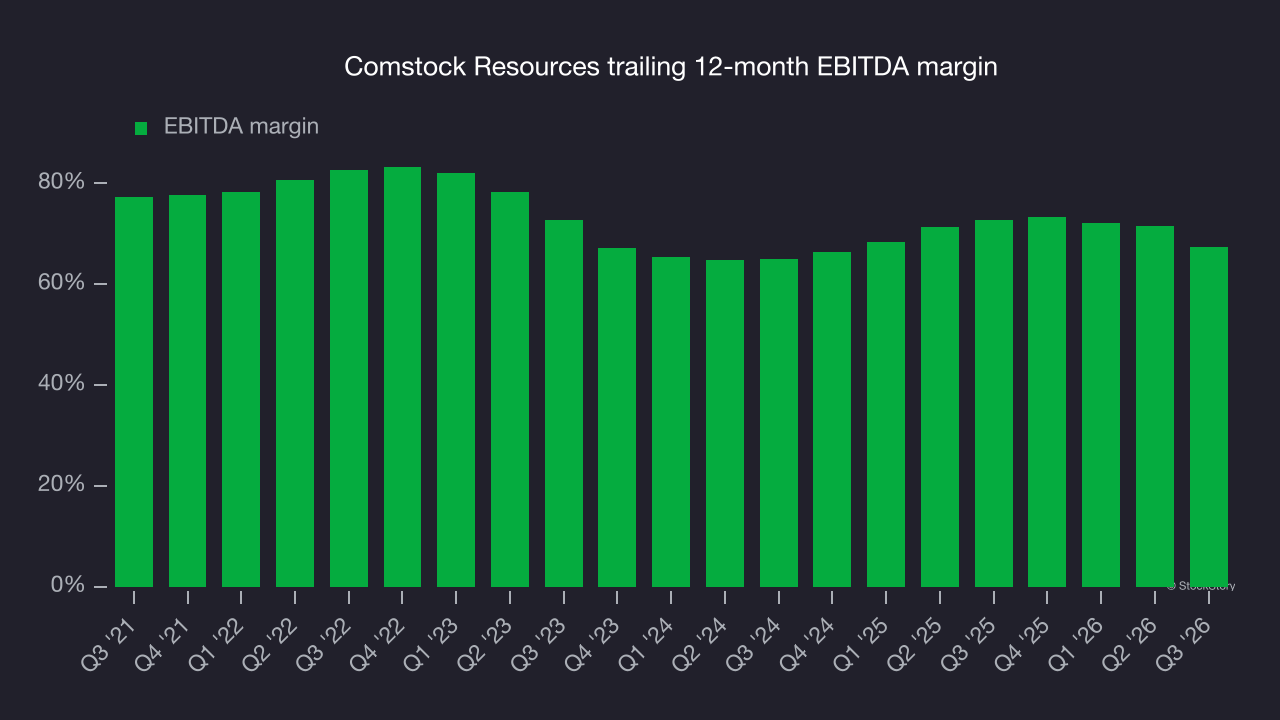
This quarter, Comstock Resources generated an EBITDA margin of 56.2%, down 15.5 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Its adjusted EBITDA fell short of Wall Street’s consensus estimates.
Key takeaways from Comstock Resources’s Q3 results
Comstock Resources delivered a softer quarter with few positives: EPS met expectations, but revenue came in slightly below Wall Street’s consensus estimates. Shares remained flat at $13.39 immediately after the results.
To assess whether Comstock Resources is a buy, it’s important to consider its valuation, business quality and latest quarterly results. Read our full research report here (it’s free).