

Over the past six months, Vita Coco’s shares (currently trading at $56.75) have posted a disappointing 15.6% loss, well below the S&P 500’s 5.3% gain. This might have investors contemplating their next move.
Following the pullback, is this a buying opportunity for COCO? Find out in our full research report, it’s free.
Why is COCO a good business?
Founded in 2004 followed by a 2021 IPO, The Vita Coco Company (NASDAQ:COCO) offers coconut water products that are a natural way to quench thirst.
1. Elevated demand drives higher sales volumes
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
Vita Coco’s average quarterly volume growth of 18.2% over the last two years has beaten the competition by a long shot. This is great because companies with significant volume growth are needles in a haystack in the stable consumer staples sector. 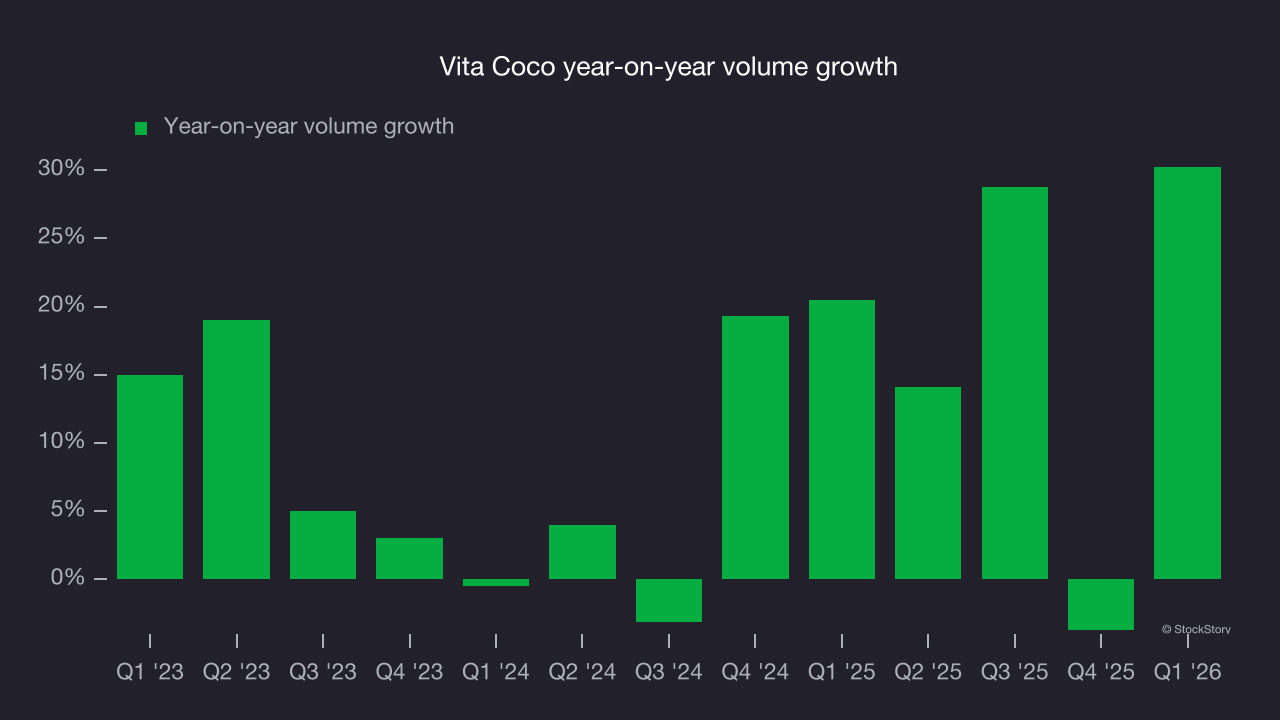
2. Outstanding long-term EPS growth
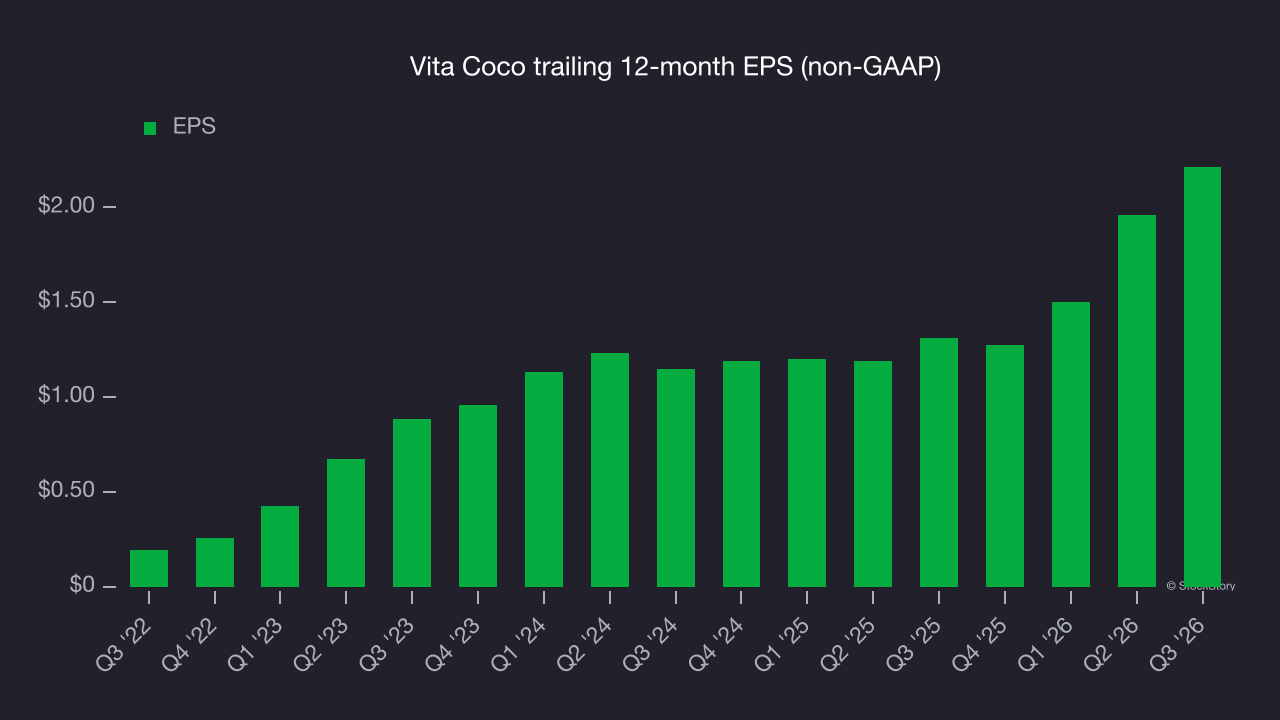
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Vita Coco’s EPS grew at 35.9% compounded annual growth rate over the last three years, higher than its 17% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Increasing free cash flow margin juices financials
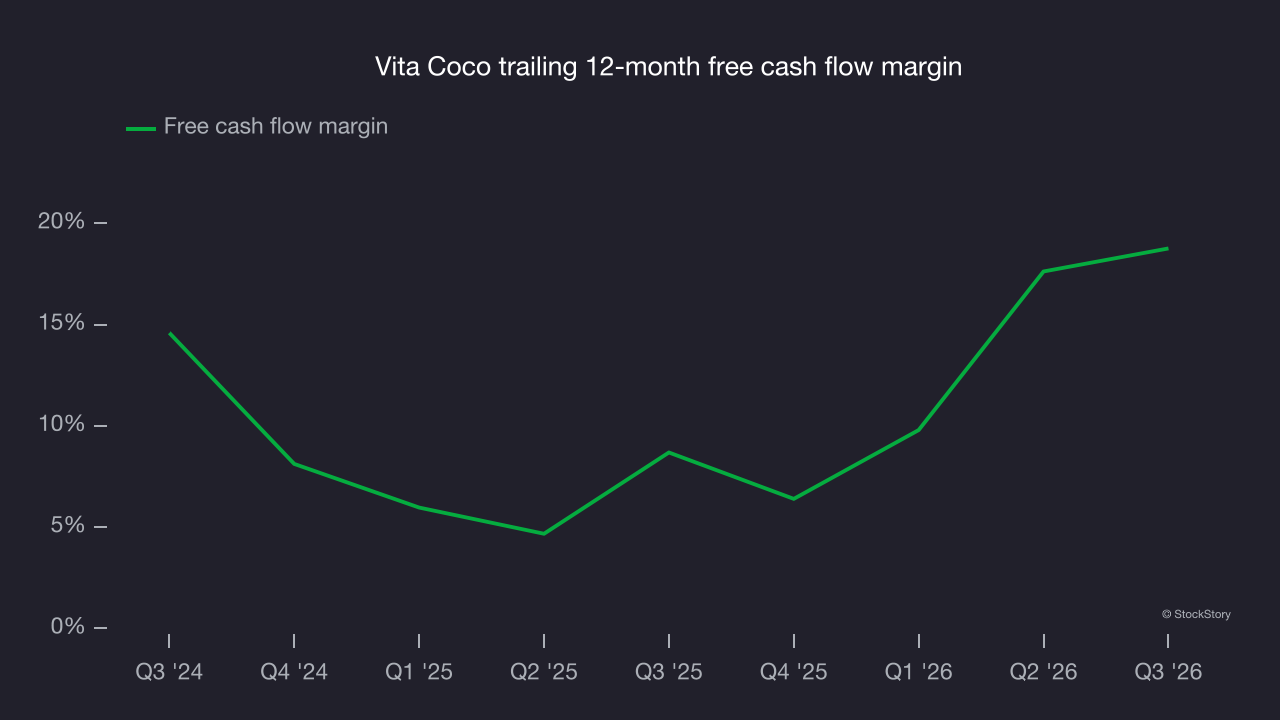
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, Vita Coco’s margin expanded by 10.1 percentage points over the last year. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Vita Coco’s free cash flow margin for the trailing 12 months was 18.8%.
Final judgment
These are just a few reasons why we think Vita Coco is a high-quality business. After the recent drawdown, the stock trades at 28.9× forward P/E (or $56.75 per share). Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
Stocks we like even more than Vita Coco
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.