

Specialty food company The Marzetti Company (NASDAQ:MZTI) fell short of the market’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), with revenue flat year on year at $481.5 million. Its non-GAAP profit of $1.14 per share was 16.9% below analysts’ consensus estimates.
For more on The Marzetti Company, read our free full research report.
The Marzetti Company (MZTI) Q3 CY2026 highlights:
- Revenue $481.5 million vs S&P analysts’ consensus estimates of $484 million (flat year on year, 0.5% miss)
- Adjusted EPS $1.14 vs S&P analysts’ consensus estimates of $1.37 (16.9% miss)
- Operating margin 8.6%, down from 12.3% in the same quarter last year
- Sales volumes were flat year on year (3.2% in the same quarter last year)
- Market capitalization $3.03 billion
CEO David A. Ciesinski commented, “The cyclospora outbreak had a significant impact on this quarter’s top and bottom-line results. The outbreak resulted in lower sales for both our Retail and Foodservice segments, with the impact on Retail segment net sales more notable, accounting for an estimated year-over-year net sales decline of approximately 4% due to lower demand for our Retail dressing, dip and crouton products. On a positive note, other areas of our business continued to perform well and the cyclospora impact has moderated in recent weeks.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years.
With $1.91 billion in revenue over the past 12 months, The Marzetti Company is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
The Marzetti Company struggled to increase demand as its $1.91 billion in revenue for the trailing 12 months was close to its revenue three years ago. On the positive side, consumers bought more of its products – the “Volume Growth” section explores what this means.
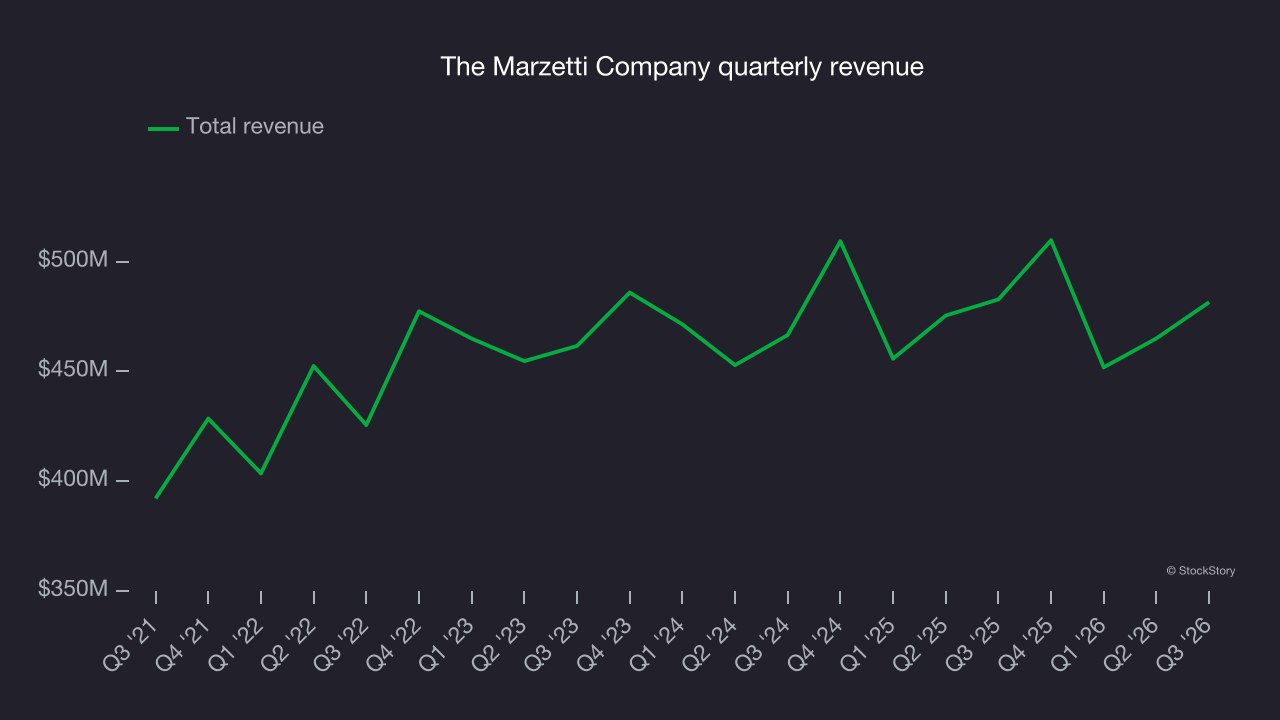
This quarter, The Marzetti Company’s $481.5 million of revenue was flat year on year, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 5.7% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is above the sector average and suggests its newer products will fuel better top-line performance.
Volume growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is essential to a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
The Marzetti Company’s quarterly sales volumes have, on average, stayed about the same over the last two years. This stability is normal because the quantity demanded for consumer staples products typically doesn’t see much volatility. 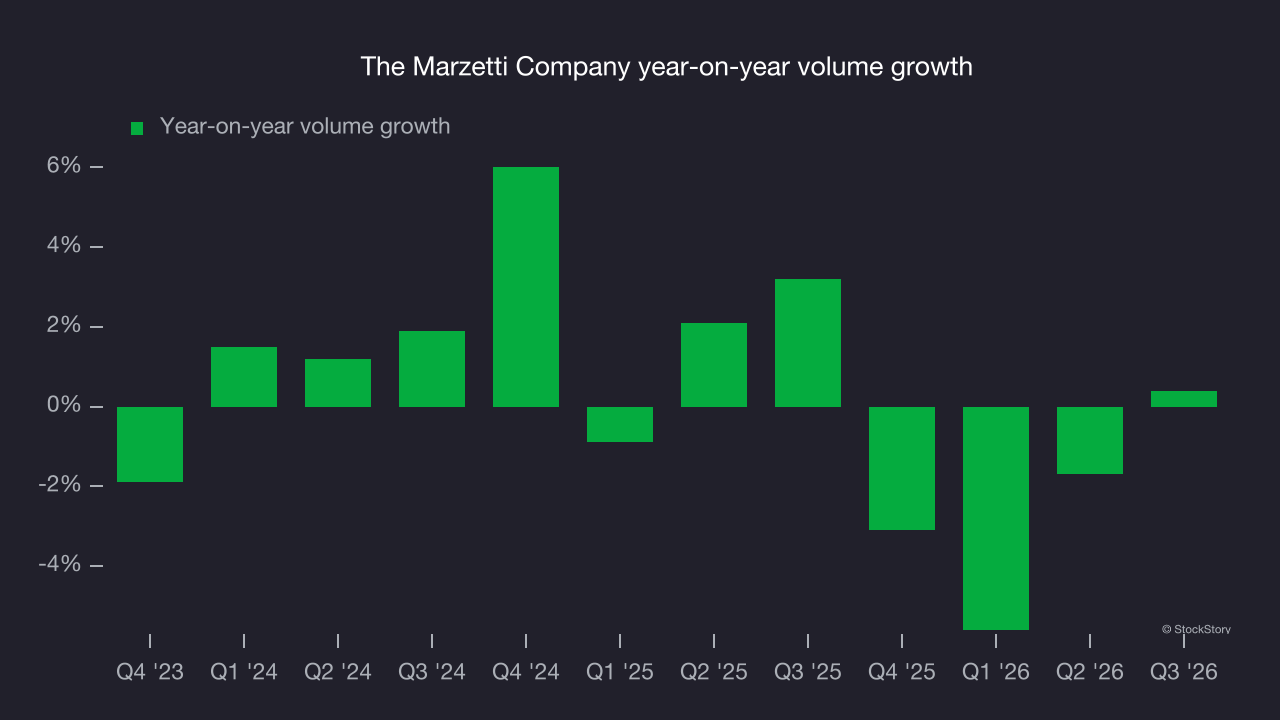
In Q3 2027, The Marzetti Company’s sales volumes were flat year over year. This result was roughly in line with its historical levels.
Key takeaways from The Marzetti Company’s Q3 results
The Marzetti Company’s gross margin miss and EPS shortfall against Wall Street’s consensus estimates left few positives in a softer quarter. Shares fell 2.8% to $107.80 immediately after the results.
The Marzetti Company had a disappointing quarter, but does that create a buying opportunity? That decision calls for a broader look at its valuation, business quality and latest earnings. Read the full research report here (it’s free).