

Industrial products and automation company Regal Rexnord (NYSE:RRX) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 6.1% year on year to $1.59 billion. Its non-GAAP profit of $2.90 per share was 8.7% above analysts’ consensus estimates.
For more on Regal Rexnord, read our free full research report.
Regal Rexnord (RRX) Q3 2026 highlights:
- Revenue $1.59 billion vs S&P analysts’ consensus estimates of $1.56 billion (6.1% year-on-year growth, 1.7% beat)
- Adjusted EPS $2.90 vs S&P analysts’ consensus estimates of $2.67 (8.7% beat)
- Adjusted EBITDA $351.3 million vs analysts’ consensus estimates of $341.3 million (22.1% margin, 2.9% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $10.75 at the midpoint, a 1.4% increase
- Operating margin 5.1%, down from 11.6% in the same quarter last year
- Free cash flow margin 12.2%, similar to the same quarter last year
- Organic revenue rose 6.1% year on year (beat)
- Market capitalization $10.72 billion
CEO Aamir Paul commented on the third-quarter performance, "Our third quarter execution showed steady progress. We delivered adjusted EBITDA excluding IEEPA refunds slightly ahead of our expectations. We had healthy order demand across the portfolio, with 13% orders growth excluding data centers. We were encouraged by the orders growth in commercial HVAC, up 47%, aided by new air moving solutions. Discrete automation orders were up 26%. Data center order growth continues to scale, with some specific project order timing effects in the quarter."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Regal Rexnord’s 12.8% annualized revenue growth over the last five years was strong. Its growth beat the average industrials company and shows its offerings resonate with customers.
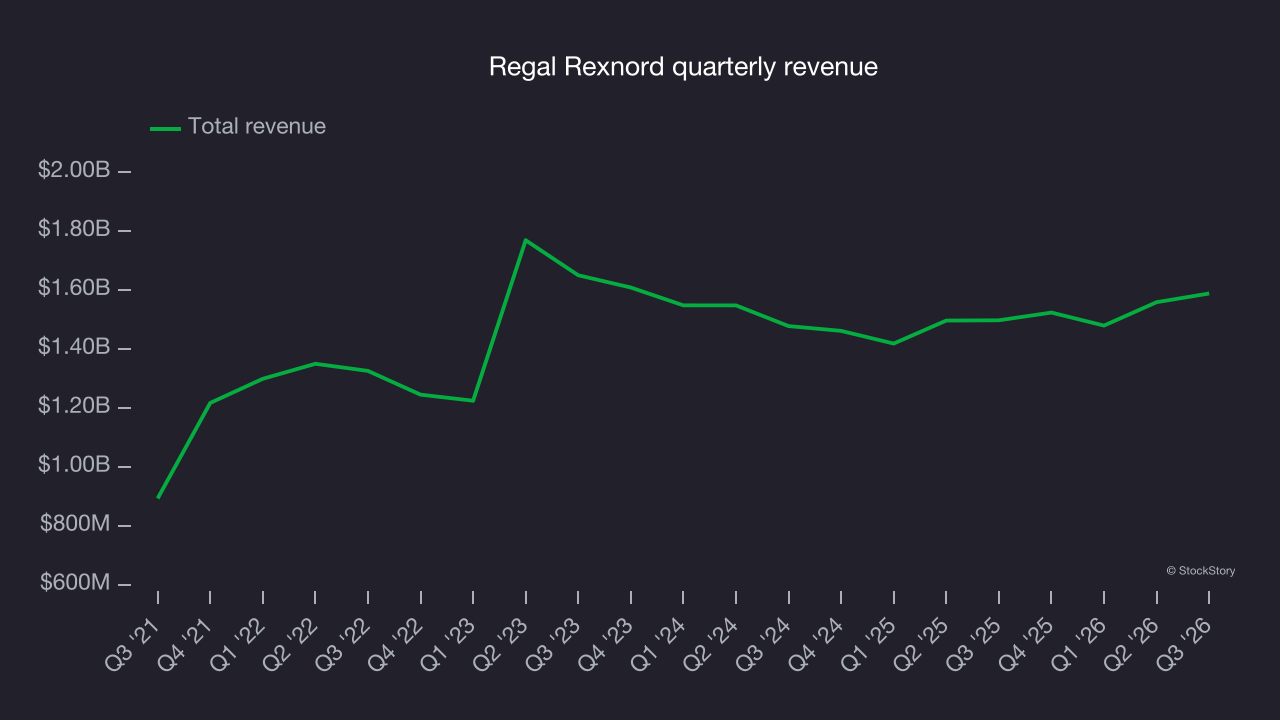
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Regal Rexnord’s recent performance shows its demand has slowed significantly as its revenue was flat over the last two years. 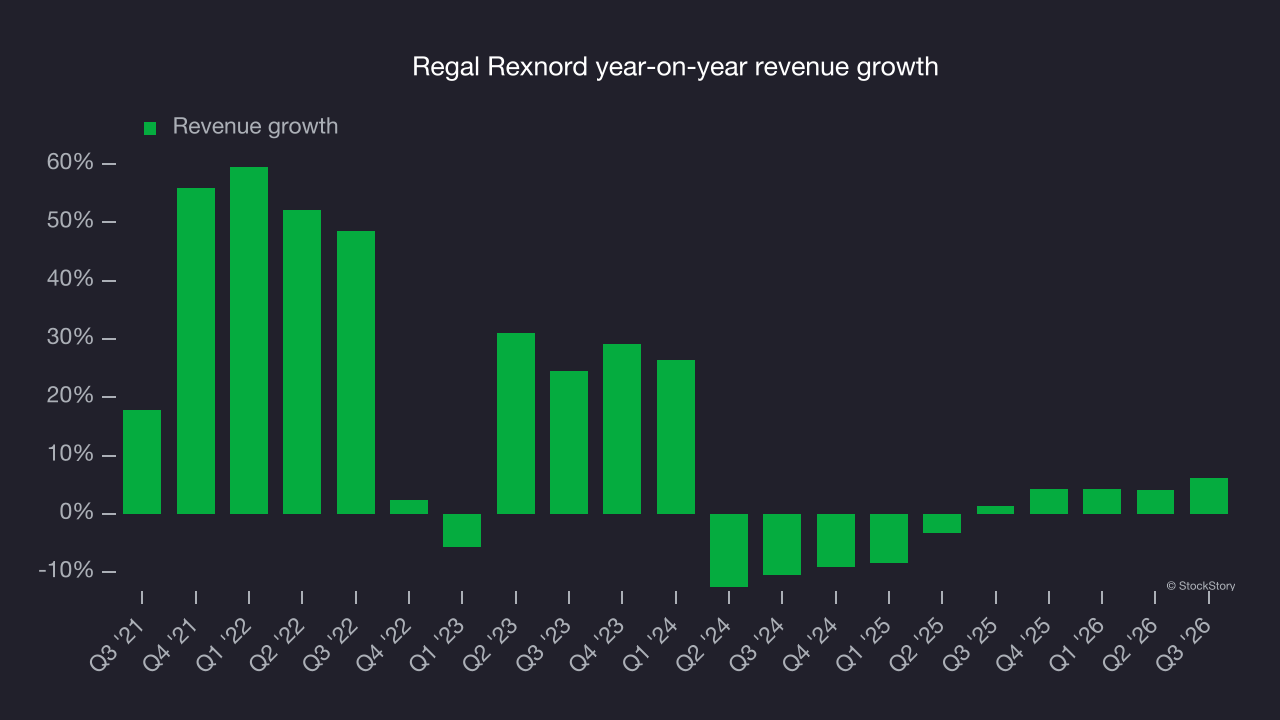
Analyzing the company’s organic revenue helps explain its revenue dynamics by stripping out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, Regal Rexnord’s organic revenue averaged 1.6% year-on-year growth. Organic revenue growth outpaced its two-year revenue growth, indicating that some combination of divestitures and foreign exchange rates dampened its headline results. 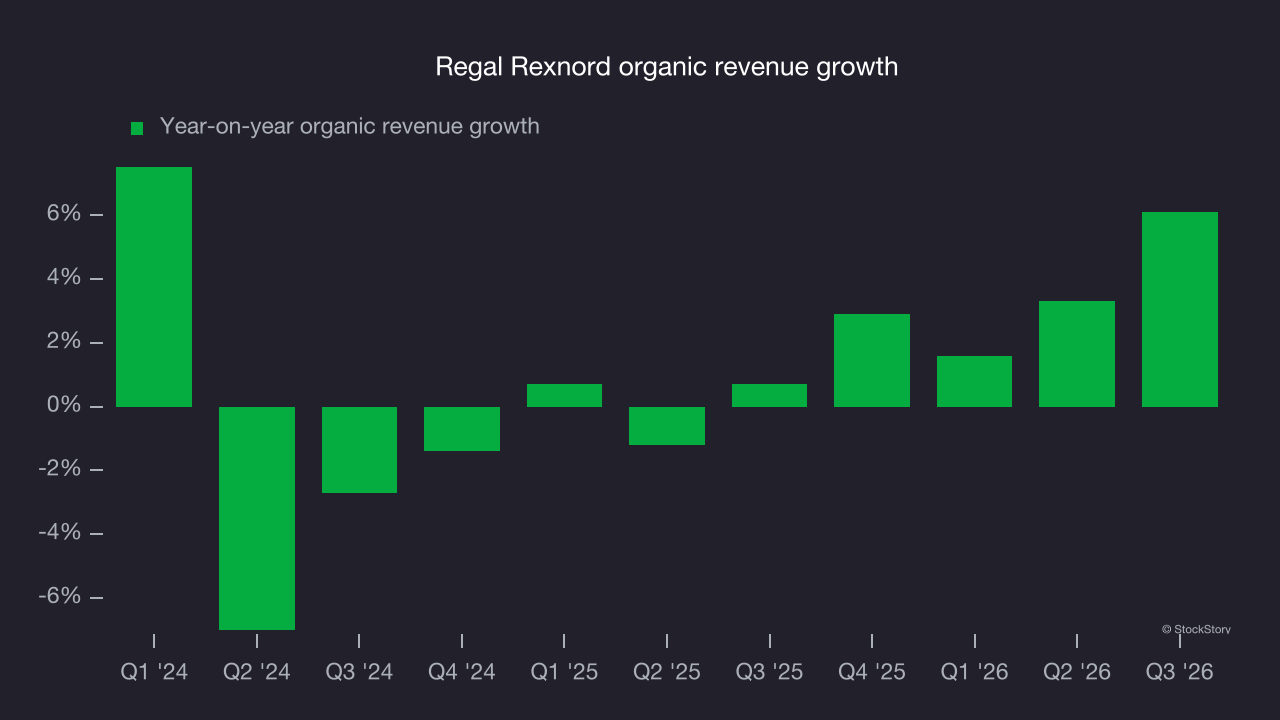
This quarter, Regal Rexnord reported year-on-year revenue growth of 6.1%, and its $1.59 billion of revenue exceeded Wall Street’s consensus estimates by 1.7%.
Looking ahead, sell-side analysts expect revenue to grow 10.8% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is noteworthy and indicates its newer products and services will spur better top-line performance.
Operating margin
Regal Rexnord’s operating margin has remained largely unchanged over the last 12 months, averaging 9.7% over the last five years. This profitability was higher than the broader industrials sector, showing it managed its expenses reasonably well.
Looking at the trend in its profitability, Regal Rexnord’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
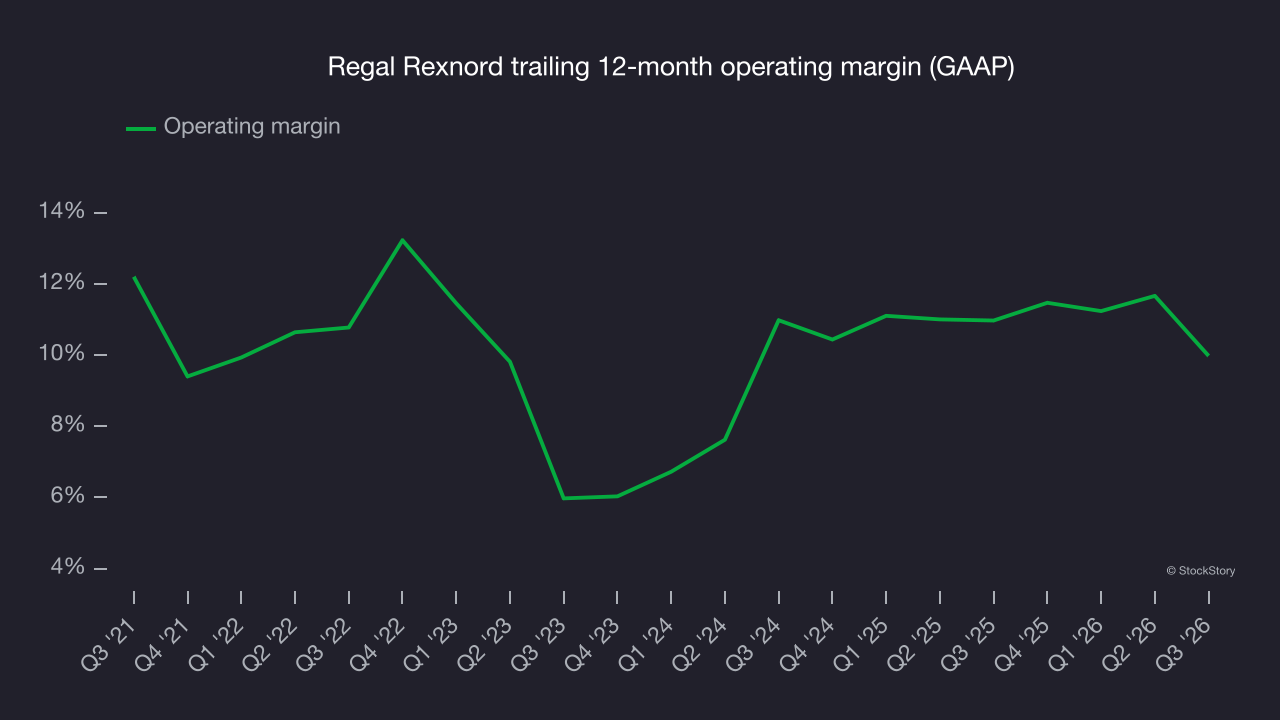
In Q3, Regal Rexnord generated an operating margin of 5.1%, down 6.5 percentage points year on year. Its operating margin decreased more than its gross margin, suggesting it was less efficient because expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Regal Rexnord’s EPS grew at an unimpressive 4.7% compounded annual growth rate over the last five years, lower than its 12.8% annualized revenue growth. However, its operating margin didn’t change during this time, telling us that non-fundamental factors such as interest and taxes affected its ultimate earnings.
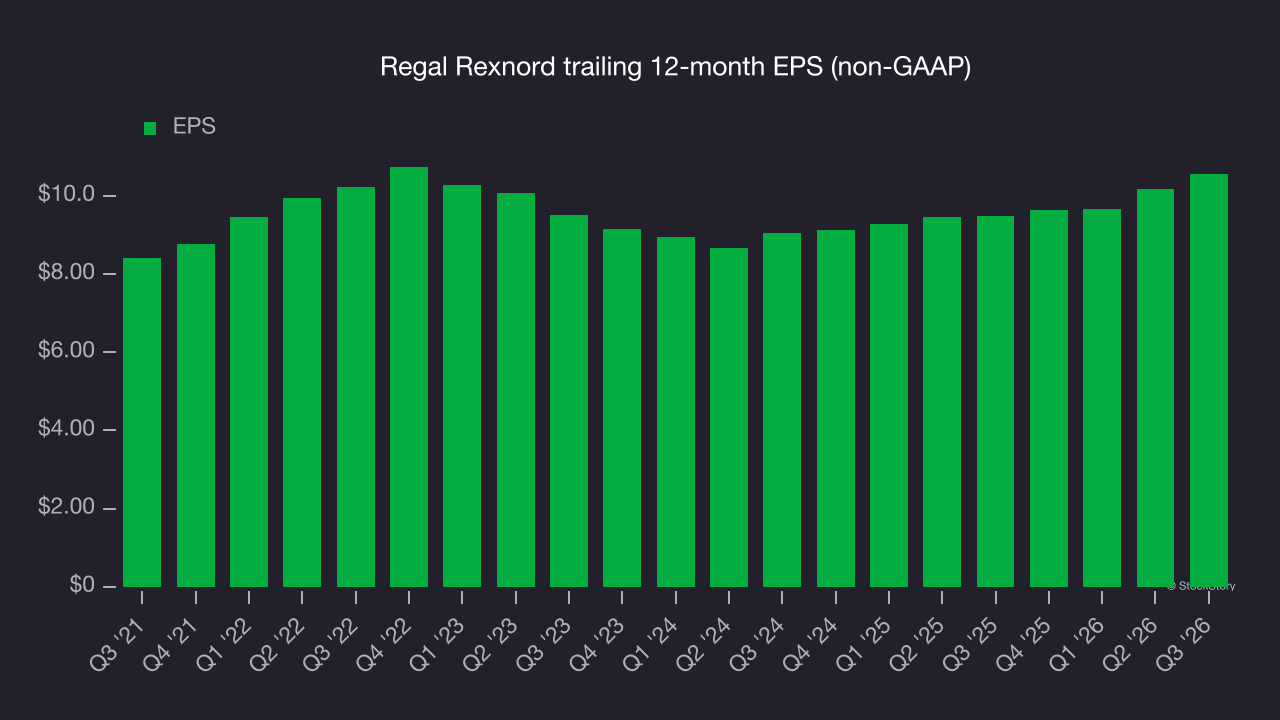
Diving into the nuances of Regal Rexnord’s earnings can give us a better understanding of its performance. A five-year view shows Regal Rexnord has diluted its shareholders, growing its share count by 62.4%. This has led to lower per share earnings. Taxes and interest expenses can also affect EPS but don’t tell us as much about a company’s fundamentals. 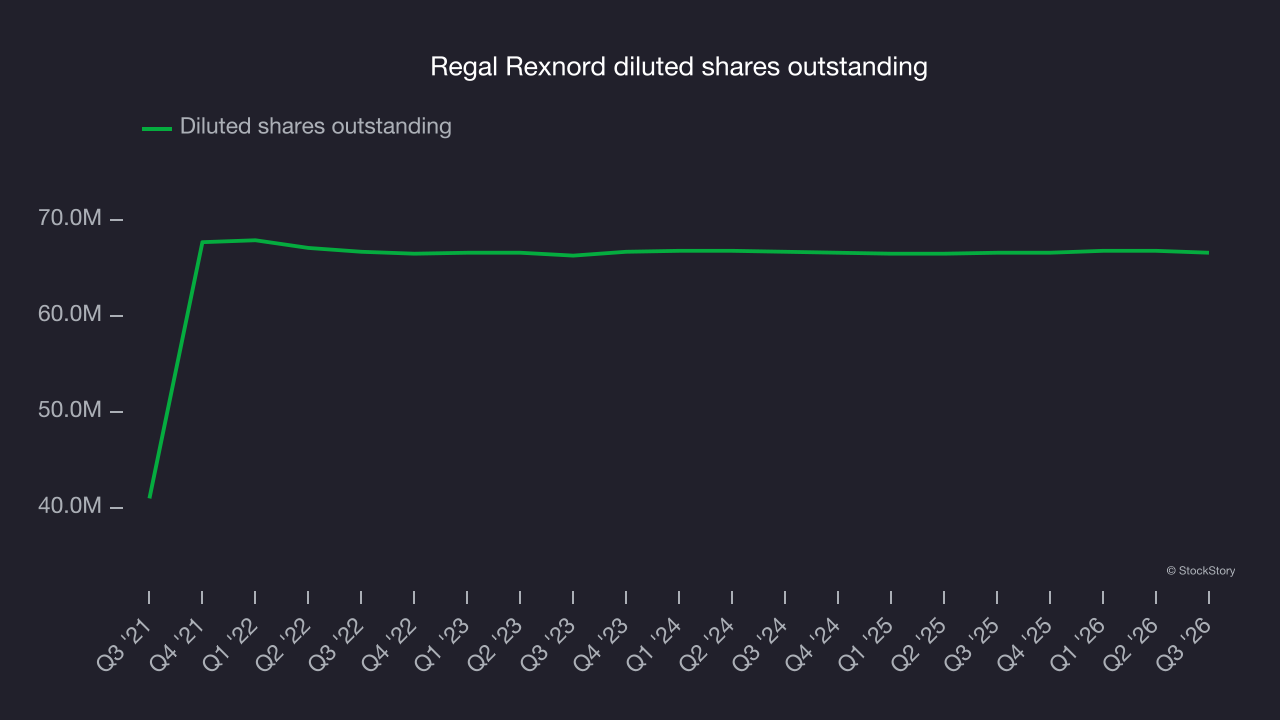
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Regal Rexnord, its two-year annual EPS growth of 8% was higher than its five-year trend. Accelerating earnings growth is almost always a positive sign.
In Q3, Regal Rexnord reported adjusted EPS of $2.90, up from $2.51 in the same quarter last year. This result beat analysts’ consensus estimates by 8.7%. Over the next 12 months, Wall Street expects Regal Rexnord’s full-year EPS to grow 17.2% from $10.57 to $12.39, according to S&P.
Key takeaways from Regal Rexnord’s Q3 results
Regal Rexnord delivered a decent quarter, topping expectations for both organic revenue and total revenue. Those beats left some key metrics above analysts’ consensus estimates, but the market seemed to be hoping for more. Shares edged lower 1% to $159.28 immediately after the report.
The latest quarter matters when deciding whether to buy the stock, but longer-term fundamentals and valuation matter much more. Read the free full research report for more on these factors.