

First Citizens BancShares currently trades at $2,369 and has been a dream stock for shareholders. It’s returned 178% since November 2021, nearly tripling the S&P 500’s 62.6% gain. The company has also beaten the index over the past six months as its stock price is up 21.2% thanks to its solid quarterly results.
Is there a buying opportunity in First Citizens BancShares, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why is First Citizens BancShares not exciting?
We’re glad investors have benefited from the price increase, but we’re cautious about First Citizens BancShares. Here are three reasons why FCNCA doesn’t excite us, plus one stock we’d rather own.
1. Revenue tumbling downwards
Long-term growth is the most important, but within financials, a stretched historical view may miss recent interest rate changes and market returns. First Citizens BancShares’s recent performance marks a sharp pivot from its five-year trend as its revenue has shown annualized declines of 1.8% over the last two years. 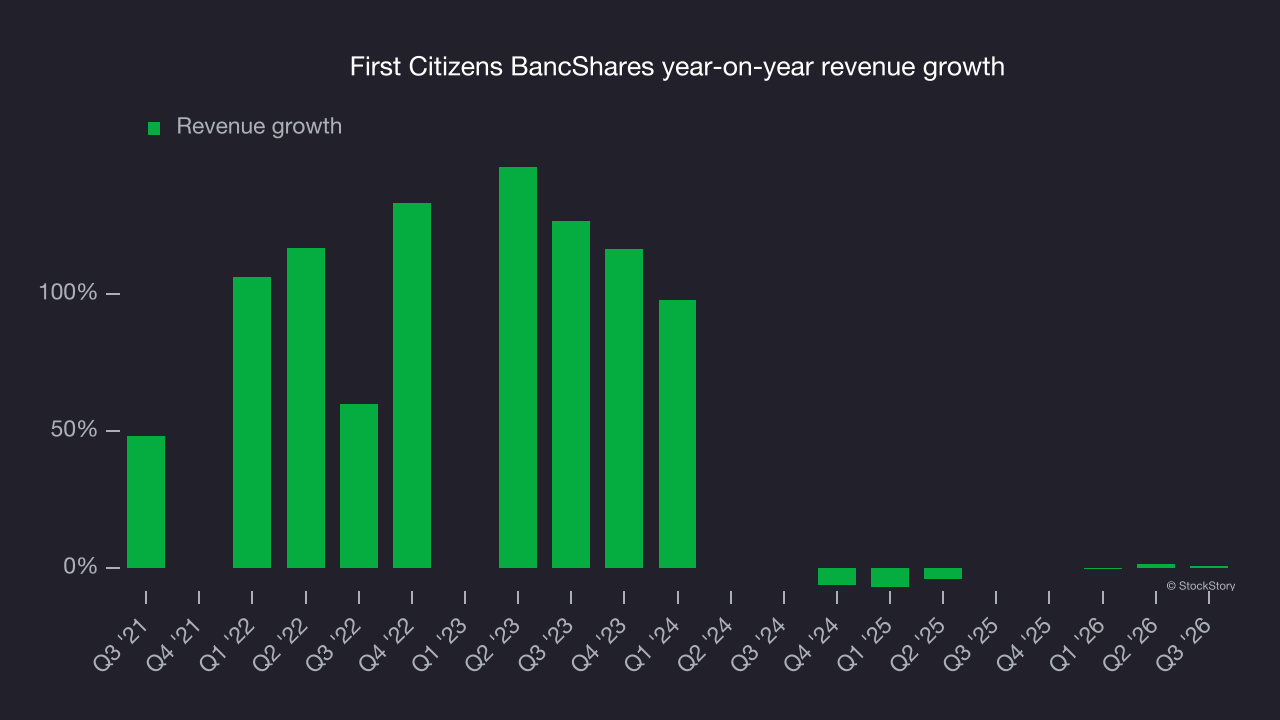 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
2. Net interest margin dropping
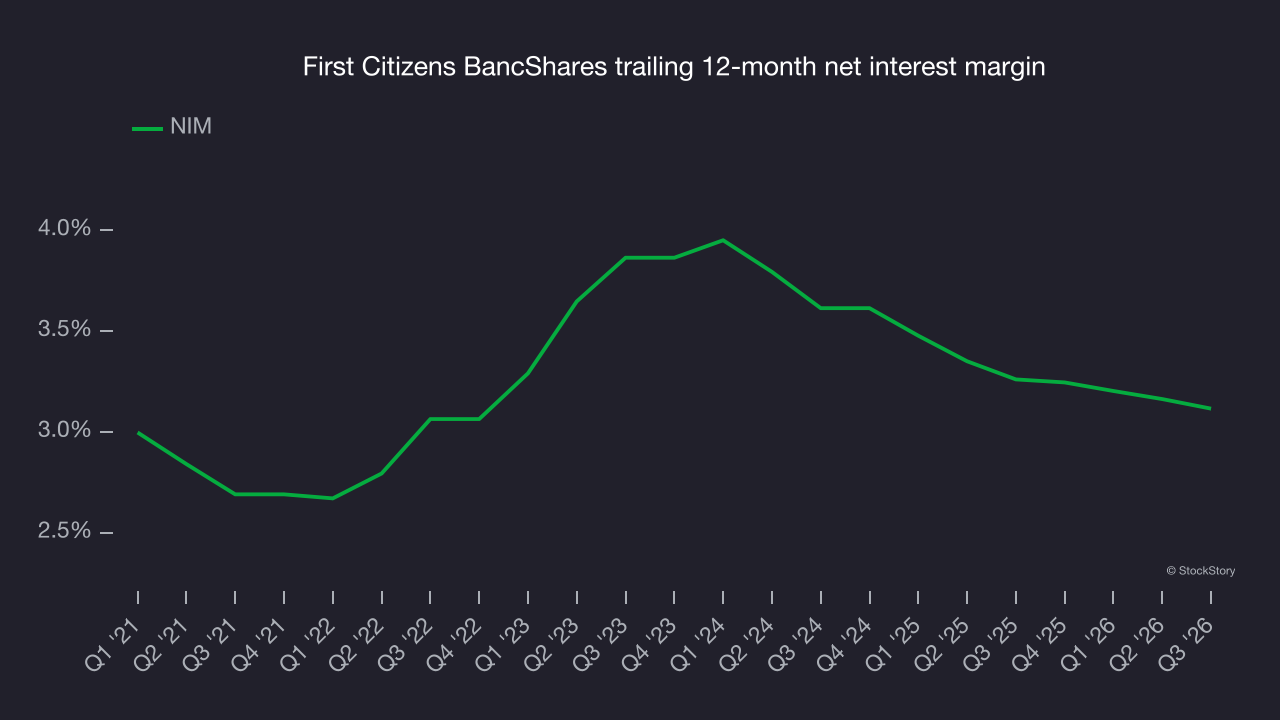
Net interest margin (NIM) represents the unit economics of a bank by measuring the profitability of its interest-bearing assets relative to its interest-bearing liabilities. It’s a fundamental metric that investors use to assess lending premiums and returns.
Over the past two years, First Citizens BancShares’s net interest margin averaged 3.2%. Its margin also contracted by 49.8 basis points (100 basis points = 1 percentage point) over that period.
This decline was a headwind for its net interest income. While prevailing rates are a major determinant of net interest margin changes over time, the decline could mean that First Citizens BancShares either faced competition for loans and deposits or experienced a negative mix shift in its balance sheet composition.
3. Recent EPS growth below our standards
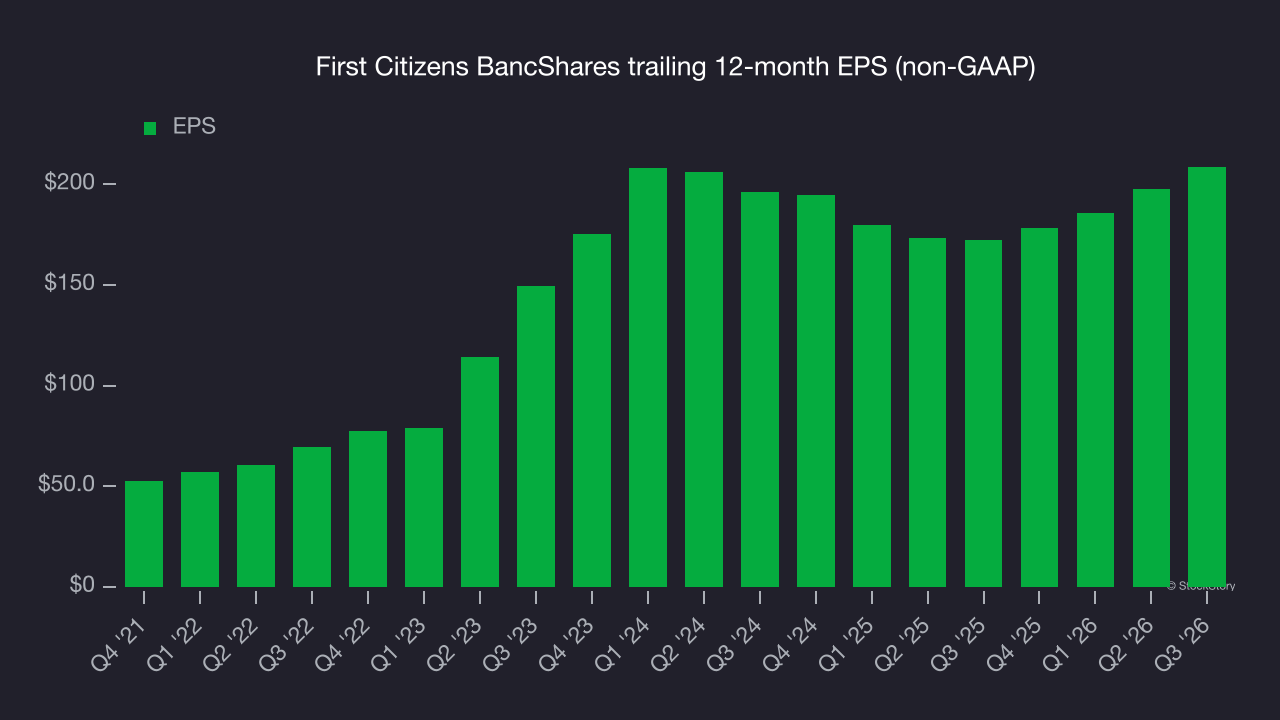
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
First Citizens BancShares’s EPS grew at a weak 3.1% compounded annual growth rate over the last two years. On the bright side, this performance was higher than its 1.8% annualized revenue declines and tells us management adapted its cost structure in response to a challenging demand environment.
Final judgment
First Citizens BancShares isn’t a terrible business, but it isn’t one of our picks. With its shares beating the market recently, the stock trades at 1.3× forward P/B (or $2,369 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at the Amazon and PayPal of Latin America.
High-quality stocks for all market conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.