

Oilfield services provider Expro (NYSE:XPRO) missed Wall Street’s revenue expectations in Q3 2026, but revenue rose 6.9% year on year to $439.9 million. On the other hand, next quarter’s outlook exceeded expectations with revenue guided to $475 million at the midpoint, or 2.3% above analysts’ consensus estimates. Its non-GAAP profit of $0.19 per share was 33.5% below analysts’ consensus estimates.
For more on Expro, read our free full research report.
Expro (XPRO) Q3 2026 highlights:
- Revenue $439.9 million vs S&P analysts’ consensus estimates of $443 million (6.9% year-on-year growth, 0.7% miss)
- Adjusted EPS $0.19 vs S&P analysts’ consensus estimates of $0.29 (33.5% miss)
- Adjusted EBITDA $91.21 million vs analysts’ consensus estimates of $93.06 million (20.7% margin, 2% miss)
- Revenue guidance $475 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $464.4 million
- EBITDA guidance $335 million at the midpoint for the full year, below analysts’ consensus estimates of $347.6 million
- Operating margin 1.1%, down from 6.4% in the same quarter last year
- Market capitalization $1.78 billion
“During the quarter, the Company also made a decision to combine its MENA and APAC geographic regions. The new region now covers Asia, Middle East and North Africa, and has the abbreviation of ‘AMENA’. We are continually looking for ways to optimize and enhance the efficiency of our organization. This move is a direct result of those efforts. We project the AMENA region will have more economies of scale, which will be levered across our service offerings.”
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Over the last five years, Expro grew its revenue at an impressive 18.3% compounded annual growth rate. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
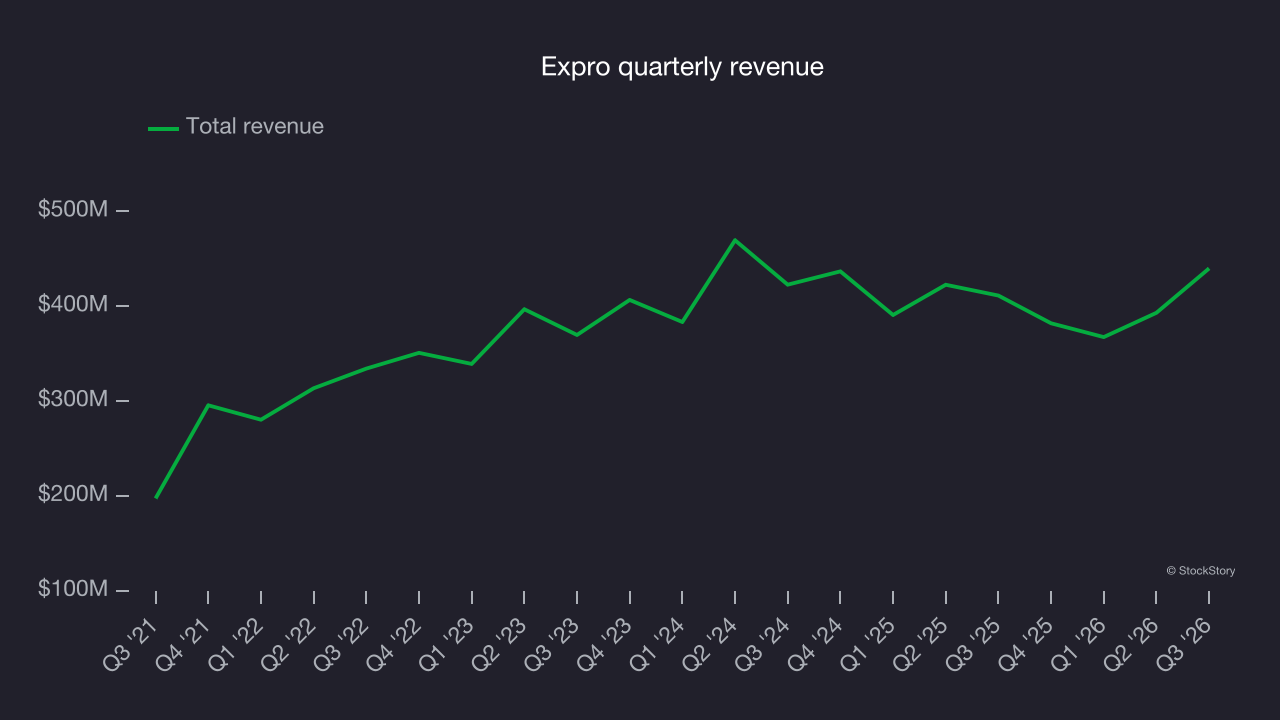
Even a long stretch in energy can be shaped by a single commodity cycle, so extending the view to ten years adds another perspective and reveals which companies can grow across pricing regimes. Expro’s annualized revenue growth of 10.5% over the last ten years is below its five-year trend, but the results still suggest decent demand.
This quarter, Expro’s revenue grew by 6.9% year on year to $439.9 million, missing Wall Street’s consensus estimates. Management is guiding for a 24.3% year-on-year increase in revenue next quarter.
Adjusted EBITDA margin
Adjusted EBITDA margin captures the operating profitability of an energy producer by excluding accounting effects related to depletion and capitalized drilling costs. It reveals how much cash the asset base generates before capital structure and reinvestment requirements shape reported earnings.
Expro was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 18.9% was weak for an upstream and integrated energy business.
On the positive side, Expro’s EBITDA margin rose by 4.9 percentage points over the last year, as its revenue growth gave it operating leverage.
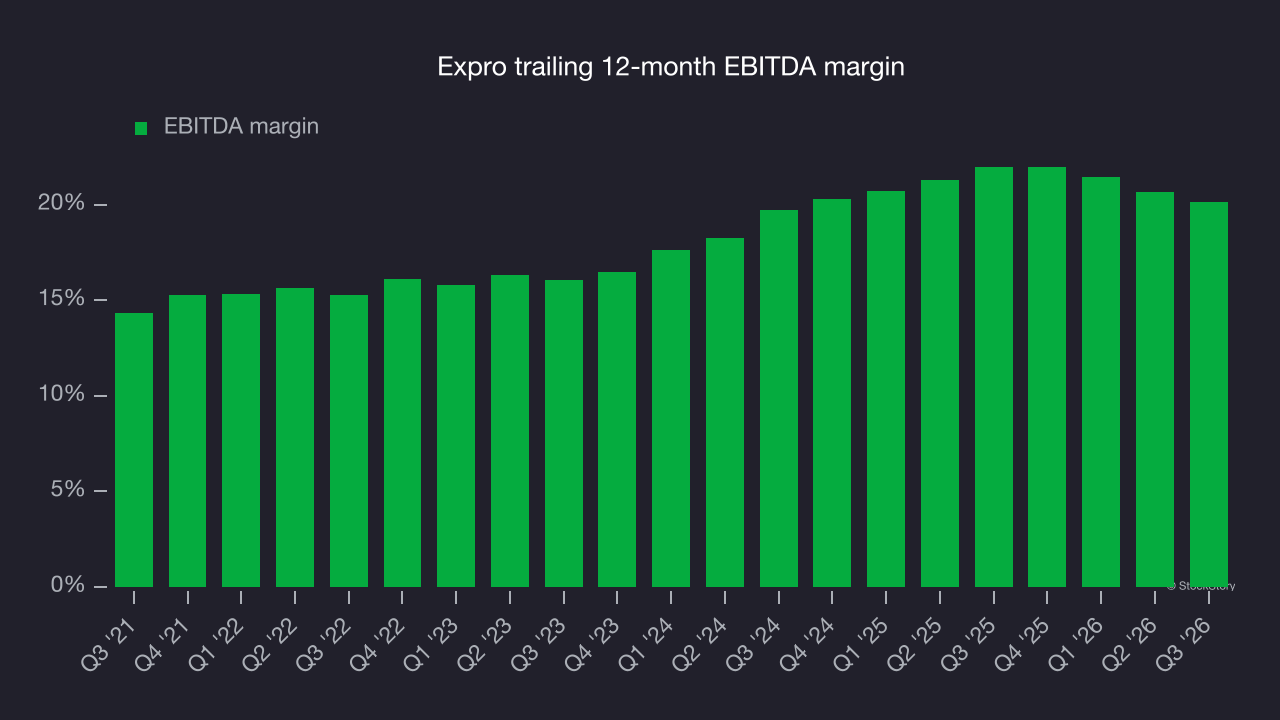
In Q3, Expro generated an EBITDA margin of 20.7%, down 2.1 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Its adjusted EBITDA fell short of Wall Street’s consensus estimates.
Free cash flow
Adjusted EBITDA shows how profitable a company’s existing wells are before financing and reinvestment decisions, but free cash flow shows how much value remains after paying the cost of replacing those wells. In upstream energy, production naturally declines over time, so companies must continuously reinvest just to stand still. A producer can report strong EBITDA margins yet generate little or no free cash flow if its wells decline quickly or if new drilling is expensive. Free cash flow therefore captures not only how efficiently a company produces hydrocarbons today, but also how costly it is to sustain that production into the future.
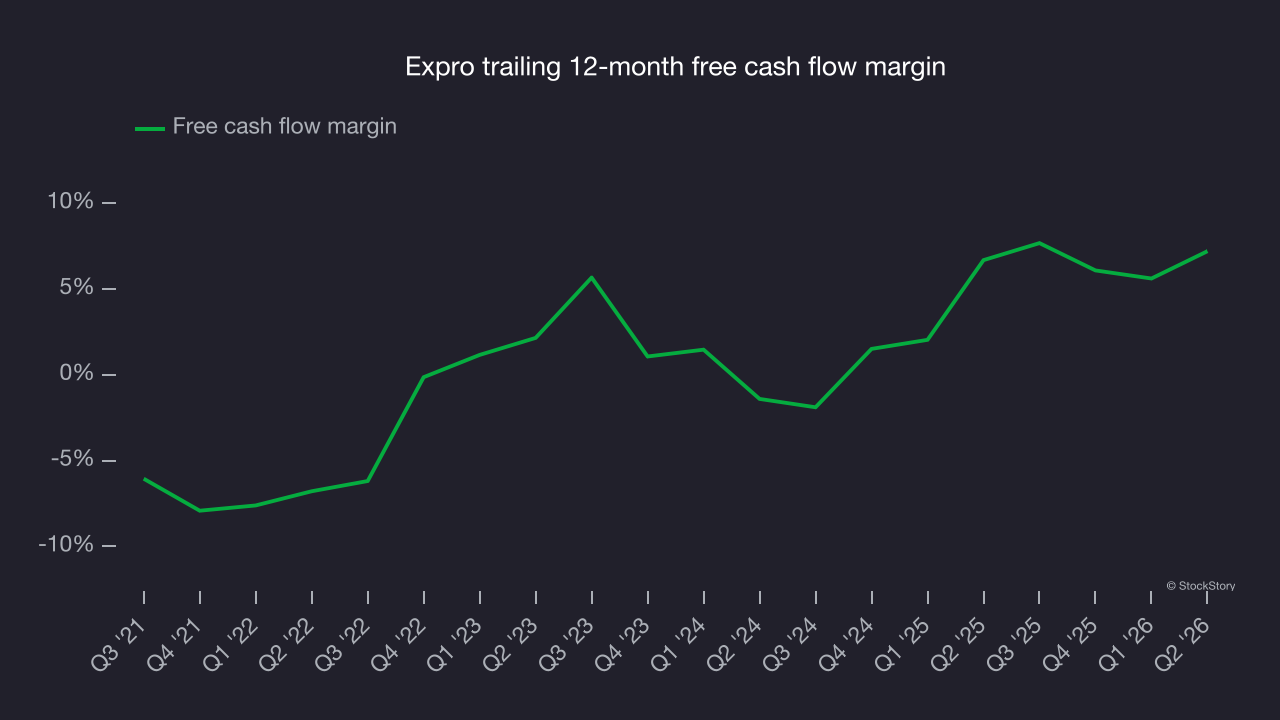
Expro has shown weak cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.4%, below the expected level for an upstream and integrated energy business.
The level of free cash flow is important, but its durability across cycles is just as critical. Consistent margins are far more valuable than volatile swings driven by commodity prices.
Expro’s ratio of quarterly free cash flow volatility to West Texas Intermediate, or WTI, crude price volatility over the past five years was 21.8 (lower is better), indicating that its cash generation is far more sensitive to commodity-price swings than most peers. This elevated volatility limits its access to capital in downturns and makes it unlikely to act as a consolidator when weaker competitors come under pressure.
Why assess stability against commodity prices at the free cash flow line rather than comparing revenue or EBITDA to WTI in Expro’s case? Because what ultimately matters is not how much revenue or profit a company earns when prices are high but how much cash it can generate when prices are low. Free cash flow is the superior metric because it includes everything from hedging effectiveness to growth and maintenance capex to management behavior during good times and bad.
Key takeaways from Expro’s Q3 results
Expro delivered a weaker quarter, with EPS falling short of Wall Street’s consensus estimates and full-year EBITDA guidance also missing expectations. Revenue guidance was a positive: the outlook for next quarter topped analysts’ consensus estimates, and the full-year forecast came in slightly ahead of Wall Street’s consensus. Shares remained flat at $15.95 immediately after the release.
For investors considering Expro, the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. Read the full research report here (it’s free).