

Material handling equipment manufacturer Columbus McKinnon (NASDAQ:CMCO) announced better-than-expected revenue in calendar Q3 2026 (fiscal Q2 2027), with revenue up 107% year on year to $539.3 million. The company’s full-year revenue guidance of $2.15 billion at the midpoint came in 2.4% above analysts’ consensus estimates. Its non-GAAP profit of $0.61 per share was 60.6% above analysts’ consensus estimates.
For more on Columbus McKinnon, read the full research report for free.
Columbus McKinnon (CMCO) Q3 CY2026 highlights:
- Revenue $539.3 million vs S&P analysts’ consensus estimates of $518.6 million (107% year-on-year growth, 4% beat)
- Adjusted EPS $0.61 vs S&P analysts’ consensus estimates of $0.38 (60.6% beat)
- Adjusted EBITDA $111.2 million vs analysts’ consensus estimates of $94.17 million (20.6% margin, 18.1% beat)
- Adjusted EPS guidance $2.08 at the midpoint for the full year, beating analysts’ consensus estimates by 3.1%
- EBITDA guidance $432.5 million at the midpoint for the full year, above analysts’ consensus estimates of $410.5 million
- Operating margin 6.5%, up from 4.5% in the same quarter last year
- Free cash flow -$15.36 million, down from $15.08 million in the same quarter last year
- Market capitalization $449.8 million
"Building on record orders and sales in the first quarter, our team delivered strong second quarter performance that exceeded expectations. Sequential revenue growth was supported by sustained strength in the Americas and bolstered by stronger than anticipated demand in both Asia and EMEA," said David J. Wilson, President and Chief Executive Officer. "Our continued focus on improving operational execution and customer experience led to increased demand from both project and short-cycle business. Early success and strong customer response to our combined portfolio reinforce our confidence in the growth opportunities created by bringing CMCO and Kito Crosby together."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Columbus McKinnon grew its revenue at a strong 17.5% compounded annual growth rate. Its growth beat the average industrials company and shows its offerings resonate with customers.
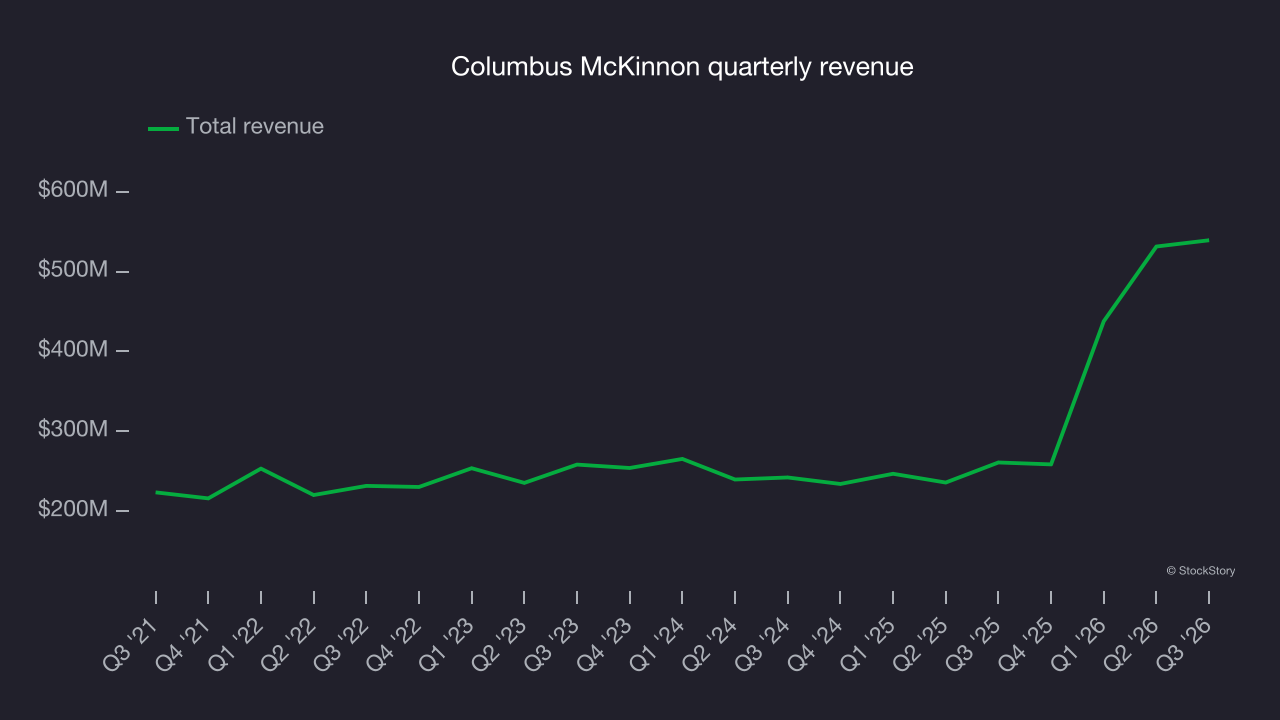
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Columbus McKinnon’s annualized revenue growth of 32.8% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 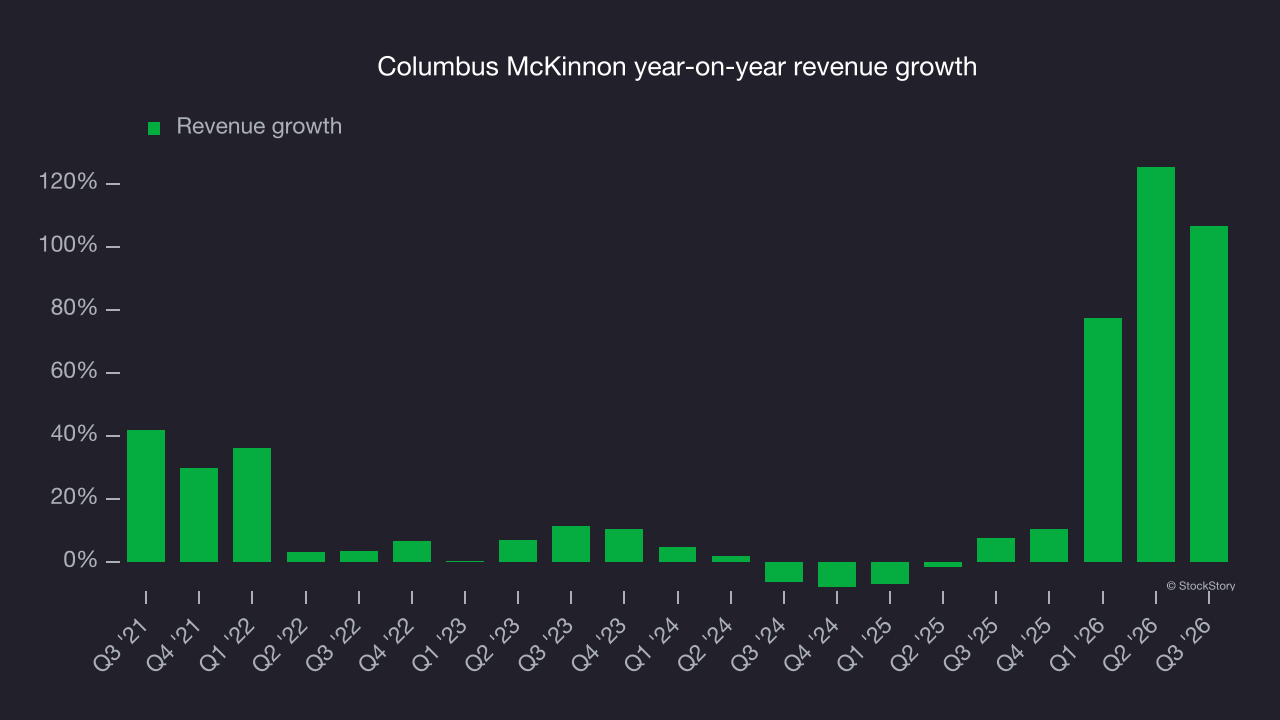
This quarter, Columbus McKinnon reported year-on-year revenue growth of 107%, and its $539.3 million in revenue beat Wall Street’s consensus estimates by 4%.
Looking ahead, sell-side analysts expect revenue to grow 20.9% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is strong and indicates the market expects continued success for its products and services.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income – the bottom line – excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Columbus McKinnon has done a decent job managing its cost base over the last five years. The company has produced an average operating margin of 8.1%, higher than the broader industrials sector.
Analyzing the trend in its profitability, Columbus McKinnon’s operating margin decreased by 1.9 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
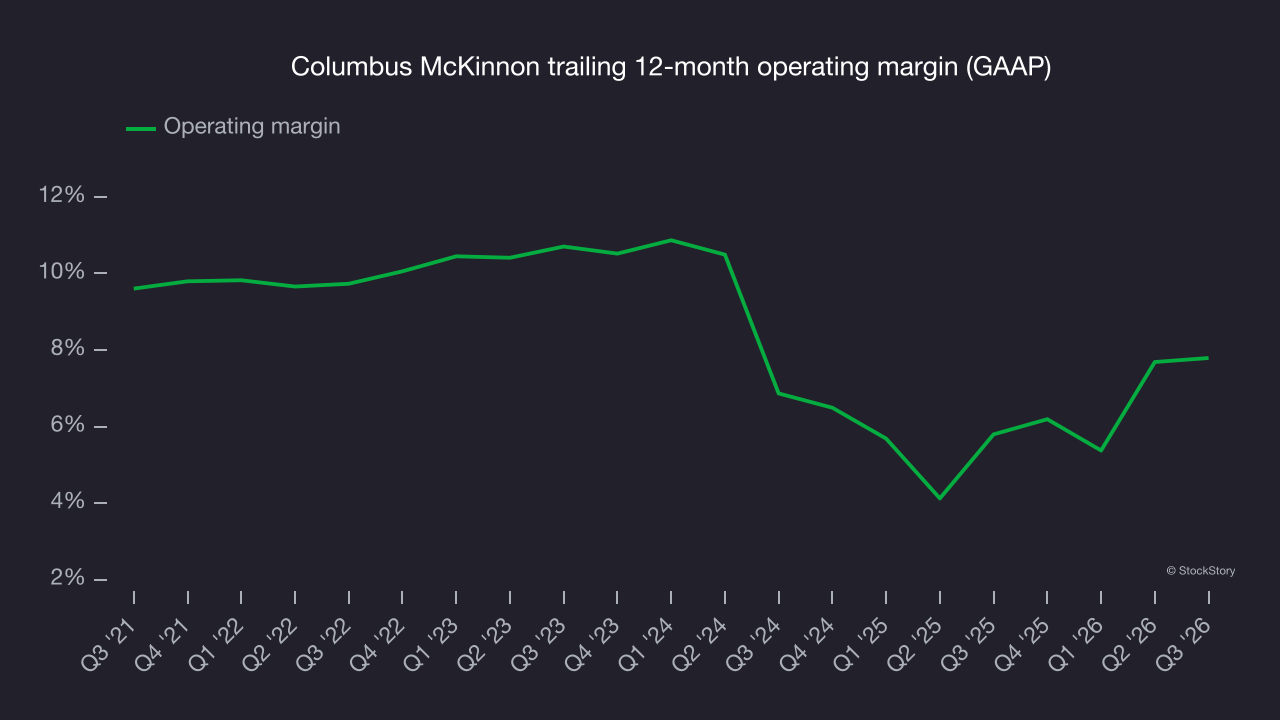
In Q3, Columbus McKinnon generated an operating margin of 6.5%, up 2 percentage points year on year. The increase was a positive sign, and operating margin rose more than gross margin, indicating greater efficiency in expenses such as marketing, R&D and administrative overhead.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Columbus McKinnon’s EPS grew at a weak 1.2% compounded annual growth rate over the last five years, lower than its 17.5% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
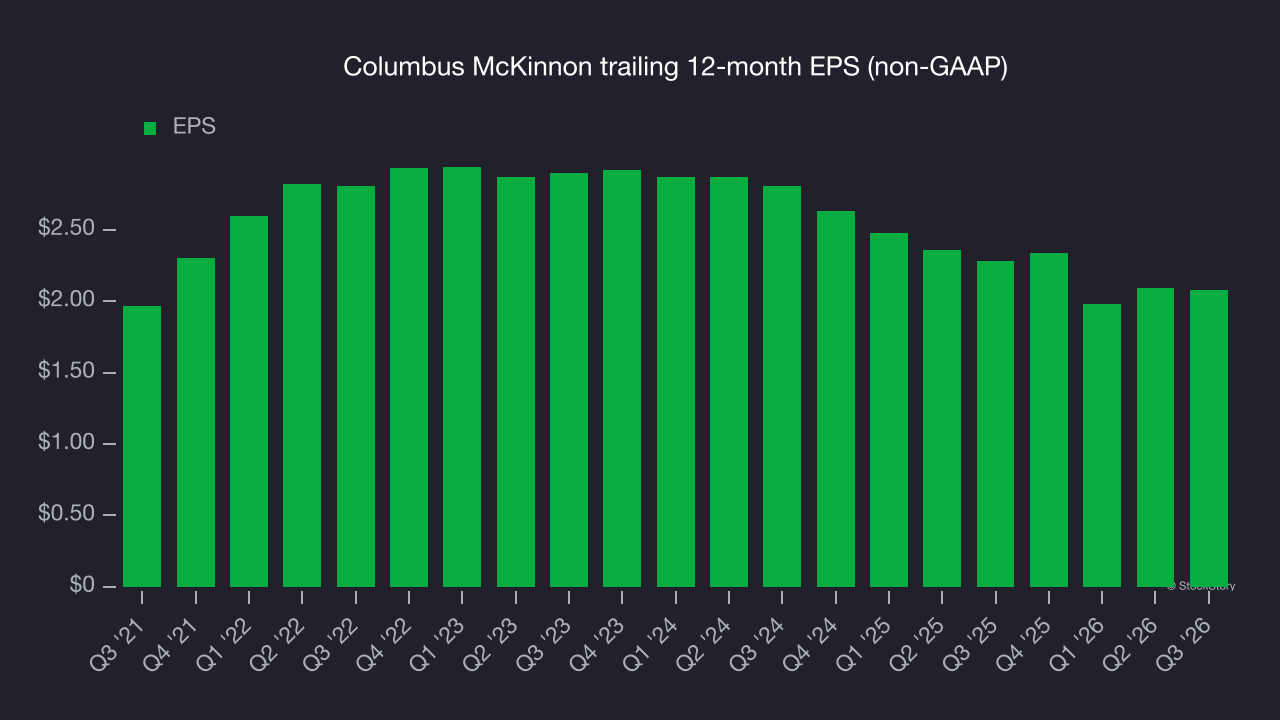
A closer look at Columbus McKinnon’s earnings helps explain the drivers of its performance. As mentioned earlier, Columbus McKinnon’s operating margin expanded this quarter but declined by 1.9 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but reveal less about a company’s fundamentals.
As with revenue, we analyze EPS over a shorter period to identify any changes in the business.
Columbus McKinnon’s annual EPS declines of 14% over the last two years show it has continued to underperform. These results were poor by any measure.
In Q3, Columbus McKinnon reported adjusted EPS of $0.61, down from $0.62 in the same quarter last year. Despite falling year on year, EPS came in well above analysts’ consensus estimates. Over the next 12 months, Wall Street expects Columbus McKinnon’s full-year EPS to grow 7.2% from $2.08 to $2.23, according to S&P.
Key takeaways from Columbus McKinnon’s Q3 results
Columbus McKinnon’s quarter had clear positives: EPS topped analysts’ consensus estimates, and EBITDA beat Wall Street’s consensus by a wide margin. Shares soared 11.6% to $17.59 immediately after the release.
Columbus McKinnon had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. An investment decision should also take into account its valuation and business quality. For more on Columbus McKinnon, read our full research report here (it’s free).