

Lowe's currently trades at $217.38 per share and has shown little upside over the past six months, posting a small loss of 2.8%. The stock also fell short of the S&P 500’s 5.3% gain during that period.
Is now the time to buy Lowe's, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Lowe's not exciting?
We’re passing on Lowe's for now. Here are three reasons we avoid LOW, plus one stock we’d rather own.
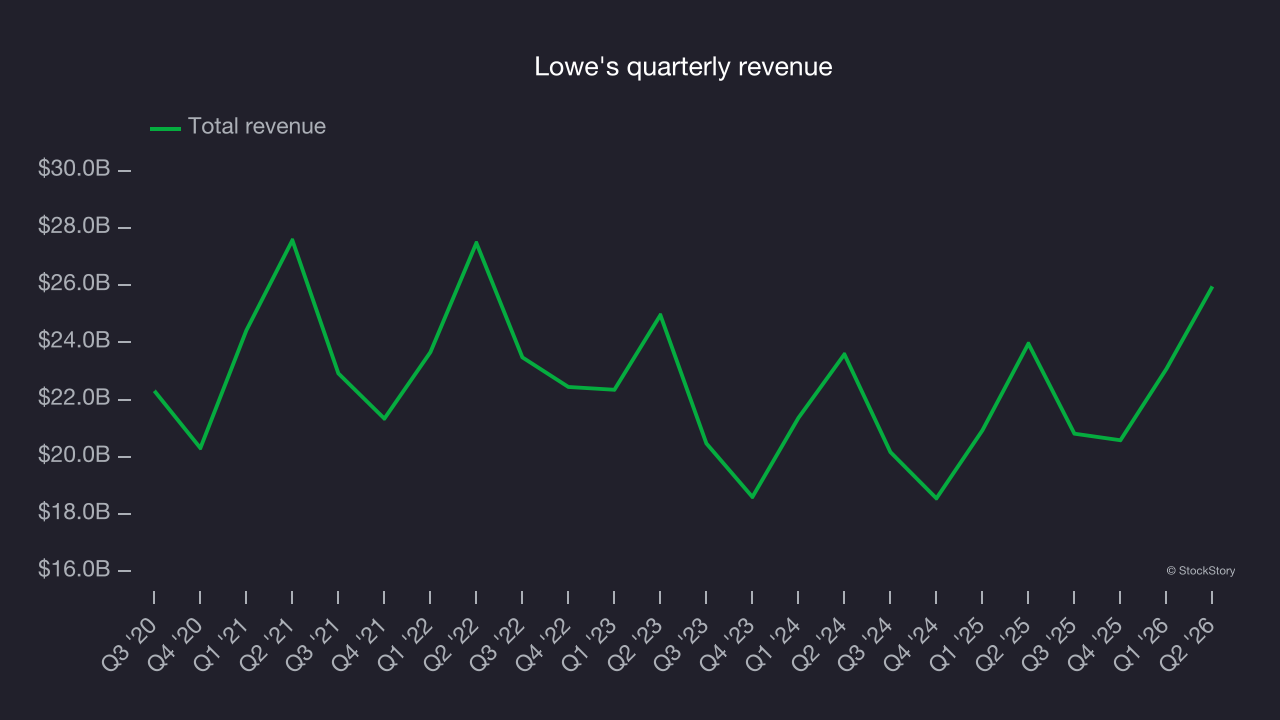
1. Revenue spiraling downwards
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Lowe's struggled to consistently generate demand over the last three years as its sales dropped at a 1% annual rate. This wasn’t a great result and signals it’s a lower quality business.
2. Flat same-store sales indicate weak demand
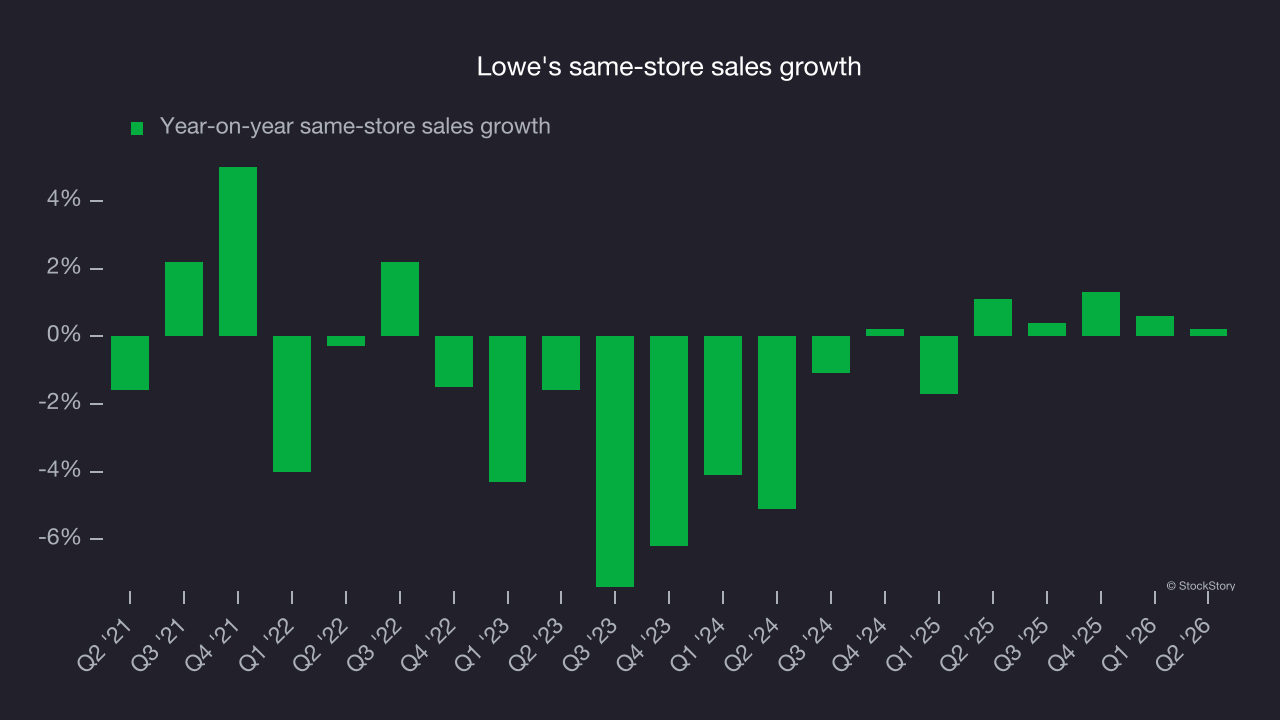
Same-store sales show the change in sales for a retailer’s e-commerce platform and brick-and-mortar shops that have existed for at least a year. This is a key performance indicator because it measures organic growth.
Lowe’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat.
3. Low gross margin reveals weak structural profitability
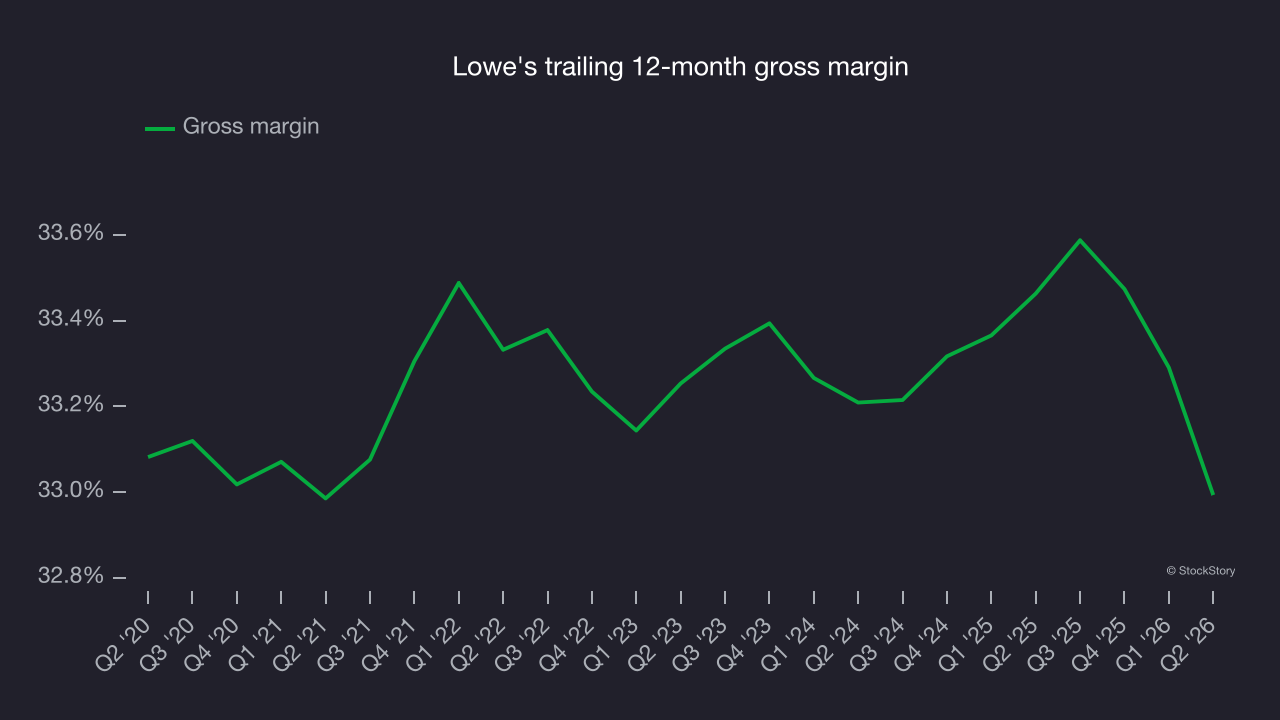
We prefer higher gross margins because they not only make it easier to generate more operating profits but also indicate product differentiation, negotiating leverage, and pricing power.
Lowe's has bad unit economics for a retailer, signaling it operates in a competitive market and lacks pricing power because its inventory is sold in many places. As you can see below, it averaged a 33.2% gross margin over the last two years. Said differently, Lowe's had to pay a chunky $66.78 to its suppliers for every $100 in revenue.
Final judgment
Lowe's isn’t a terrible business, but it doesn’t pass our quality test. With its shares underperforming the market lately, the stock trades at 16.7× forward P/E (or $217.38 per share). This valuation is reasonable, but the company’s shakier fundamentals present too much downside risk. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at one of our top software and edge computing picks.
High-quality stocks for all market conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.