

What a fantastic six months it’s been for Azenta. Shares of the company have skyrocketed 46.2%, hitting $35.57. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Azenta, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why do we think Azenta will underperform?
We’re glad investors have benefited from the price increase, but we’re cautious about Azenta. Here are three reasons why AZTA doesn’t excite us, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
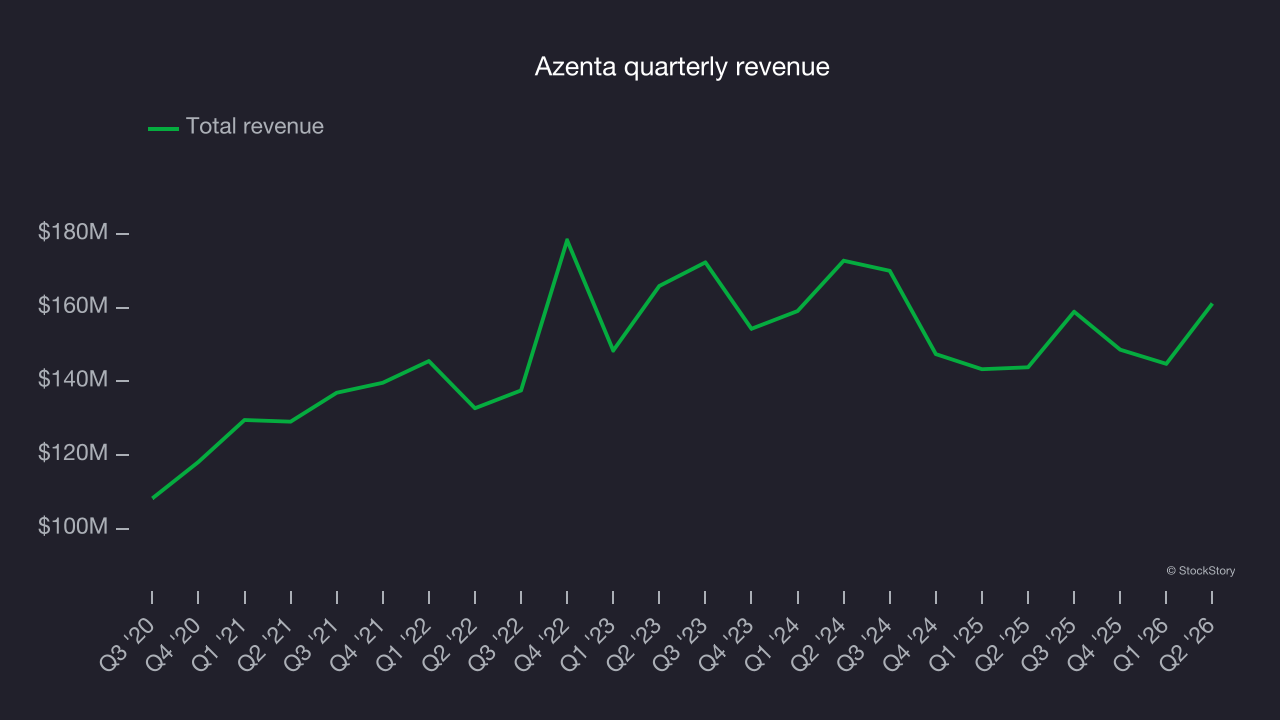
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, Azenta’s 4.8% annualized revenue growth over the last five years was mediocre. This was below our standard for the healthcare sector.
2. EPS trending down
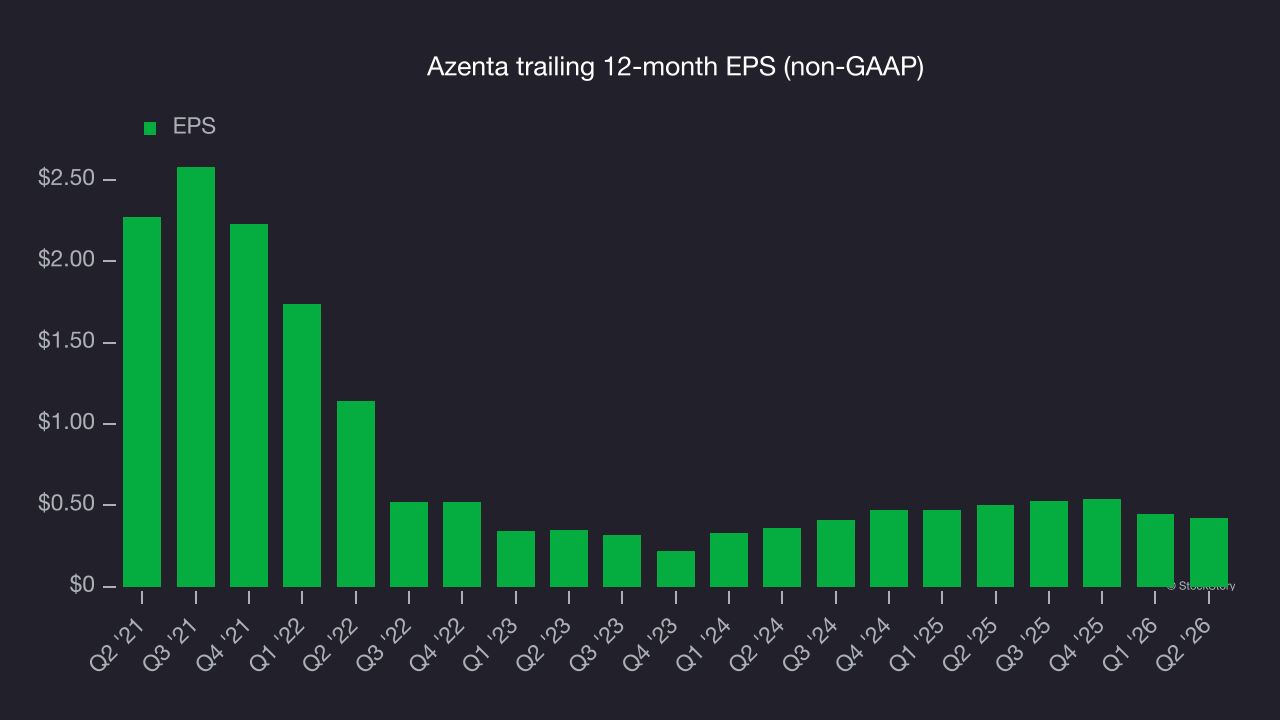
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Azenta, its EPS declined by 28.6% annually over the last five years while its revenue grew by 4.8%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Cash burn ignites concerns
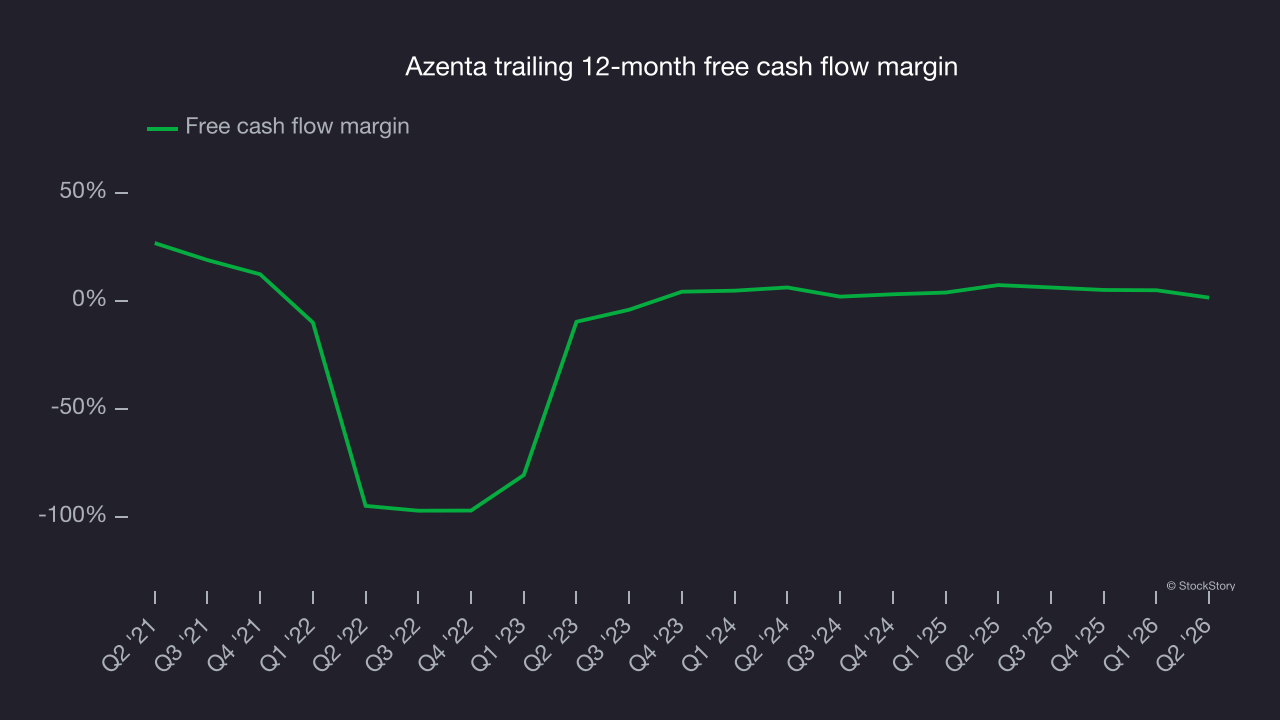
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
Azenta’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 16.1%, meaning it lit $16.10 of cash on fire for every $100 in revenue.
Final judgment
We see the value of companies making people healthier, but in the case of Azenta, we’re out. Following the recent surge, the stock trades at 82.8× forward P/E (or $35.57 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in - we think there are better opportunities elsewhere. We’d recommend looking at our favorite semiconductor picks and shovels play.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.