

Energizer has had an impressive run over the past six months as its shares have beaten the S&P 500 by 19.4%. The stock now trades at $24.10, marking a 24.6% gain. This run-up might have investors contemplating their next move.
Is there a buying opportunity in Energizer, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why do we think Energizer will underperform?
We’re happy investors have made money, but we don’t have much confidence in Energizer. Here are three reasons you should be careful with ENR, plus one stock we’d rather own.
1. Core business falling behind as organic growth slumps
When analyzing revenue growth, we care most about organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions, and divestitures as well as foreign currency fluctuations.
The demand for Energizer’s products has barely risen over the last eight quarters. On average, the company’s organic sales have been flat. 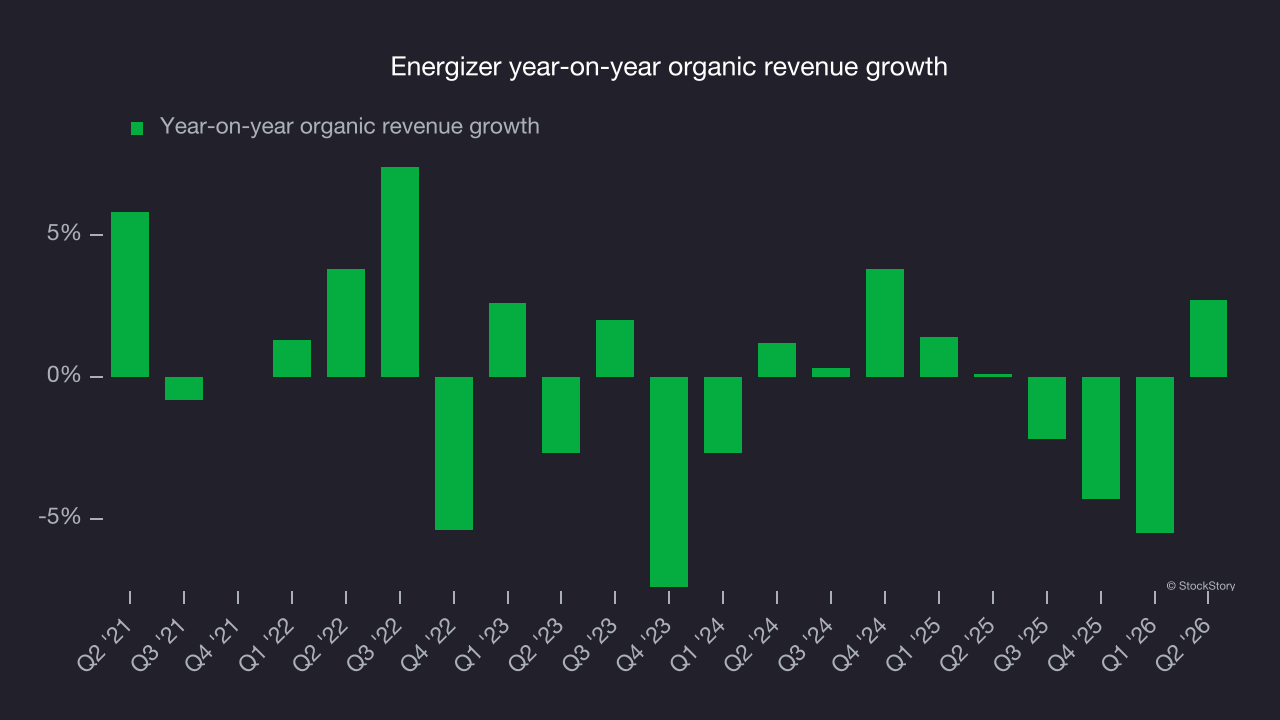
2. Projected revenue growth shows limited upside
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Energizer’s revenue to stall, according to S&P, a slight deceleration versus its flat result for the past three years. This projection is underwhelming and indicates its products will face some demand challenges.
3. High debt levels increase risk
Debt is a tool that can boost company returns but presents risks if used irresponsibly. As long-term investors, we aim to avoid companies taking excessive advantage of this instrument because it could lead to insolvency.
Energizer’s $3.33 billion of debt exceeds the $173.4 million of cash on its balance sheet. Furthermore, its 5× net-debt-to-EBITDA ratio (based on its EBITDA of $575.4 million over the last 12 months) shows the company is overleveraged.
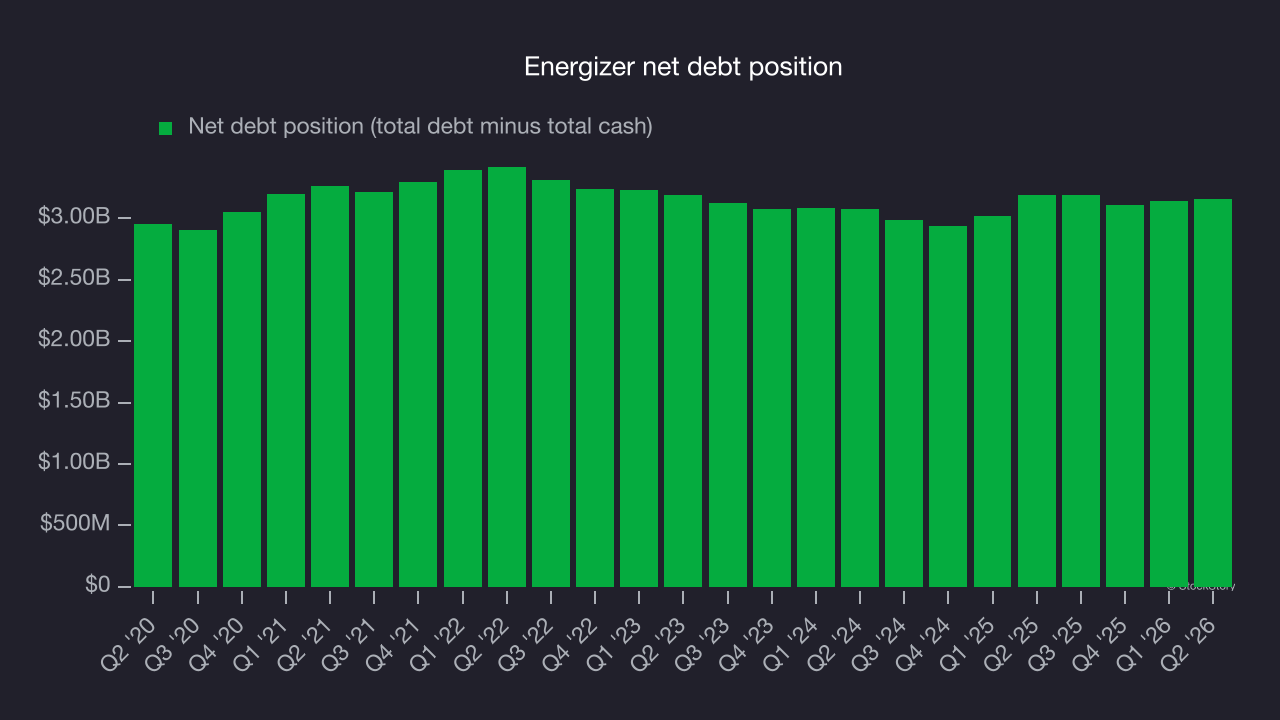
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Energizer could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Energizer can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final judgment
Energizer falls short of our quality standards. With its shares topping the market in recent months, the stock trades at 7× forward P/E (or $24.10 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are superior stocks to buy right now. Let us point you toward one of Charlie Munger’s all-time favorite businesses.
High-quality stocks for all market conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.