

Over the past six months, Hasbro has been a great trade, beating the S&P 500 by 21.5%. Its stock price has climbed to $119.15, representing a healthy 26.8% increase. This was partly thanks to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Hasbro, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why do we think Hasbro will underperform?
We’re happy investors have made money, but we’re passing on Hasbro for now. Here are three reasons you should be careful with HAS, plus one stock we’d rather own.
1. Revenue spiraling downwards
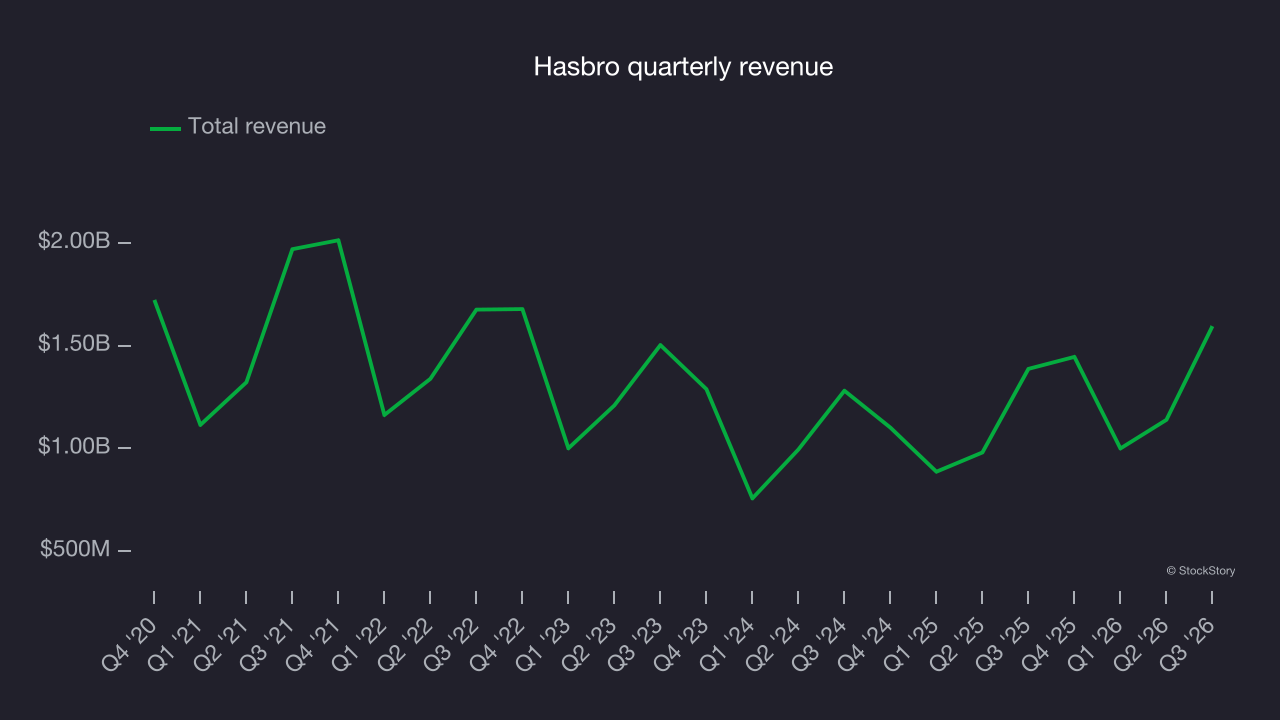
A company’s long-term performance is an indicator of its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Hasbro’s demand was weak over the last five years as its sales fell at a 3.3% annual rate. This wasn’t a great result and signals it’s a low quality business.
2. Weak operating margin could cause trouble
Operating margin is a key measure of profitability. Think of it as net income - the bottom line - excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
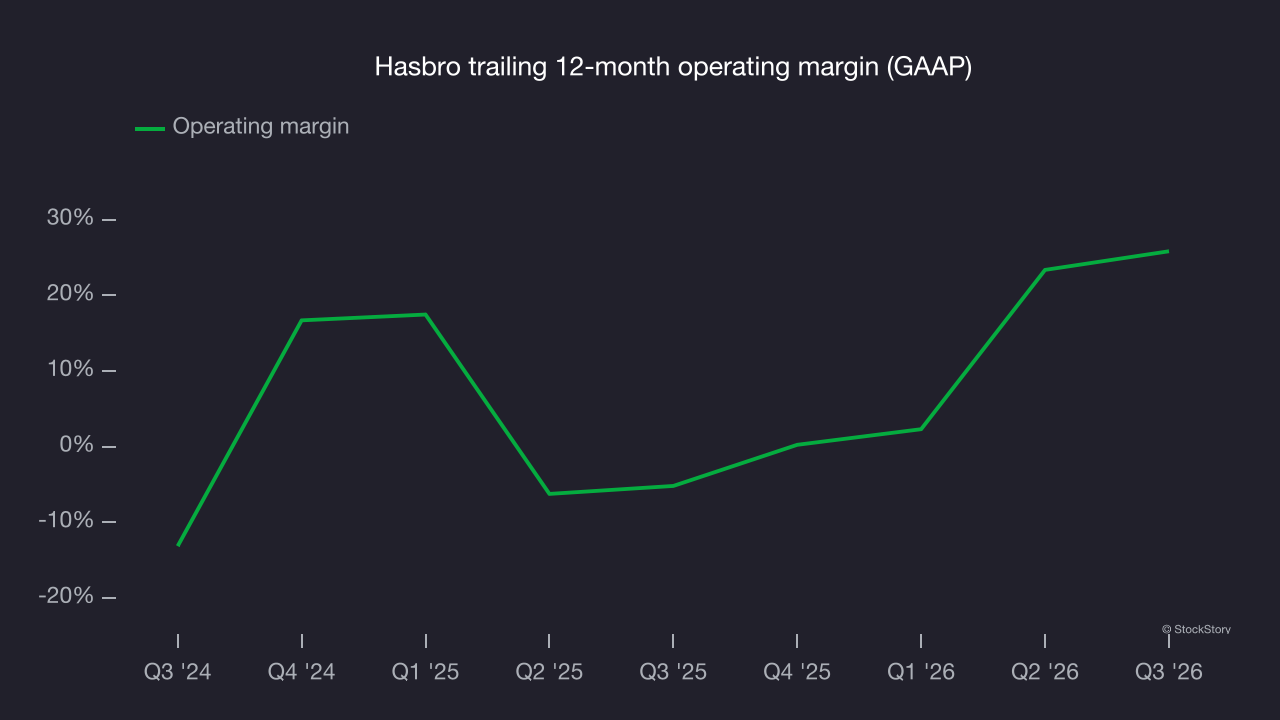
Hasbro’s operating margin has been trending up over the last 12 months and averaged 11.6% over the last two years. The company’s higher efficiency is a breath of fresh air, but its suboptimal cost structure means it still sports inadequate profitability for a consumer discretionary business.
3. EPS barely growing
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
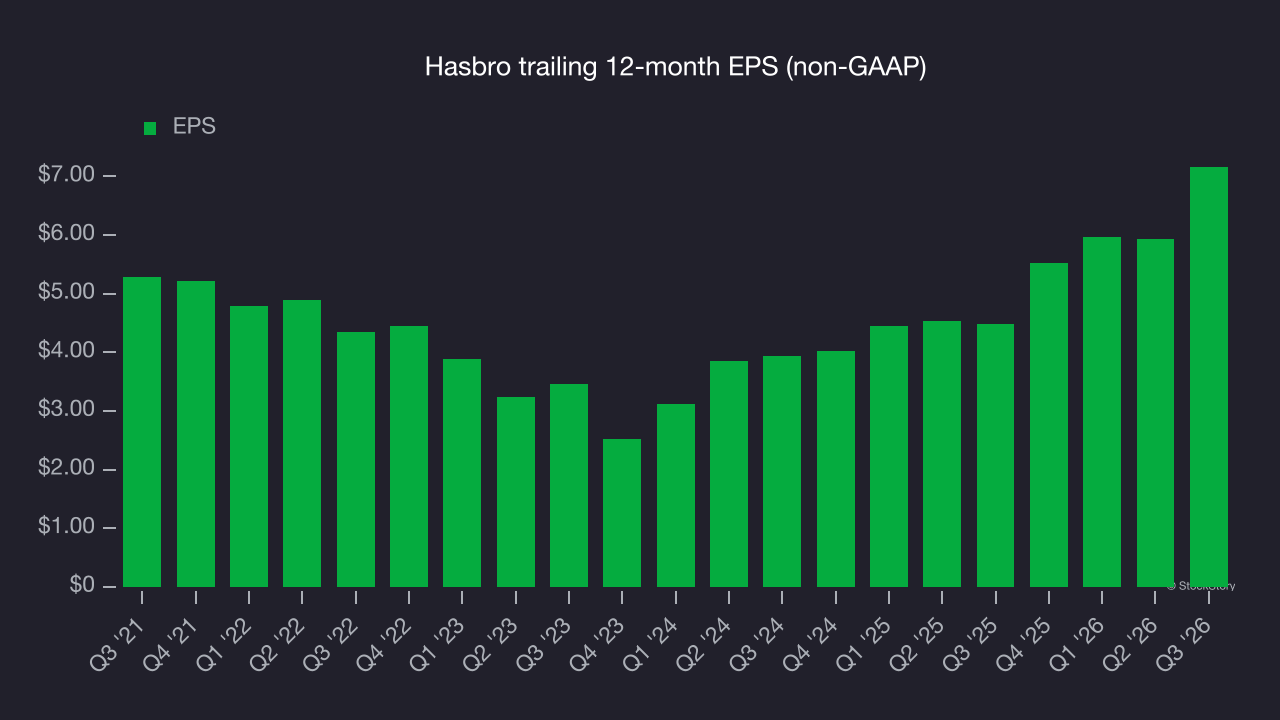
Hasbro’s EPS grew at 6.3% compounded annual growth rate over the last five years. On the bright side, this performance was better than its 3.3% annualized revenue declines and tells us management adapted its cost structure in response to a challenging demand environment.
Final judgment
We see the value of companies helping consumers, but in the case of Hasbro, we’re out. With its shares outperforming the market lately, the stock trades at 17.6× forward P/E (or $119.15 per share). This multiple tells us a lot of good news is priced in - we think other companies feature superior fundamentals at the moment. We’d recommend looking at the most entrenched endpoint security platform on the market.
Stocks we like more than Hasbro
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.