

Over the past six months, WD-40 has been a great trade, beating the S&P 500 by 6.1%. Its stock price has climbed to $227.54, representing a healthy 11.4% increase. This performance may have investors wondering how to approach the situation.
Is now still a good time to buy WDFC? Or are investors being too optimistic? Find out in our full research report, it’s free.
Why does WD-40 spark debate?
Short for “Water Displacement perfected on the 40th try”, WD-40 (NASDAQ:WDFC) is a renowned American consumer goods company known for its iconic and versatile spray, WD-40 Multi-Use Product.
Two things to like:
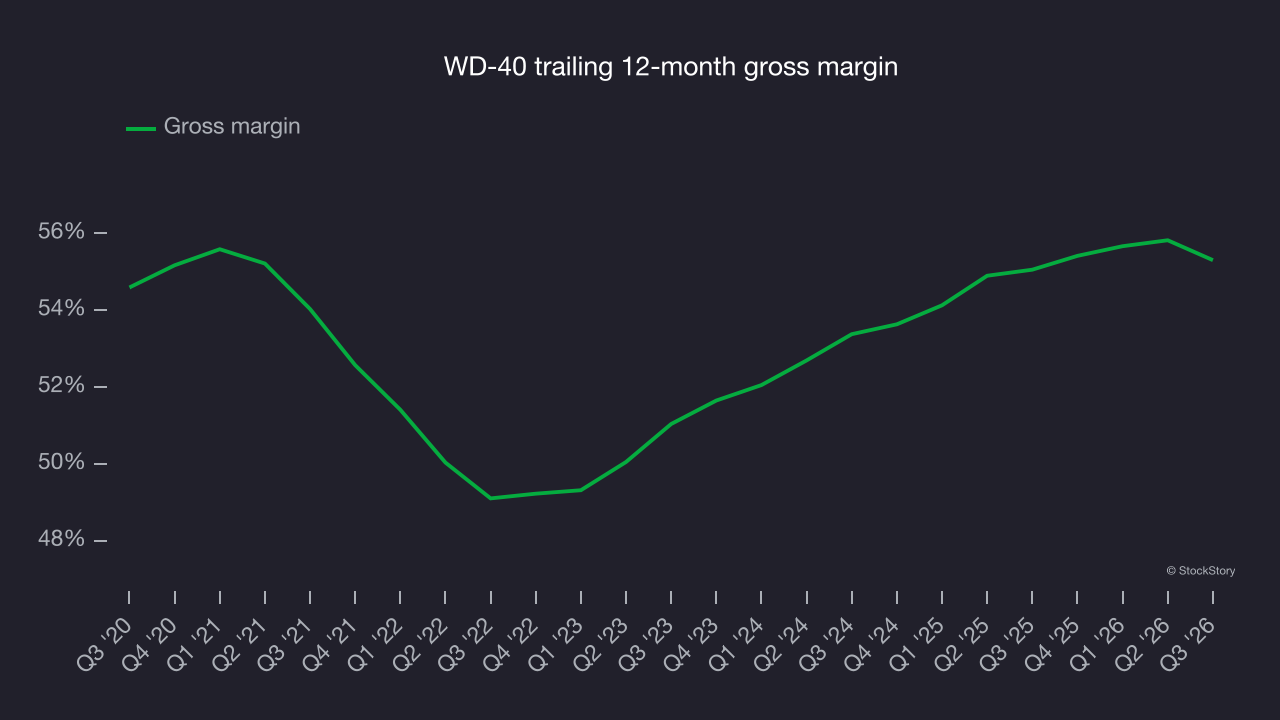
1. Elite gross margin powers best-in-class business model
All else equal, we prefer higher gross margins because they usually indicate that a company sells more differentiated products, has a stronger brand, and commands pricing power.
WD-40 has best-in-class unit economics for a consumer staples company, enabling it to invest in areas such as marketing and talent to grow its brand. As you can see below, it averaged an elite 55.2% gross margin over the last two years. That means for every $100 in revenue, only $44.81 went towards paying for raw materials, production of goods, transportation, and distribution.
2. Excellent free cash flow margin boosts reinvestment potential
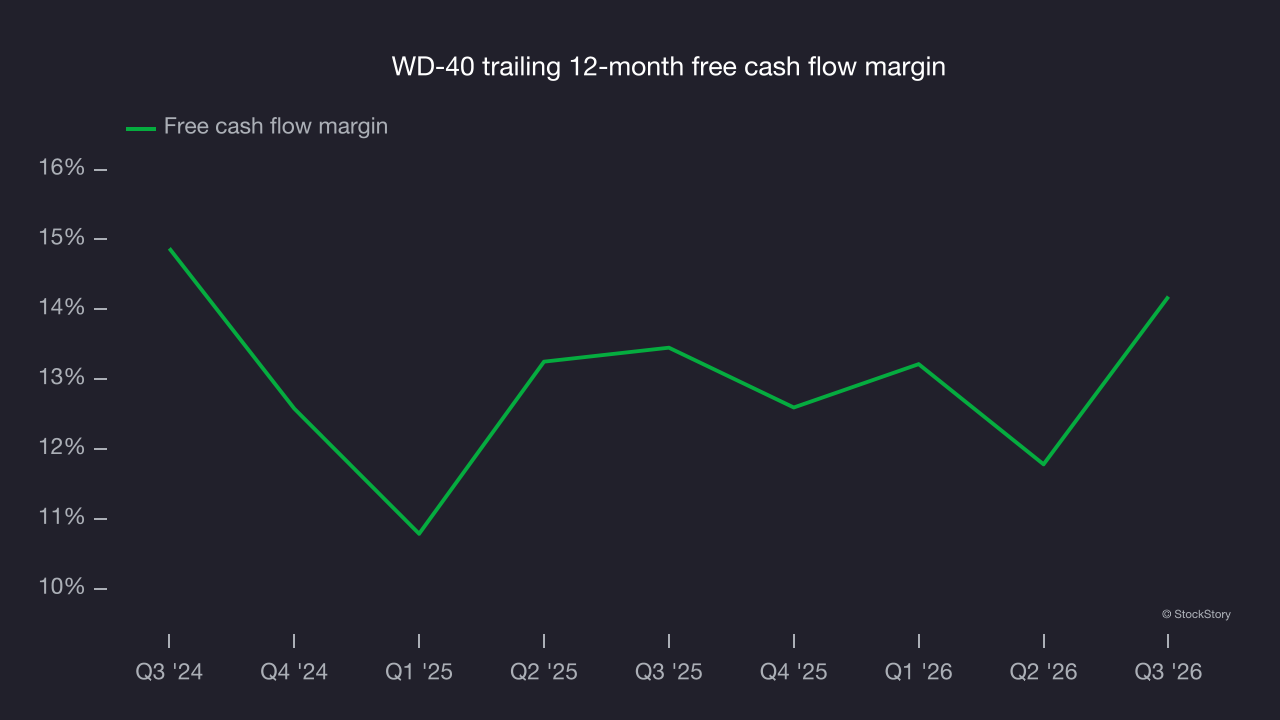
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
WD-40 has shown terrific cash profitability, driven by its lucrative business model that enables it to reinvest, return capital to investors, and stay ahead of the competition. The company’s free cash flow margin was among the best in the consumer staples sector, averaging 13.8% over the last two years.
One reason to be careful:
Fewer distribution channels limit its ceiling
With $688 million in revenue over the past 12 months, WD-40 is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the bright side, it can grow faster because it has a longer list of untapped store chains to sell into.
Final judgment
WD-40’s merits more than compensate for its flaws, and with its shares beating the market recently, the stock trades at 33.7× forward P/E (or $227.54 per share). Is now a good time to initiate a position? See for yourself in our comprehensive research report, it’s free.
High-quality stocks for all market conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.