

Health and wellness products company Herbalife (NYSE:HLF) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 6% year on year to $1.35 billion. Guidance for next quarter’s revenue was better than expected at $1.32 billion at the midpoint, 0.7% above analysts’ consensus estimates. Its non-GAAP profit of $0.64 per share was 3.7% above analysts’ consensus estimates.
For more on Herbalife, read our free full research report.
Herbalife (HLF) Q3 2026 highlights:
- Revenue $1.35 billion vs S&P analysts’ consensus estimates of $1.31 billion (6% year-on-year growth, 3.2% beat)
- Adjusted EPS $0.64 vs S&P analysts’ consensus estimates of $0.62 (3.7% beat)
- Adjusted EBITDA $182.4 million vs analysts’ consensus estimates of $169 million (13.5% margin, 7.9% beat)
- Revenue guidance $1.32 billion at the midpoint for Q4 2026, roughly in line with what analysts were expecting
- EBITDA guidance $680 million at the midpoint for the full year, above analysts’ consensus estimates of $672.5 million
- Operating margin 10.3%, in line with the same quarter last year
- Free cash flow margin 9.8%, similar to the same quarter last year
- Market capitalization $1.37 billion
“We delivered a fifth consecutive quarter of year-over-year net sales growth, and we continue to expect net sales growth for the remainder of the year,” said John DeSimone, Interim CEO. “Our priorities are clear: disciplined execution, profitable growth, and a focused roadmap for our business opportunity and digital platforms with measurable success metrics.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years.
With $5.28 billion in revenue over the past 12 months, Herbalife carries some recognizable products but is a mid-sized consumer staples company. Its size could bring disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale.
Herbalife grew its revenue at a sluggish 1.6% compounded annual growth rate over the last three years. This shows it failed to generate meaningful demand.
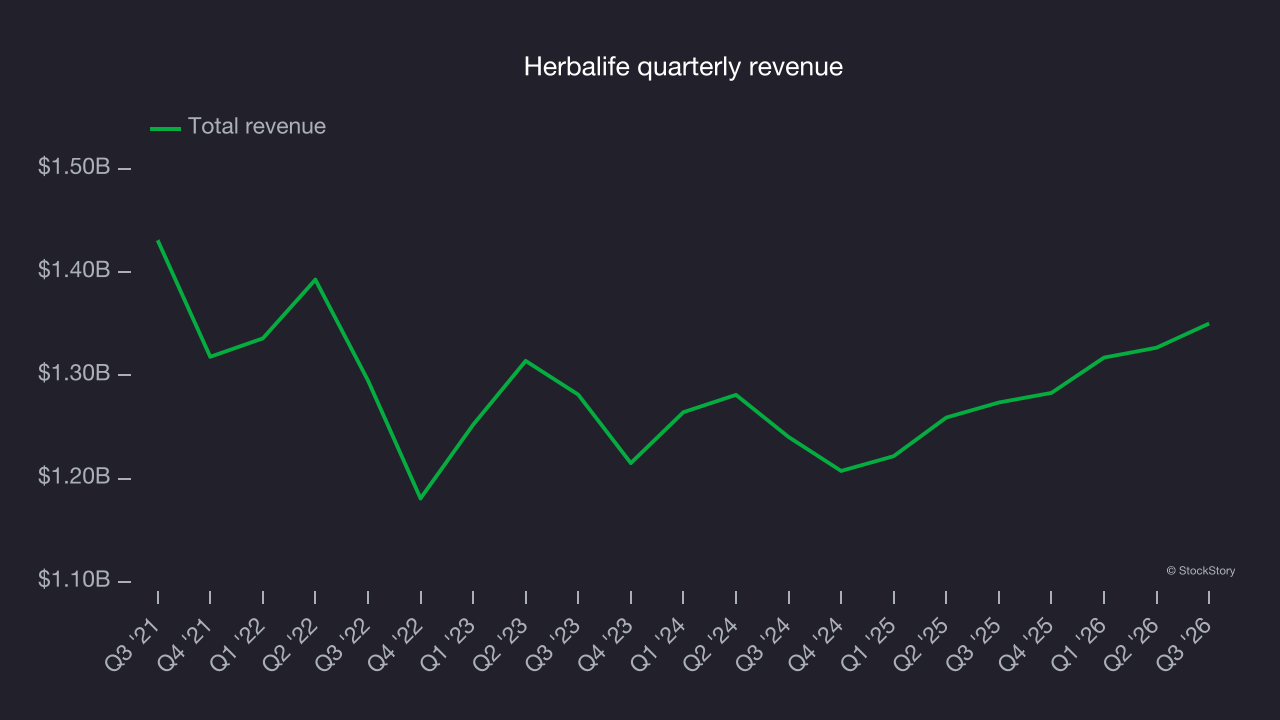
This quarter, Herbalife reported year-on-year revenue growth of 6%, and its $1.35 billion of revenue exceeded Wall Street’s consensus estimates by 3.2%. Company management is currently guiding for a 2.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 1.3% over the next 12 months, according to S&P, similar to its three-year rate. This projection is underwhelming and suggests its newer products will not accelerate its top-line performance yet.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s telling because it accounts for all operating and capital expenses, making it difficult to manipulate.
Herbalife has shown decent cash profitability, giving it some flexibility to reinvest or return capital to investors. The company’s free cash flow margin averaged 5.4% over the last two years, slightly better than the broader consumer staples sector.
Herbalife’s margin expanded by 2 percentage points over the last year. This points to improvement, and the company became less capital-intensive as its free cash flow profitability rose while its operating profitability was flat.
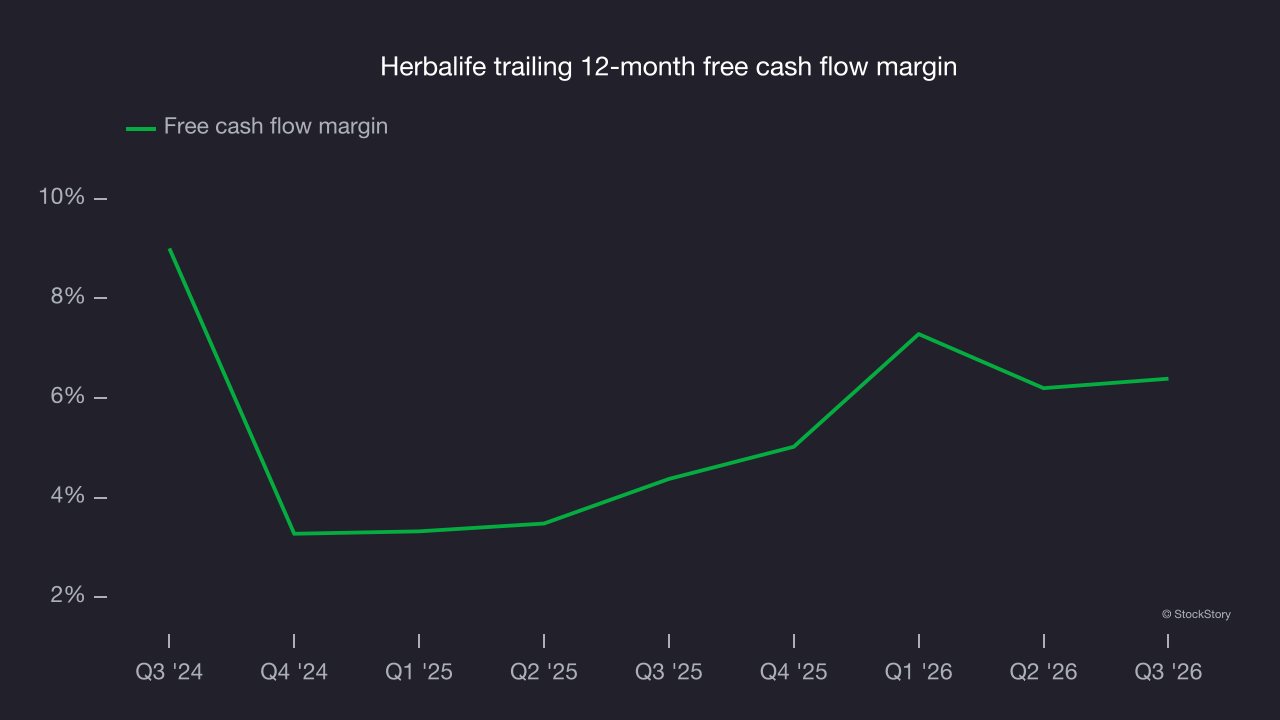
Herbalife’s free cash flow totaled $132.8 million in Q3, equivalent to a 9.8% margin. This cash profitability was in line with the comparable period last year and above its two-year average.
Key takeaways from Herbalife’s Q3 results
Herbalife’s Q3 had some key positives: EBITDA came in well above analysts’ consensus estimates, and revenue also topped Wall Street’s consensus. But next-quarter EBITDA guidance missed expectations, and gross margin fell slightly short of consensus, making the results mixed overall. Shares surged 5.1% to $13.97 immediately after the report.
Herbalife had a solid quarterly earnings result, but that alone doesn’t determine whether the stock is a good investment. The latest quarter matters, but longer-term fundamentals and valuation matter much more when deciding whether to buy. For more on Herbalife, read our full research report here (it’s free).