

Consumer products giant Clorox (NYSE:CLX) reported revenue ahead of Wall Street’s expectations in calendar Q3 2026 (fiscal Q1 2027), with revenue up 33.3% year on year to $1.91 billion. Its non-GAAP profit of $1.55 per share was 44.6% above analysts’ consensus estimates.
For more on Clorox, read our free full research report.
Clorox (CLX) Q3 CY2026 highlights:
- Revenue $1.91 billion vs S&P analysts’ consensus estimates of $1.88 billion (33.3% year-on-year growth, 1.5% beat)
- Adjusted EPS $1.55 vs S&P analysts’ consensus estimates of $1.07 (44.6% beat)
- Adjusted EPS guidance Management reiterated its full-year adjusted EPS guidance of $5.85 at the midpoint
- Organic revenue rose 18% year on year (beat)
- Market capitalization $10.64 billion
"We entered this fiscal year focused on steadily improving performance while navigating continued input cost pressures. We made good progress in the first quarter, delivering better-than-expected results through strong execution and timing benefits," said Chair and CEO Linda Rendle. "The cost environment has become more challenging, with higher inflationary pressures reflected in our updated outlook. We have plans in place to mitigate these pressures while continuing to invest behind our brands. Importantly, we continue to make progress against our strategic priorities, including improving market share and integrating GOJO to unlock the full potential of Clorox Purell ProCare. We remain confident in the strength of our long-term trajectory and our ability to create sustainable value for shareholders."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term.
With $7.2 billion in revenue over the past 12 months, Clorox is one of the larger consumer staples companies and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because it’s harder to find incremental growth when its existing brands have penetrated most of the market. To expand meaningfully, Clorox likely needs to tweak its prices, innovate with new products or enter new markets.
Clorox struggled to increase demand as its $7.2 billion in revenue for the trailing 12 months was close to its revenue three years ago. This shows demand was soft.
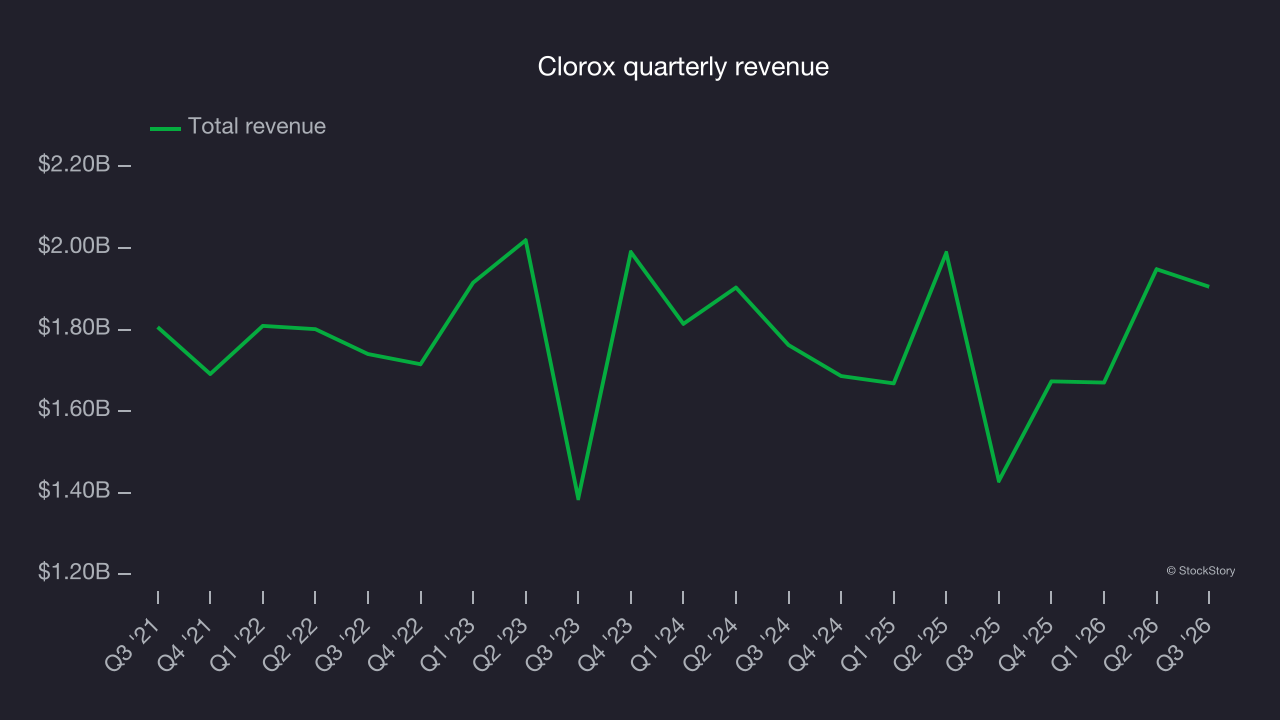
This quarter, Clorox reported strong year-on-year revenue growth of 33.3%, and its $1.91 billion in revenue exceeded Wall Street’s consensus estimates by 1.5%.
Looking ahead, sell-side analysts expect revenue to grow 6.6% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is above average for the sector and indicates its newer products will catalyze better top-line performance.
Free cash flow
Free cash flow matters because accounting profits alone cannot pay the bills.
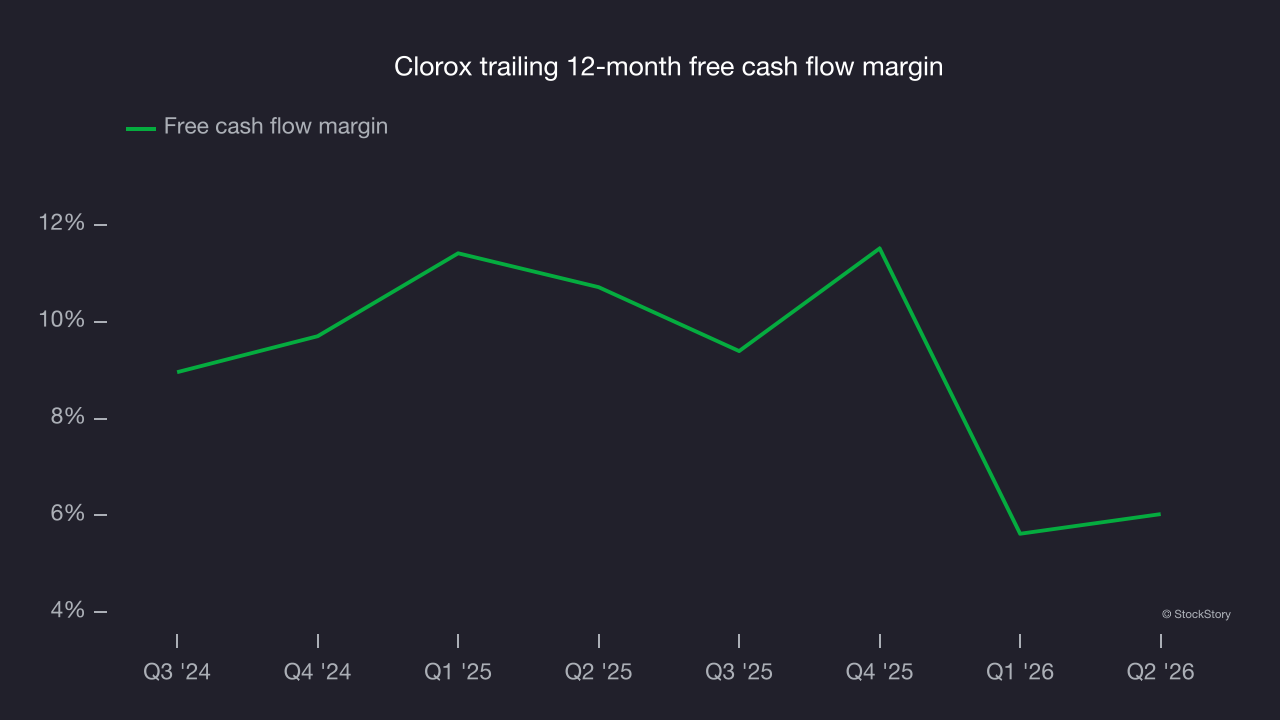
Clorox has shown impressive cash profitability, driven by its attractive business model that gives it the option to reinvest or return capital to investors. The company’s free cash flow margin averaged 8.2% over the last two years, better than the broader consumer staples sector.
Key takeaways from Clorox’s Q3 results
Clorox’s EPS beat and above-consensus full-year EPS guidance made for a decent quarter, with some key metrics topping expectations. Shares rose 2.1% to $91.88 immediately after the results.
Clorox had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. Let’s look at the investment case. If you’re making that decision, you should consider the bigger picture of valuation, business quality and the latest earnings. Read our full research report here (it’s free).