

Aerospace and defense company BWX (NYSE:BWXT) missed Wall Street’s revenue expectations in Q3 2026, but revenue rose 10% year on year to $953 million. On the other hand, the company’s outlook for the full year was close to analysts’ consensus estimates, with revenue guided to $3.8 billion at the midpoint. Its non-GAAP profit of $1.26 per share was 5.7% above analysts’ consensus estimates.
For more on BWX, read our free full research report.
BWX (BWXT) Q3 2026 highlights:
- Revenue $953 million vs S&P analysts’ consensus estimates of $973.1 million (10% year-on-year growth, 2.1% miss)
- Adjusted EPS $1.26 vs S&P analysts’ consensus estimates of $1.19 (5.7% beat)
- Adjusted EBITDA $179.7 million vs analysts’ consensus estimates of $167.5 million (18.9% margin, 7.3% beat)
- Adjusted EPS guidance Management reiterated its full-year adjusted EPS guidance of $4.74 at the midpoint
- EBITDA guidance $667 million at the midpoint for the full year, above analysts’ consensus estimates of $660.3 million
- Operating margin 13.9%, in line with the same quarter last year
- Free cash flow margin 15.8%, up from 11% in the same quarter last year
- Backlog $8.56 billion at quarter end, up 15.6% year on year
- Market capitalization $11.97 billion
"As we look to the remainder of 2026 and into 2027, we expect continued demand momentum for nuclear solutions and increased conversion of our robust bid pipeline into firm awards," said Geveden. "Our preliminary outlook for 2027 points to another year of solid earnings and cash flow growth, which combined with robust demand, a strong balance sheet, and a disciplined capital allocation strategy, positions us well to continue compounding growth and shareholder value in 2027 and beyond."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. BWX’s 11.5% annualized revenue growth over the last five years was impressive. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
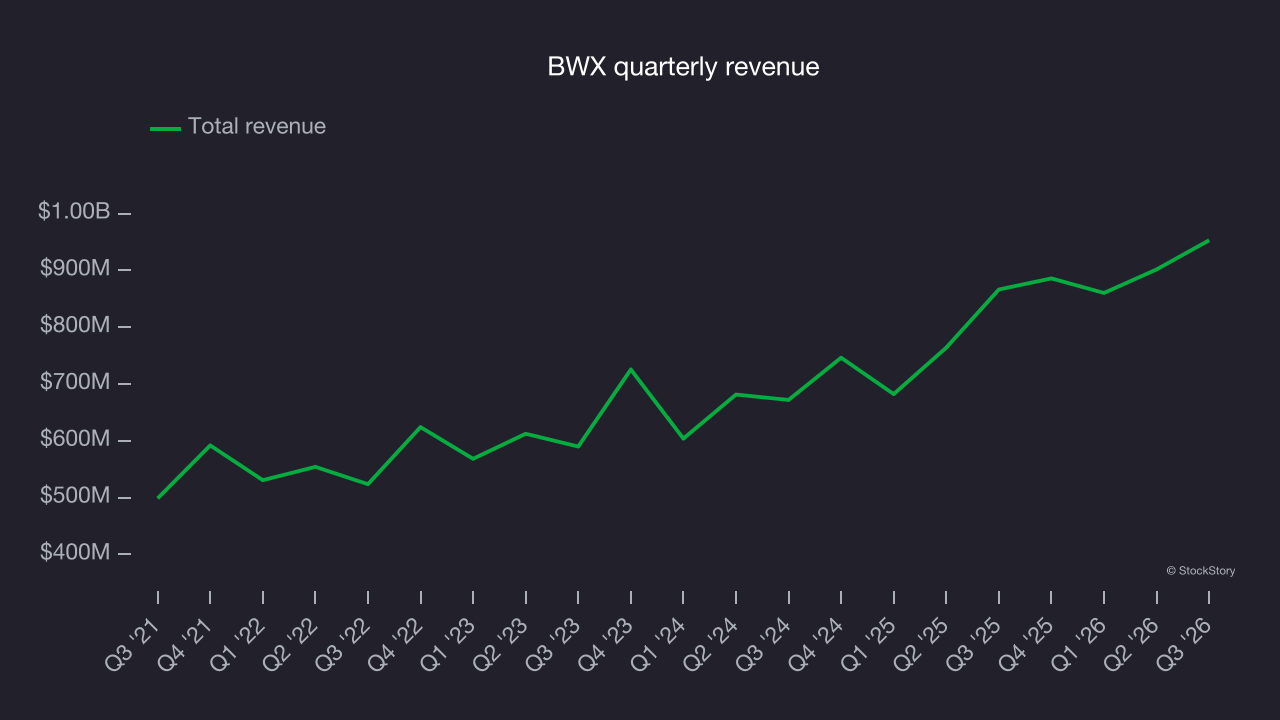
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. BWX’s annualized revenue growth of 15.8% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 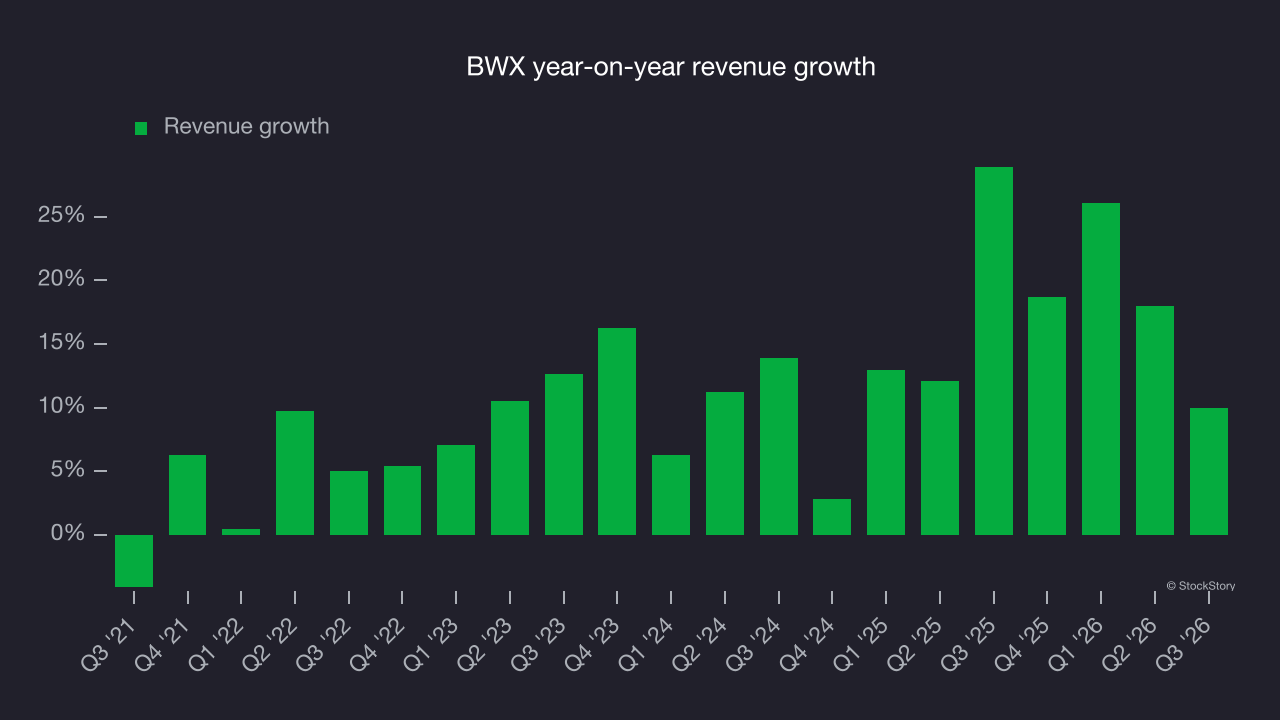
BWX also breaks out the revenue for its most important segments, Government Operations and Commercial Operations, which are 67.1% and 33% of revenue. Over the last two years, BWX’s Government Operations revenue (public sector revenue) averaged 109% year-on-year growth while its Commercial Operations revenue (private sector revenue) averaged 61.5% growth. 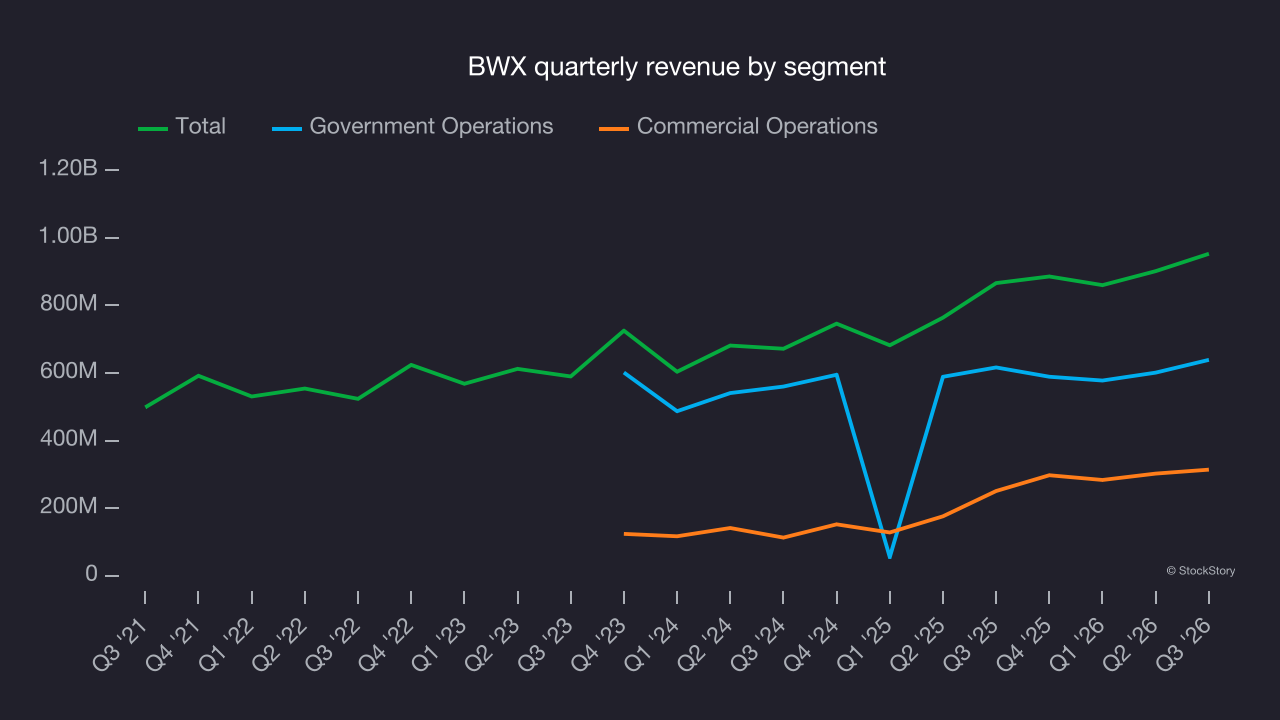
This quarter, BWX’s revenue grew by 10% year on year to $953 million but fell short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 14.4% over the next 12 months, according to S&P, similar to its two-year rate. Despite the slowdown, this projected growth is strong and implies the market is forecasting success for its products and services.
Operating margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products and, most importantly, keeping them relevant through research and development.
BWX has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 14.1%.
Looking at the trend in its profitability, BWX’s operating margin decreased by 3.5 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
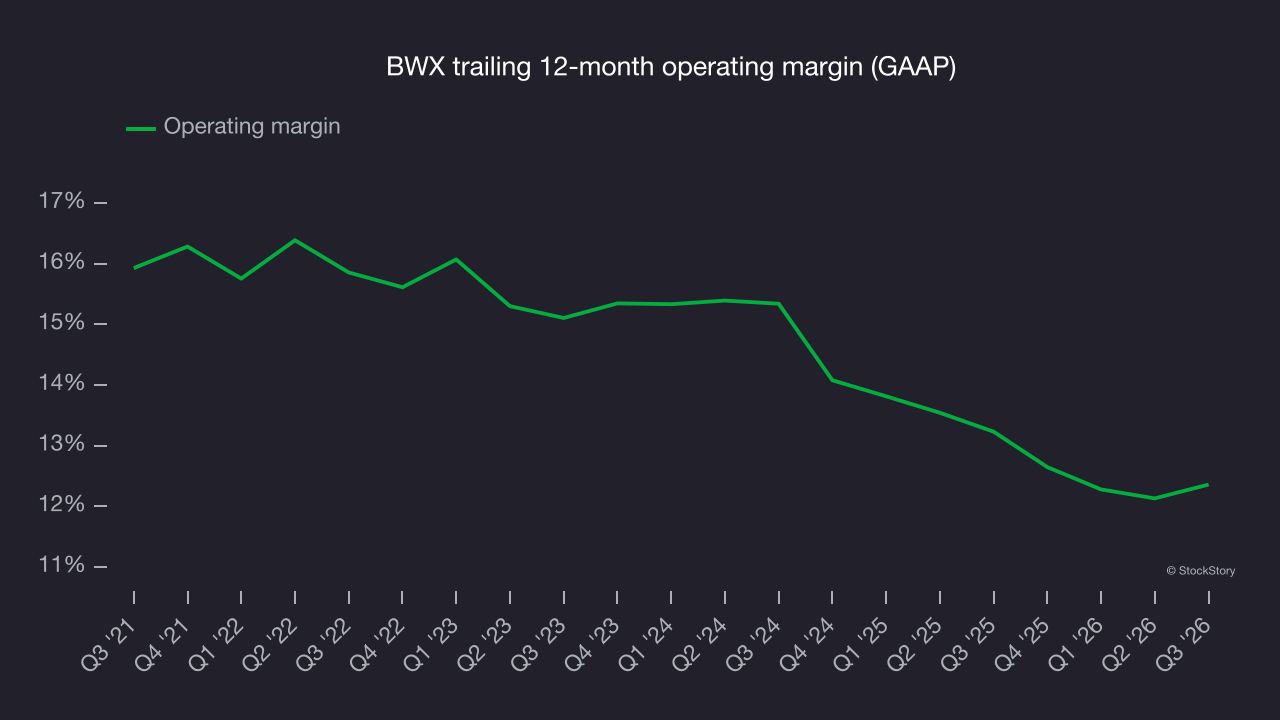
This quarter, BWX generated an operating margin of 13.9%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth – for example, a company could inflate its revenue through excessive spending on advertising and promotions.
BWX’s solid 10.8% annual EPS growth over the last five years aligns with its revenue performance. This tells us it maintained its per-share profitability as it expanded.
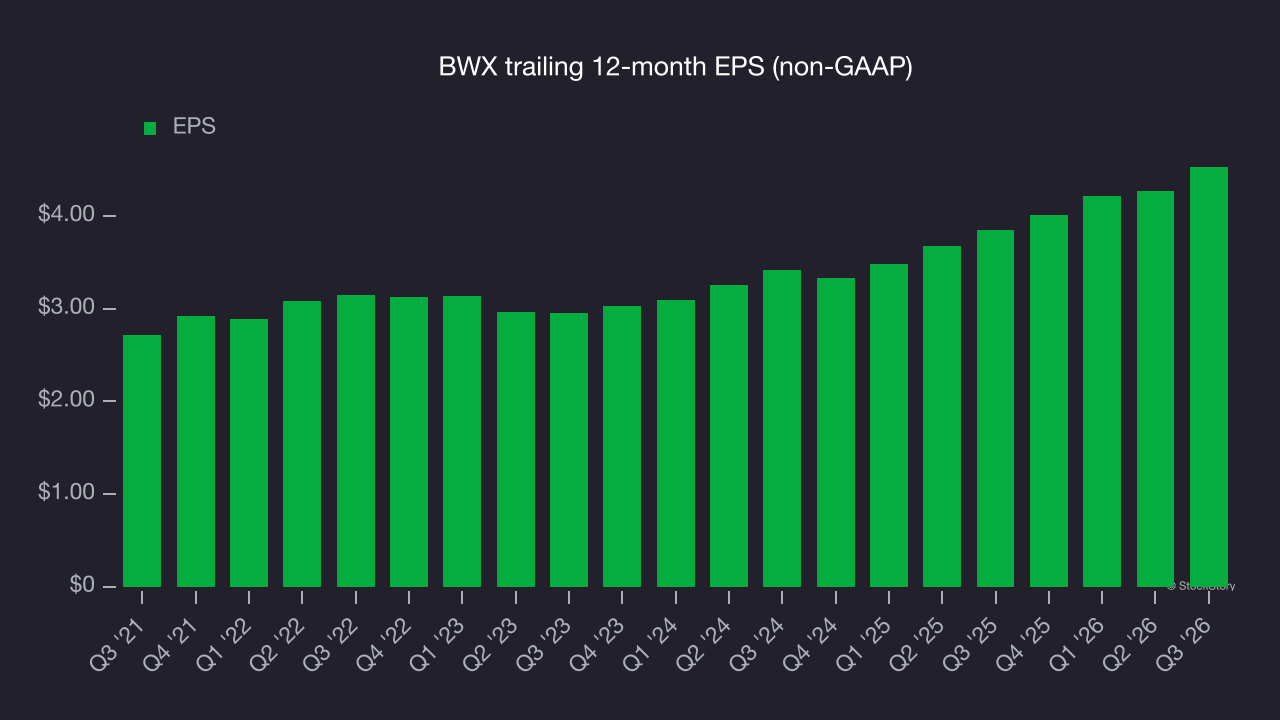
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
For BWX, its two-year annual EPS growth of 15.1% was higher than its five-year trend. That acceleration is a positive sign, especially given the already high base.
In Q3, BWX reported adjusted EPS of $1.26, up from $1 in the same quarter last year. The result beat analysts’ consensus estimates by 5.7%. Over the next 12 months, Wall Street expects BWX’s full-year EPS to grow 14.2% from $4.53 to $5.17, according to S&P.
Key takeaways from BWX’s Q3 results
BWX’s Q3 results were mixed: EBITDA beat analysts’ consensus estimates, and full-year EBITDA guidance came in slightly above Wall Street’s consensus. But revenue missed expectations, and full-year revenue guidance was in line with consensus. Investors were likely hoping for more, as shares fell 3.2% to $126.32 immediately after the report.
The latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. For more on these factors, read the full research report here (it’s free).