

Transmission provider Allison Transmission (NYSE:ALSN) beat Wall Street’s revenue expectations in Q3 2026, with revenue up 121% year on year to $1.53 billion. The company’s full-year revenue guidance of $6.03 billion at the midpoint came in 1.5% above analysts’ consensus estimates. Its GAAP profit of $2.30 per share was in line with analysts’ consensus estimates.
For more on Allison Transmission, read our free full research report.
Allison Transmission (ALSN) Q3 2026 highlights:
- Revenue $1.53 billion vs S&P analysts’ consensus estimates of $1.47 billion (121% year-on-year growth, 4.2% beat)
- EPS (GAAP) $2.30 vs analysts’ consensus estimates of $2.31 (in line)
- Adjusted EBITDA $400 million vs analysts’ consensus estimates of $385.1 million (26.1% margin, 3.9% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $6.03 billion at the midpoint from $5.9 billion, a 2.1% increase
- EBITDA guidance $1.56 billion at the midpoint for the full year, above analysts’ consensus estimates of $1.53 billion
- Operating margin 19.8%, down from 29.4% in the same quarter last year
- Free cash flow margin 18.1%, down from 26.6% in the same quarter last year
- Market capitalization $8.92 billion
David S. Graziosi, chair, president and chief executive officer of Allison, commented, "Allison's third quarter results reflect continued strength across the majority of our end markets, supported by disciplined execution that maximized the benefits of higher volumes. Within the Allison Transmission business unit, demand accelerated for medium-duty and Class 8 vocational trucks, driving record quarterly revenue of $462 million in the North America On-Highway end market. Within the Allison Off-Highway business unit, momentum in the Mining end market remained robust, while the Construction & Material Handling end market delivered year over year growth across all regions, exceeding our expectations entering 2026. As anticipated, third quarter performance reflects customary seasonality for the business unit, including the impact of European holidays, and represents the softest quarter of the year. Conversely, demand within the Industrial and Agriculture end markets remained subdued, as ongoing geopolitical developments continue to temper customer purchasing activity."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a weak business can perform well for one or two quarters, but a high-quality one grows for years. Over the last five years, Allison Transmission grew its revenue at a strong 18% compounded annual growth rate. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
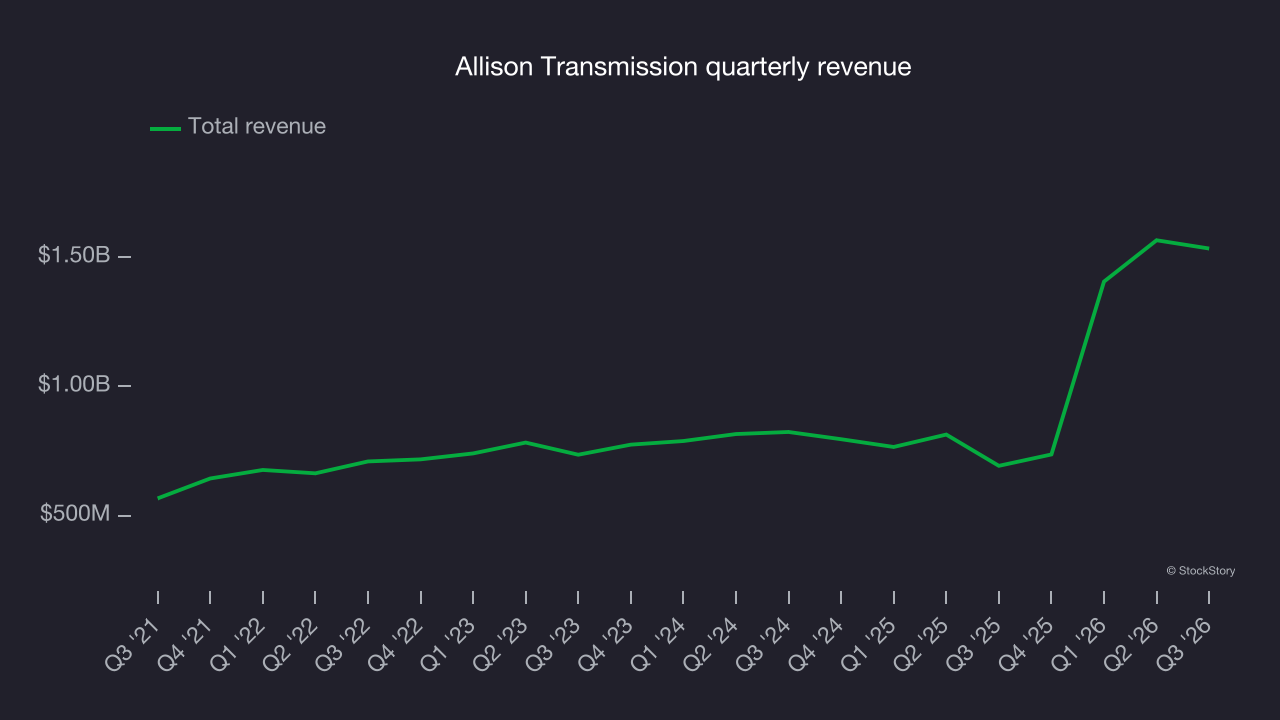
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Allison Transmission’s annualized revenue growth of 27.9% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated.
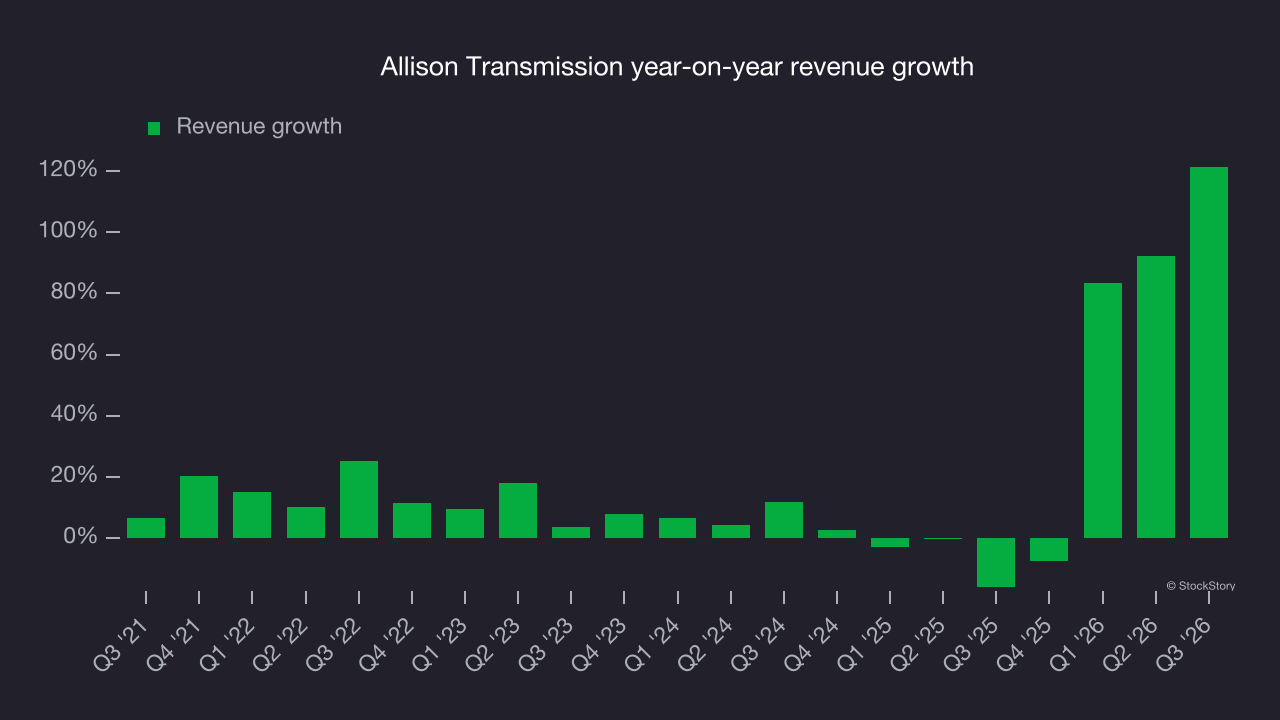
This quarter, Allison Transmission reported strong year-on-year revenue growth of 121%, and its $1.53 billion of revenue beat Wall Street’s consensus estimates by 4.2%.
Looking ahead, sell-side analysts expect revenue to grow 13.6% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is noteworthy and suggests the market sees success for its products and services.
Operating margin
Allison Transmission has performed well over the last five years. It demonstrated high profitability for an industrials business, with an average operating margin of 26.4%. This result is unsurprising given its favorable gross margin baseline.
Analyzing the trend in its profitability, Allison Transmission’s operating margin decreased by 10.2 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
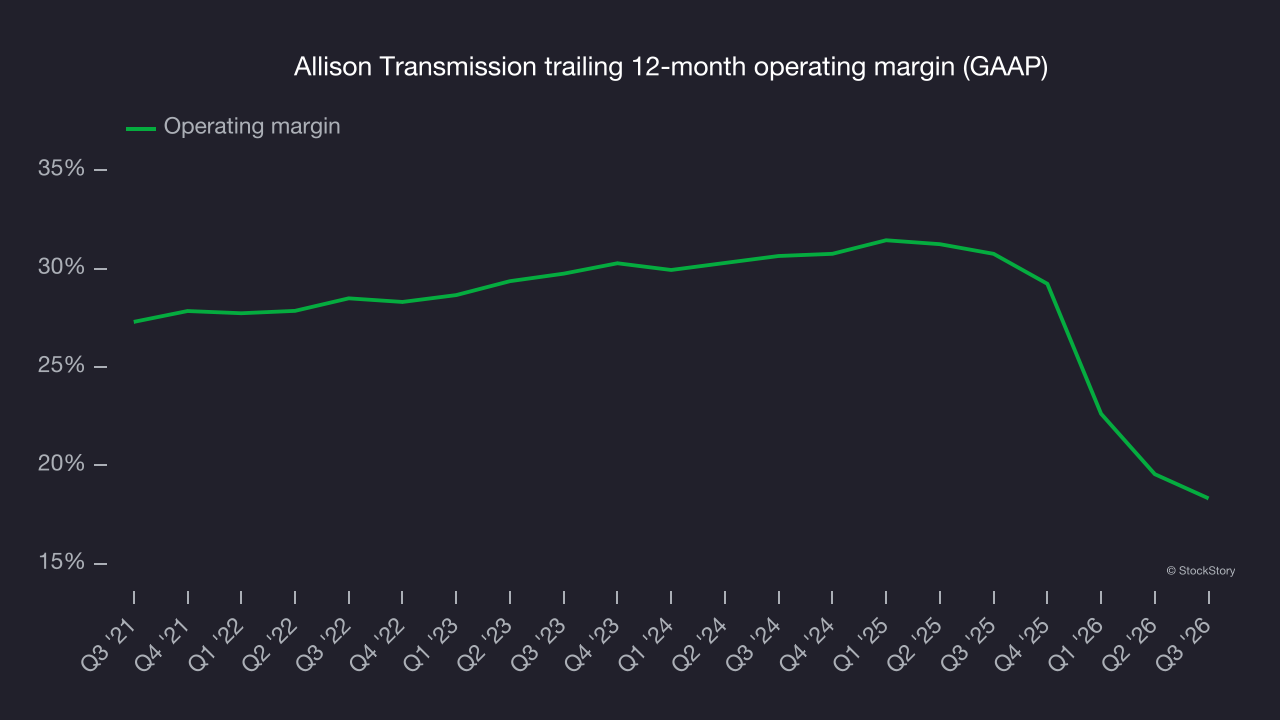
In Q3, Allison Transmission generated an operating margin of 19.8%, down 9.6 percentage points year on year. Since Allison Transmission’s gross margin decreased more than its operating margin, its recent inefficiencies appear to have been driven more by weaker leverage on its cost of sales than by increased marketing, R&D and administrative overhead expenses.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
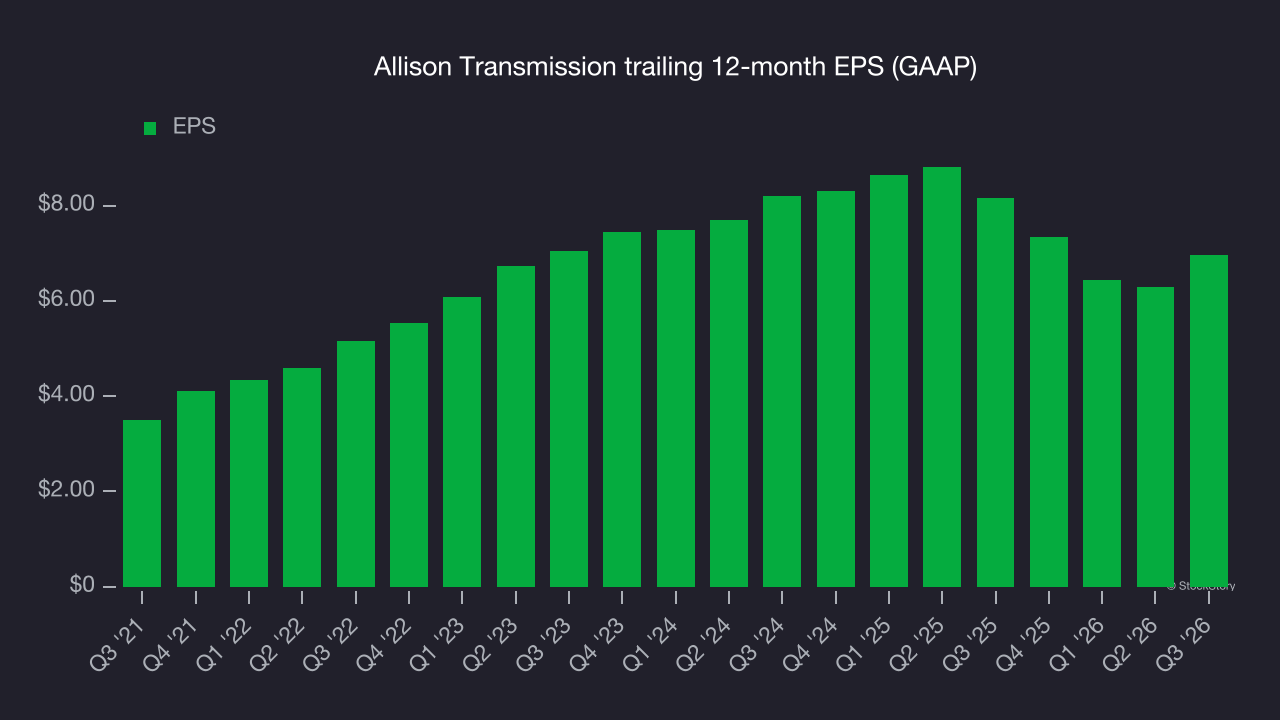
Allison Transmission’s EPS grew at a strong 14.8% compounded annual growth rate over the last five years. However, this performance was lower than its 18% annualized revenue growth, indicating the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
We can take a deeper look into Allison Transmission’s earnings quality to better understand the drivers of its performance. As we mentioned earlier, Allison Transmission’s operating margin declined by 10.2 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Allison Transmission, its two-year annual EPS declines of 7.9% mark a reversal from its seemingly healthy five-year trend. These shorter-term results were underwhelming, but its performance on other measures of financial health offers some reason to expect a return to earnings growth.
In Q3, Allison Transmission reported EPS of $2.30, up from $1.63 in the same quarter last year. This result was close to analysts’ consensus estimates. Over the next 12 months, Wall Street expects Allison Transmission’s full-year EPS to grow 50% from $6.97 to $10.45, according to S&P.
Key takeaways from Allison Transmission’s Q3 results
A sizable revenue beat and full-year EBITDA guidance above Wall Street’s consensus made this a solid quarter for Allison Transmission, with clear positives in both results and outlook. Revenue came in well ahead of analysts’ consensus estimates. Shares rose 2.5% to $115.99 immediately after the report.
Allison Transmission had a solid quarterly earnings result, but investors should also consider valuation and business quality when deciding whether to invest. For more on those factors, read our full research report here (it’s free).