

Since May 2026, Glacier Bancorp has been in a holding pattern, posting a small return of 0.8% while floating around $48.57. The stock also fell short of the S&P 500’s 7.2% gain during that period.
Is there a buying opportunity in Glacier Bancorp, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Glacier Bancorp not exciting?
We’re cautious about Glacier Bancorp. Here are three reasons why GBCI doesn’t excite us, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions.
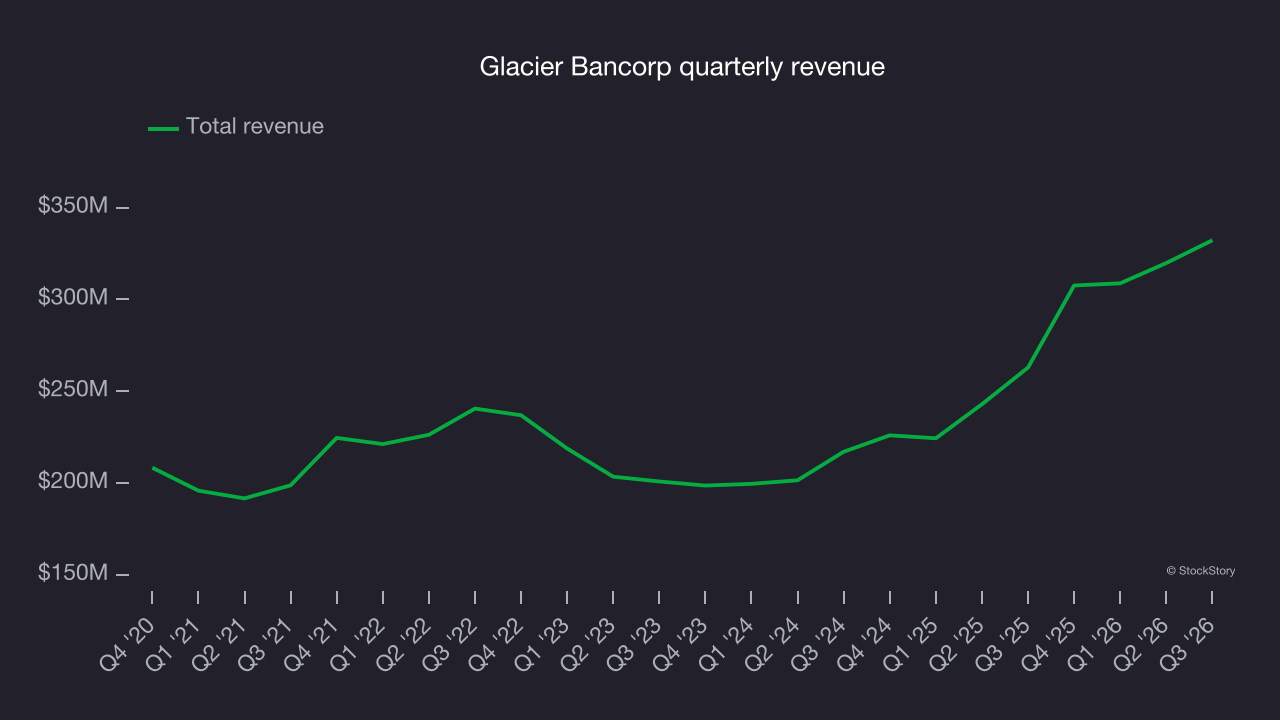
Over the last five years, Glacier Bancorp grew its revenue at a mediocre 9.8% compounded annual growth rate. This was below our standard for the banking sector.
2. EPS trending down
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
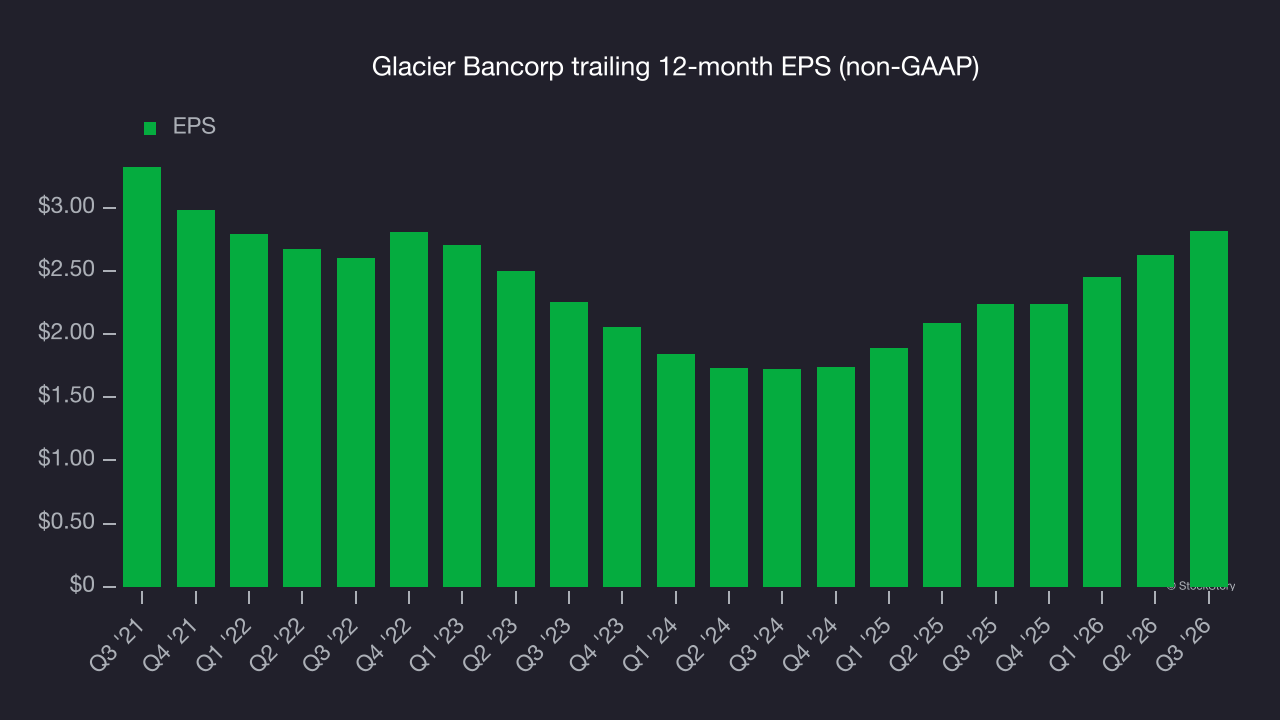
Sadly for Glacier Bancorp, its EPS declined by 3.3% annually over the last five years while its revenue grew by 9.8%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Substandard TBVPS growth indicates limited asset expansion
In the banking industry, tangible book value per share (TBVPS) provides the clearest picture of shareholder value, as it focuses on concrete assets while excluding intangible items that may not hold value during challenging times.
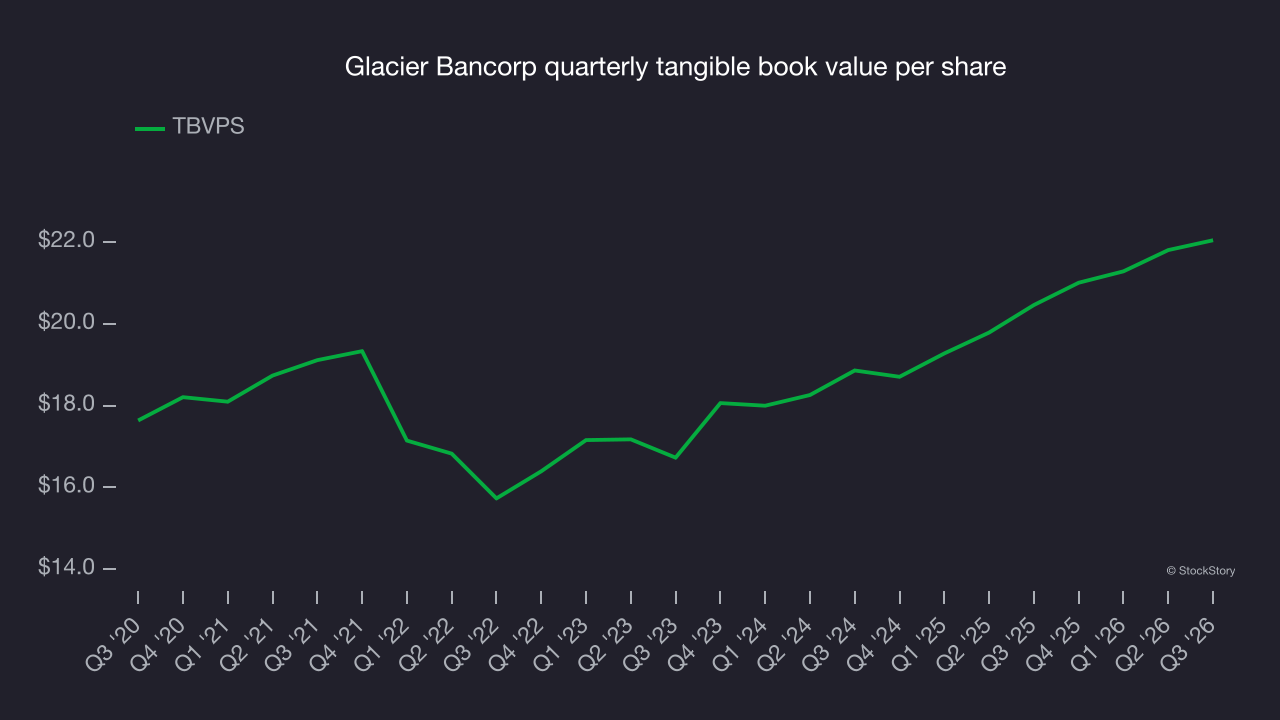
Disappointingly for investors, Glacier Bancorp’s TBVPS grew at a mediocre 8.1% annual clip over the last two years.
Final judgment
Glacier Bancorp isn’t a terrible business, but it isn’t one of our picks. With its shares underperforming the market lately, the stock trades at 1.4× forward P/B (or $48.57 per share). Investors with a higher risk tolerance might like the company, but we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. We’d recommend looking at one of Charlie Munger’s all-time favorite businesses.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.