

Shareholders of Nature's Sunshine would probably like to forget the past six months even happened. The stock dropped 55.2% and now trades at $12.29. This was partly driven by its softer quarterly results and may have investors wondering how to approach the situation.
Is there a buying opportunity in Nature's Sunshine, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why is Nature's Sunshine not exciting?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons you should be careful with NATR, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
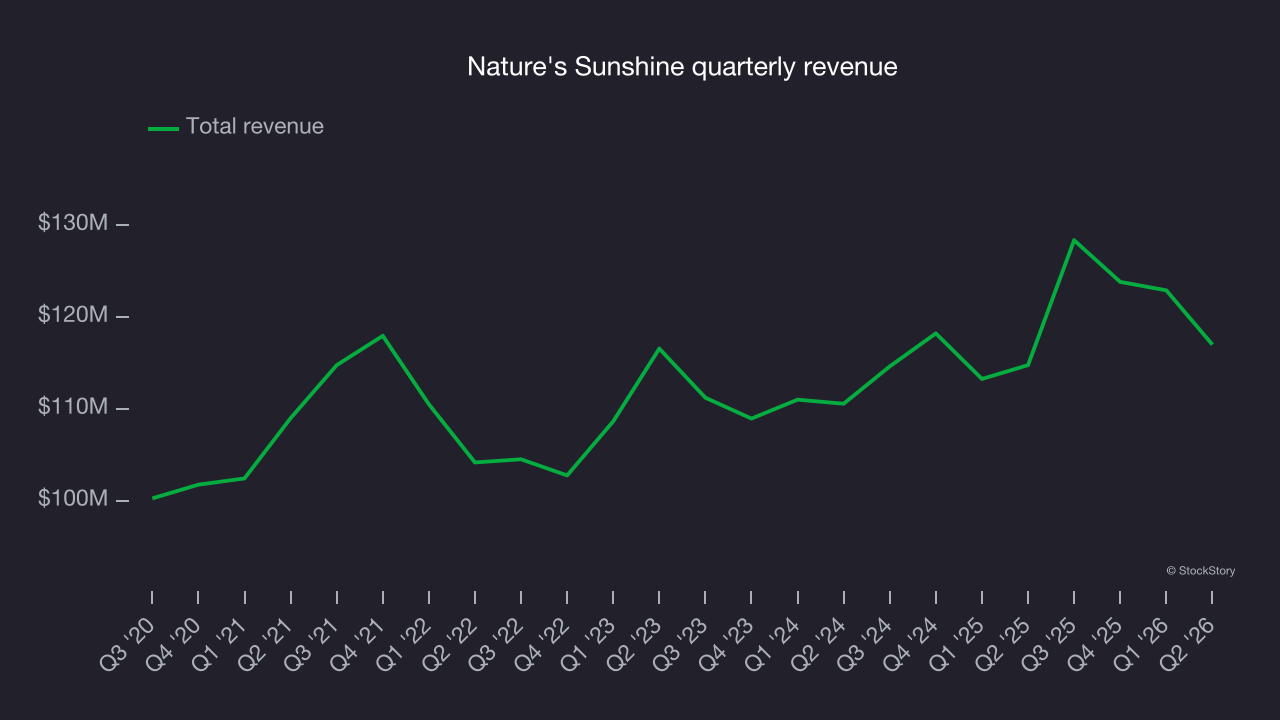
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Regrettably, Nature's Sunshine’s sales grew at a tepid 4.4% compounded annual growth rate over the last three years. This fell short of our benchmark for the consumer staples sector.
2. Fewer distribution channels limit its ceiling
With $492 million in revenue over the past 12 months, Nature's Sunshine is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
3. Projected revenue growth is slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Nature's Sunshine’s revenue to rise by 2.8%, according to S&P, a slight deceleration versus its 4.4% annualized growth for the past three years. This projection is underwhelming and implies its products will see some demand headwinds.
Final judgment
Nature's Sunshine isn’t a terrible business, but it doesn’t pass our bar. Following the recent decline, the stock trades at 11.3× forward P/E (or $12.29 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks we like more than Nature's Sunshine
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.