
Regional banking company Simmons First National (NASDAQ:SFNC) missed Wall Street’s revenue expectations in Q3 2026, but sales rose 6.3% year on year to $251.2 million. Its non-GAAP profit of $0.54 per share was in line with analysts’ consensus estimates.
Is now the time to buy Simmons First National? Find out by accessing our full research report, it’s free.
Simmons First National (SFNC) Q3 2026 Highlights:
- Net Interest Income: $204 million vs analyst estimates of $205.5 million (9.3% year-on-year growth, 0.8% miss)
- Net Interest Margin: 3.9% vs analyst estimates of 3.8% (8 basis point beat)
- Revenue: $251.2 million vs analyst estimates of $254.3 million (6.3% year-on-year growth, 1.2% miss)
- Efficiency Ratio: 71.6% vs analyst estimates of 55.2% (1,638 basis point miss)
- Adjusted EPS: $0.54 vs analyst estimates of $0.53 (in line)
- Tangible Book Value per Share: $13.52 vs analyst estimates of $14.51 (flat year on year, 6.8% miss)
- Market Capitalization: $3.19 billion
Company Overview
With roots dating back to 1903 and a presence across Arkansas, Kansas, Missouri, Oklahoma, Tennessee, and Texas, Simmons First National (NASDAQ:SFNC) is a regional bank holding company that provides banking and financial services to individuals and businesses.
Sales Growth
Two primary revenue streams drive bank earnings. While net interest income, which is earned by charging higher rates on loans than paid on deposits, forms the foundation, fee-based services across banking, credit, wealth management, and trading operations provide additional income. Over the last five years, Simmons First National grew its revenue at a sluggish 5.2% compounded annual growth rate. This fell short of our benchmark for the banking sector and is a rough starting point for our analysis.
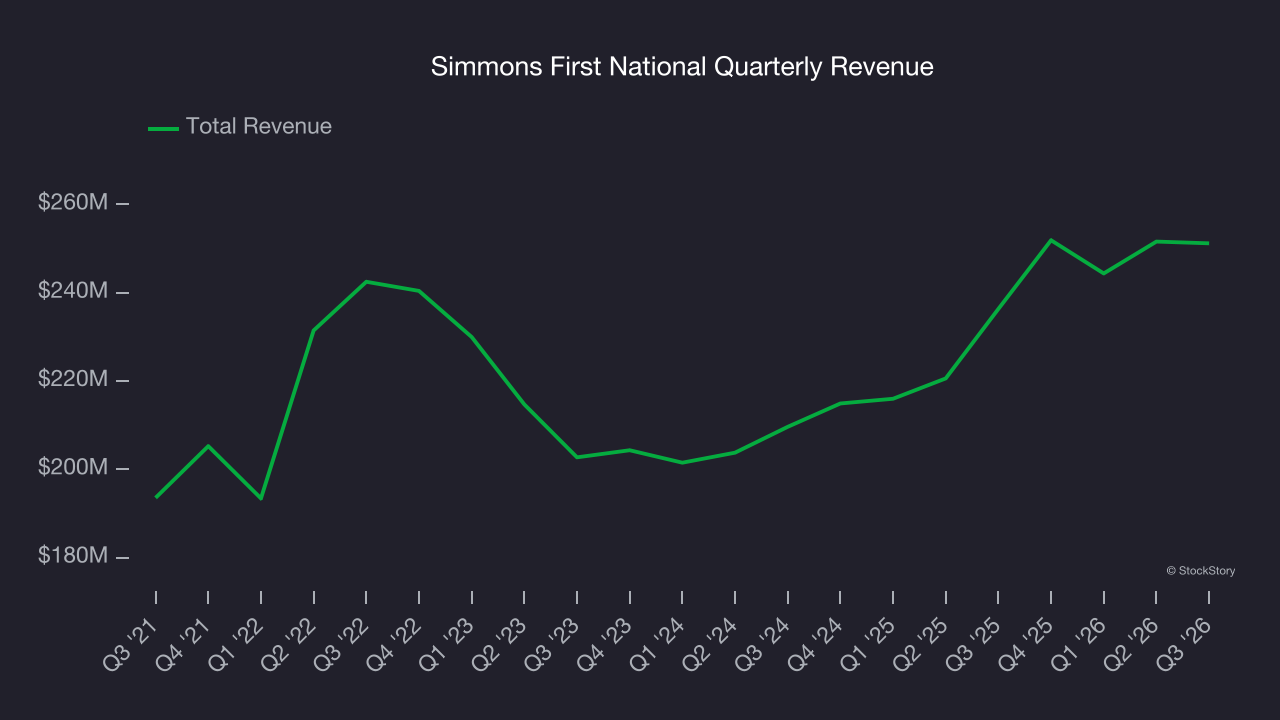
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Simmons First National’s annualized revenue growth of 10.4% over the last two years is above its five-year trend, suggesting some bright spots. 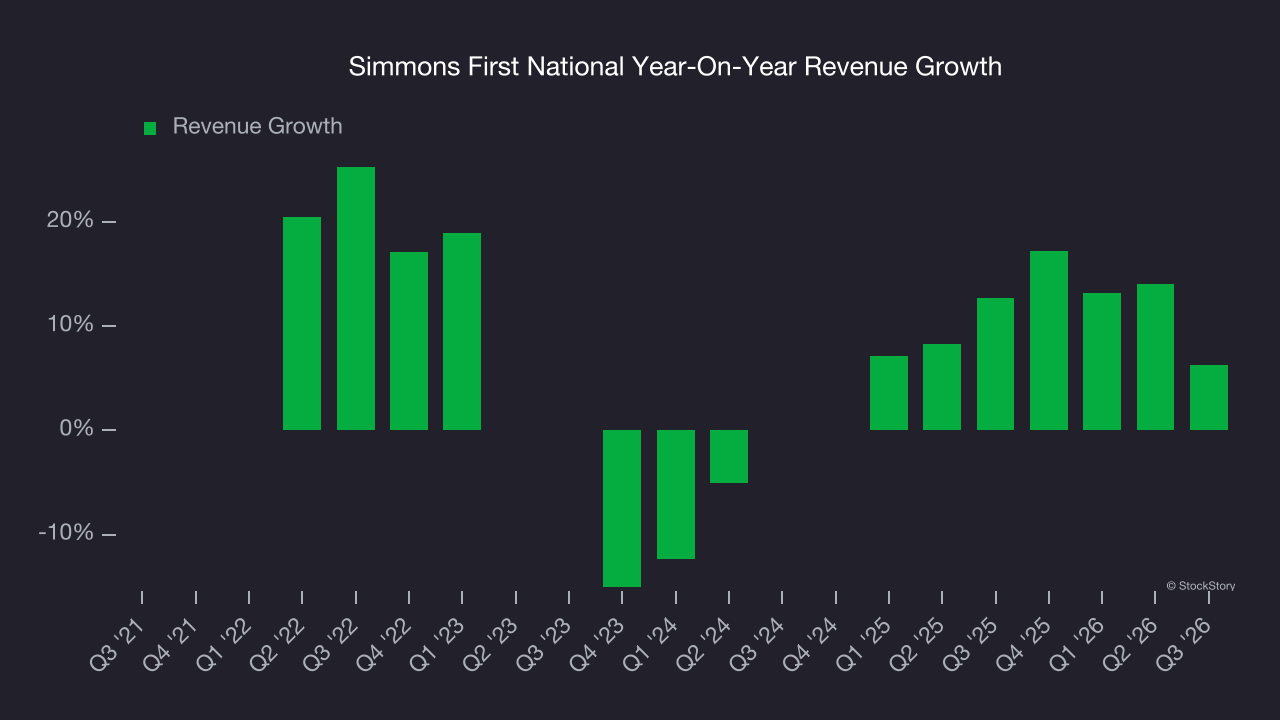 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Simmons First National’s revenue grew by 6.3% year on year to $251.2 million, missing Wall Street’s estimates.
Net interest income made up 80.9% of the company’s total revenue during the last five years, meaning Simmons First National barely relies on non-interest income to drive its overall growth.
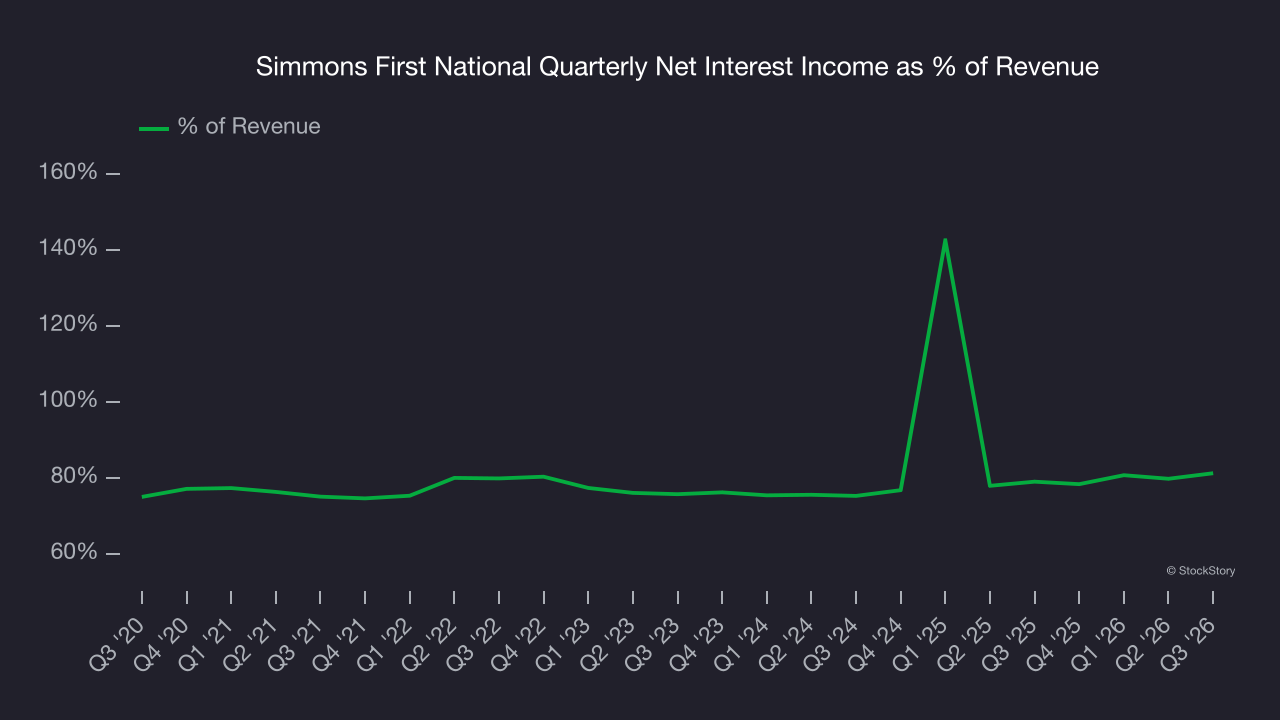
Our experience and research show the market cares primarily about a bank’s net interest income growth as non-interest income is considered a lower-quality and non-recurring revenue source.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Tangible Book Value Per Share (TBVPS)
The balance sheet drives banking profitability since earnings flow from the spread between borrowing and lending rates. As such, valuations for these companies concentrate on capital strength and sustainable equity accumulation potential.
Because of this, tangible book value per share (TBVPS) emerges as the critical performance benchmark. By excluding intangible assets with uncertain liquidation values, this metric captures real, liquid net worth per share. Other (and more commonly known) per-share metrics like EPS can sometimes be murky due to M&A or accounting rules allowing for loan losses to be spread out.
Simmons First National’s TBVPS declined at a 4.9% annual clip over the last five years. A turnaround doesn’t seem to be in sight as its TBVPS also dropped by 10.2% annually over the last two years ($16.78 to $13.52 per share).
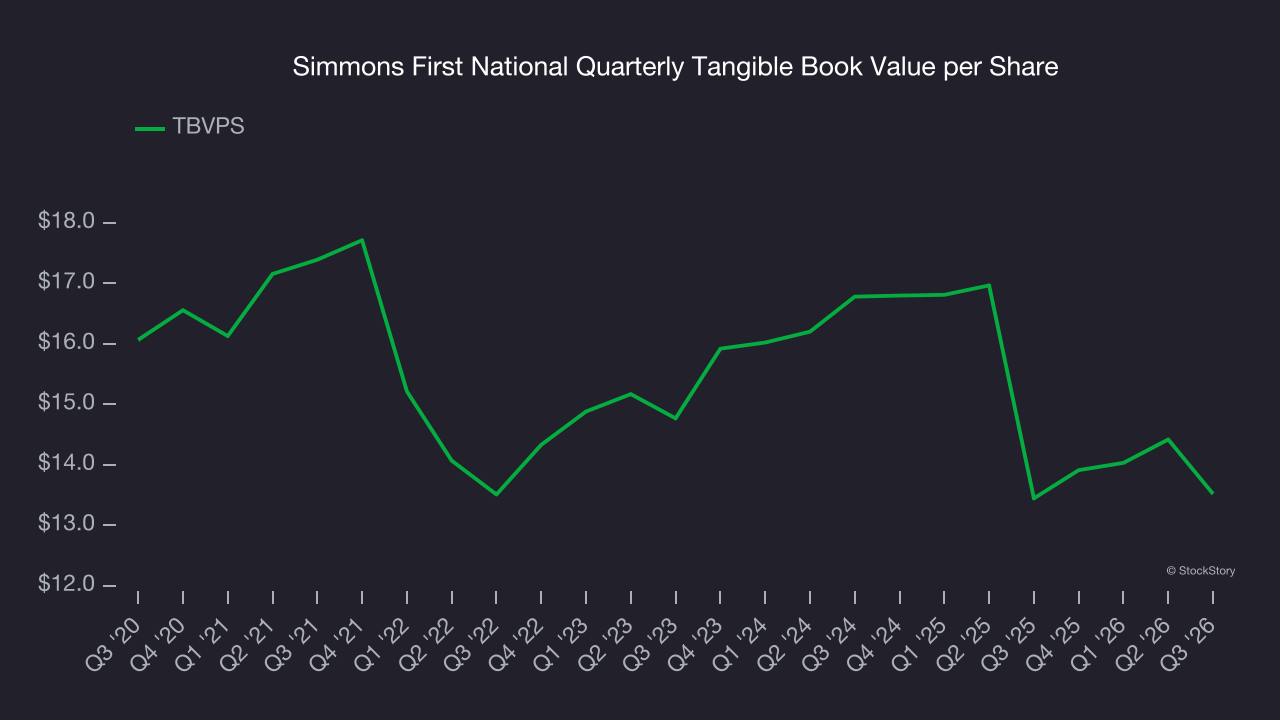
Over the next 12 months, Consensus estimates call for Simmons First National’s TBVPS to grow by 18.6% to $16.04, top-notch growth rate.
Key Takeaways from Simmons First National’s Q3 Results
We struggled to find many positives in these results. Its tangible book value per share missed and its revenue fell slightly short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock traded up 2% to $22.71 immediately after reporting.
So should you invest in Simmons First National right now? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. We cover that in our actionable full research report which you can read here (it’s free).