

Athletic apparel brand Nike (NYSE:NKE) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q1 2027), with sales falling 4.3% year on year to $11.21 billion. Its GAAP profit of $0.48 per share was 9.9% above analysts’ consensus estimates.
Is now the time to buy Nike? Find out by accessing our full research report, it’s free.
Nike (NKE) Q3 CY2026 Highlights:
- Revenue: $11.21 billion vs analyst estimates of $11.33 billion (4.3% year-on-year decline, 1% miss)
- EPS (GAAP): $0.48 vs analyst estimates of $0.44 (9.9% beat)
- Operating Margin: 8.1%, in line with the same quarter last year
- Constant Currency Revenue fell 5% year on year (-1% in the same quarter last year)
- Market Capitalization: $52.52 billion
- Outlook: Revenues are expected to decline high-single digits in fiscal 2027. Non-GAAP Diluted earnings per share is expected to be in the range of $1.15 to $1.35, which excludes $0.15 of restructuring expenses for fiscal 2027.
Company Overview
Originally selling Japanese Onitsuka Tiger sneakers as Blue Ribbon Sports, Nike (NYSE:NKE) is a global titan in athletic footwear, apparel, equipment, and accessories.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, Nike struggled to consistently increase demand as its $45.89 billion of sales for the trailing 12 months was close to its revenue five years ago. This wasn’t a great result and suggests it’s a low quality business.
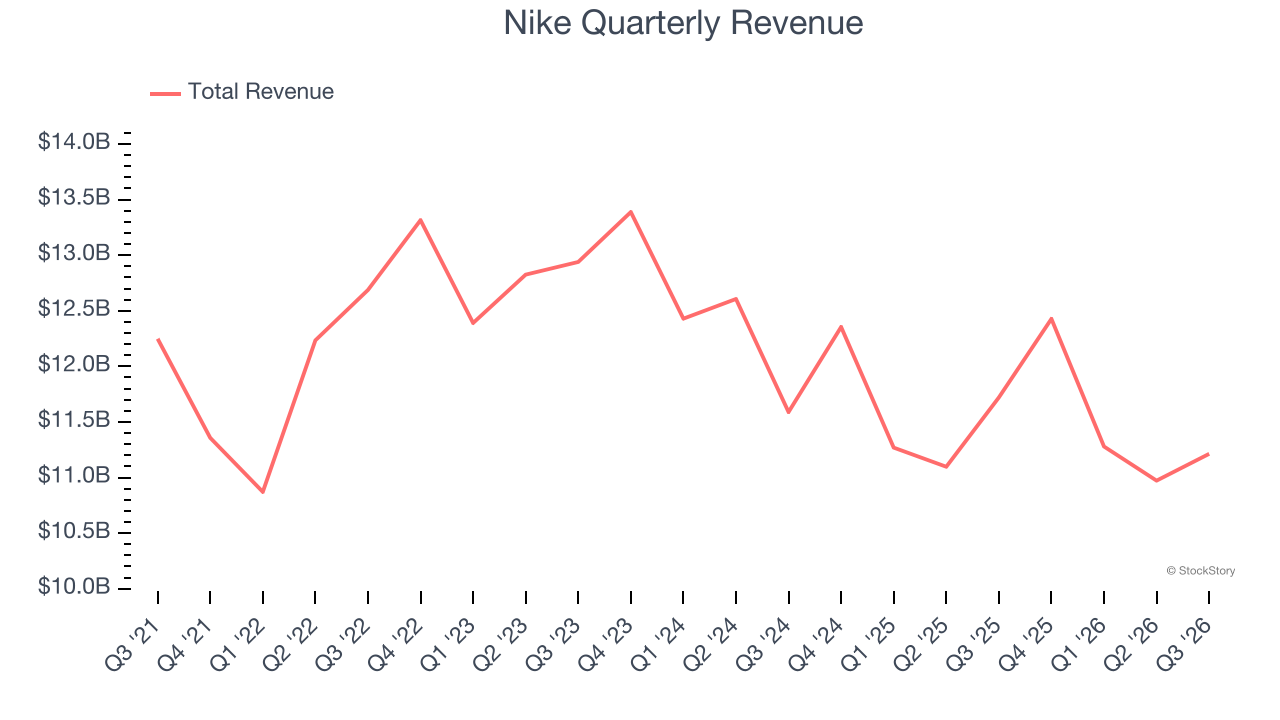
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Nike’s recent performance shows its demand remained suppressed as its revenue has declined by 4.2% annually over the last two years. 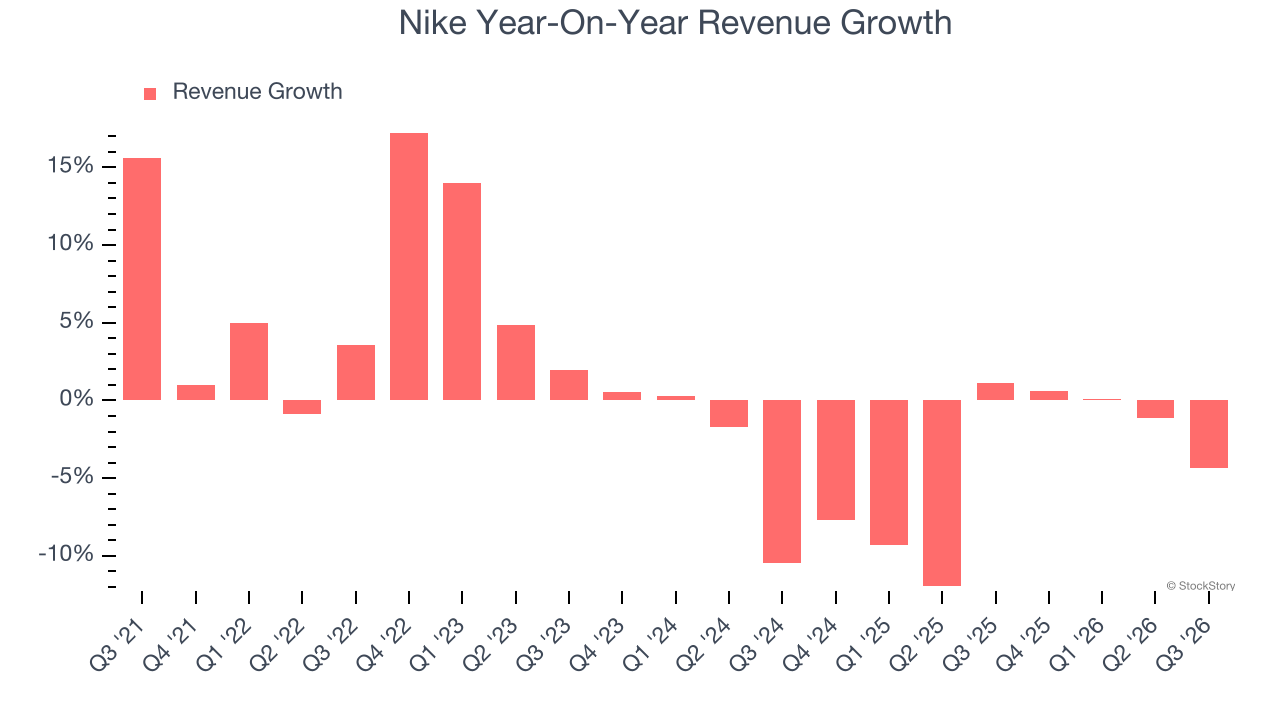
Nike also reports sales performance excluding currency movements, which are outside the company’s control and not indicative of demand. Over the last two years, its constant currency sales averaged 4.8% year-on-year declines. Because this number aligns with its reported revenue growth, we can see that foreign exchange has not had a meaningful impact on topline. 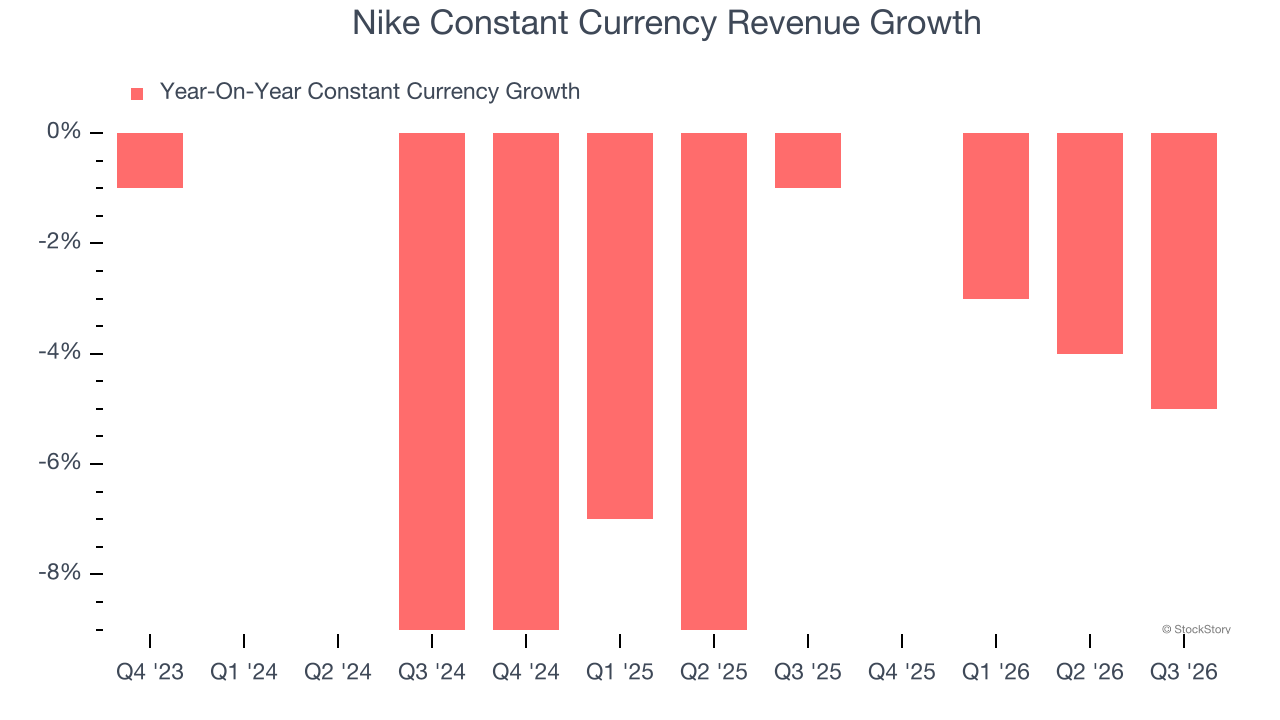
This quarter, Nike missed Wall Street’s estimates and reported a rather uninspiring 4.3% year-on-year revenue decline, generating $11.21 billion of revenue.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months. Although this projection implies its newer products and services will catalyze better top-line performance, it is still below the sector average.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating Margin
Nike’s operating margin has generally stayed the same over the last 12 months, and we generally like to see margin increases due to economies of scale and cost efficiency over time.
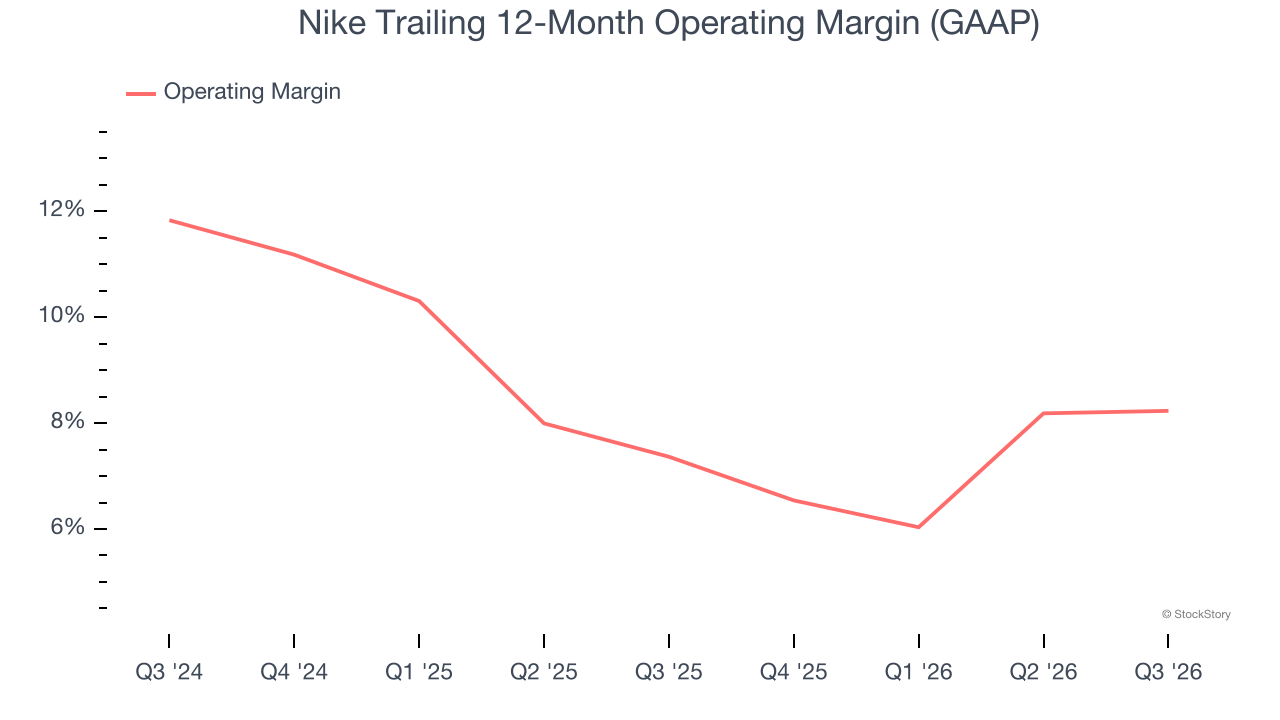
In Q3, Nike generated an operating margin profit margin of 8.1%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings Per Share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Sadly for Nike, its EPS declined by 11.1% annually over the last five years while its revenue was flat. This tells us the company struggled because its fixed cost base made it difficult to adjust to choppy demand.
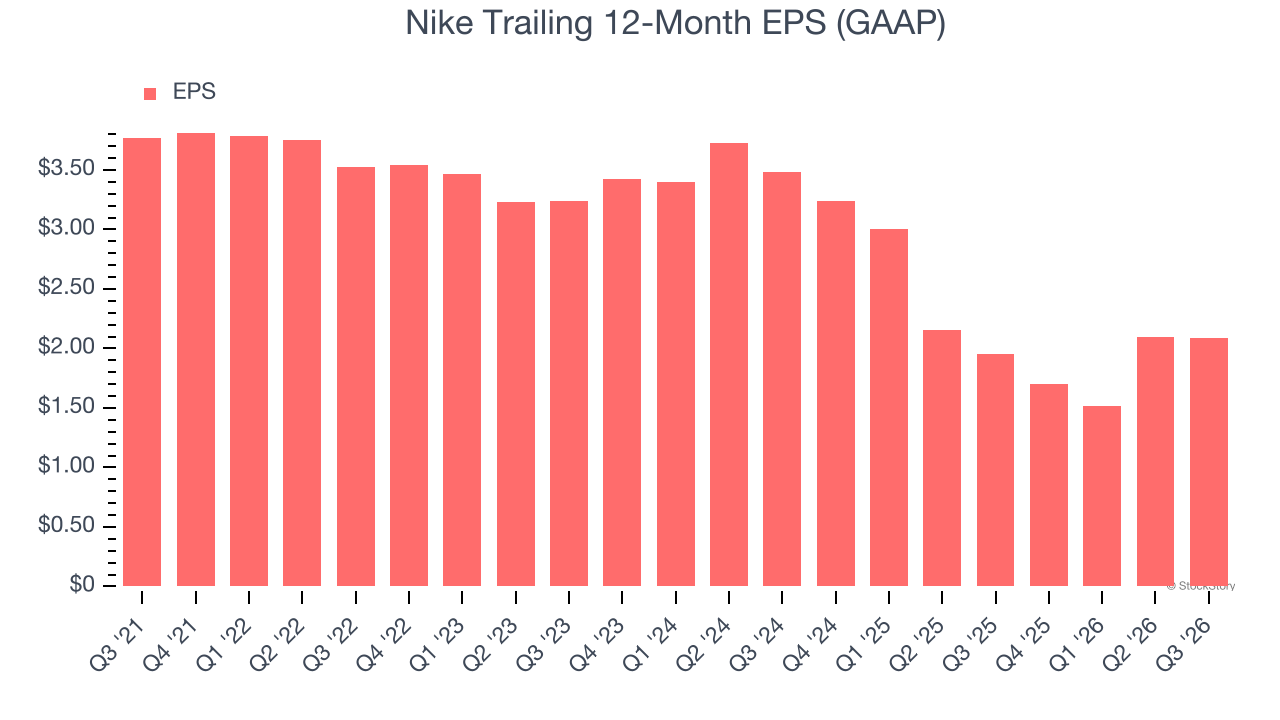
In Q3, Nike reported EPS of $0.48, down from $0.49 in the same quarter last year. Despite falling year on year, this print beat analysts’ estimates by 9.9%. Over the next 12 months, Wall Street expects Nike’s full-year EPS to shrink by 15.9% from $2.09 to $1.76.
Key Takeaways from Nike’s Q3 Results
It was good to see Nike beat analysts’ EPS expectations this quarter. On the other hand, its revenue slightly missed and Fiscal 2027 outlook came in below expectations. Zooming out, we think this was a mixed quarter. Investors were likely hoping for more, and shares traded down 6.3% to $33.00 immediately after reporting.
Should you buy the stock or not? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).